Medicare Supplement Plans in California 2027: Birthday Rule, Regional Prices and State-Only Rights
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 29, 2026
Medicare Supplement plans in California are sold by about 22 insurers, and state law gives every policyholder 60 days starting on their birthday each year to switch to a plan with the same or fewer benefits without health questions. Prices depend heavily on where you live: one large California insurer’s July 2026 rates for Plan G at 65 range from $188 to $227 a month by region.
2027 by the Numbers
60 days
California birthday window, starting on your birthday each year (CA Department of Insurance)
$468
yearly Plan G gap at 65 between one insurer’s cheapest and priciest California region, July 2026 rates (our math)
598,000
Original Medicare beneficiaries in California with Medigap coverage in 2023 (healthinsurance.org)
$3,050
2027 high-deductible Plan G deductible (CMS)
California has more people on Medicare than any other state, and its Medigap rules go further than federal law in several ways. The biggest is the birthday rule, but California also protects people who lose employer coverage, people under 65, and anyone who wants a plan with extra perks such as dental or vision.
This guide covers the rules that are unique to California, shows how much your region changes a Plan G price, and explains how to use the state’s own rate tool. For a quick look at what each letter covers, keep our Medicare Supplement comparison chart for 2027 open in another tab.
Compare 2027 California Medigap Rates
California's Birthday Rule Runs 60 Days From Your Birthday
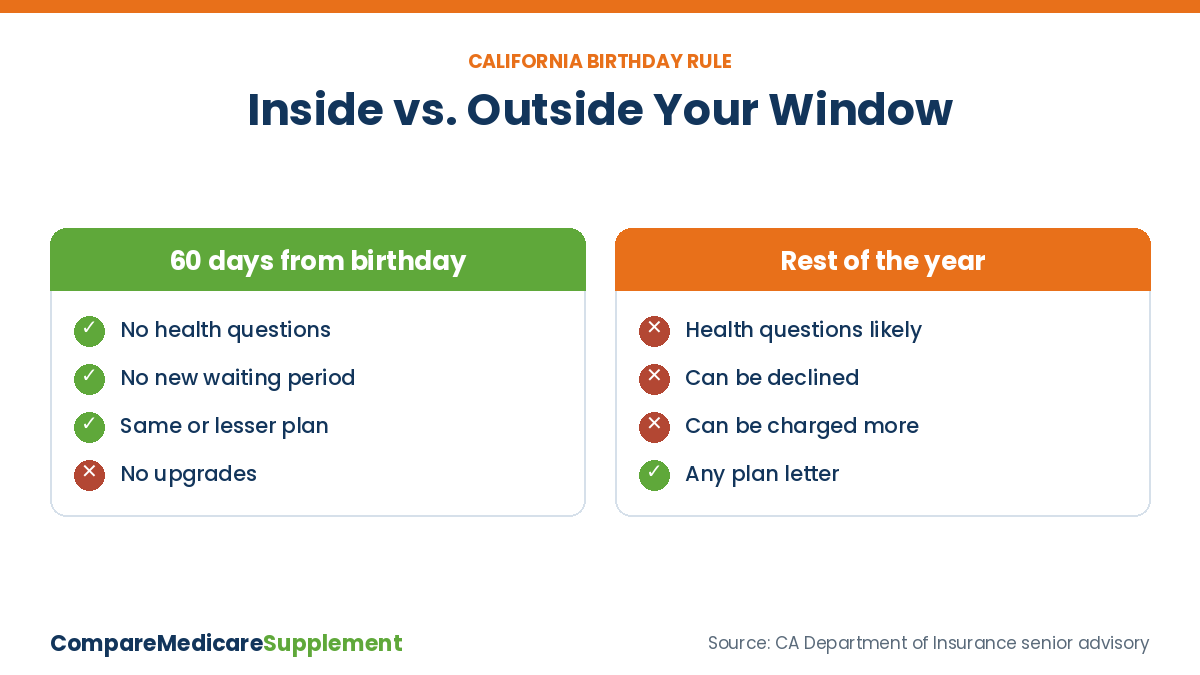
The California Department of Insurance (CDI) says that if you already have Medigap insurance, “you have 60 days of open enrollment following your birthday each year.” During that time you can buy a new policy with the same or lesser benefits, and the insurer cannot ask about your health or start a new waiting period. California first set this window at 30 days and lengthened it to 60 days starting in 2020.
| If your birthday is | Your window starts | Last day to have a new plan in place (our math) |
|---|---|---|
| February 1, 2027 | February 1, 2027 | April 1, 2027 |
| June 15, 2027 | June 15, 2027 | August 13, 2027 |
| November 2, 2027 | November 2, 2027 | December 31, 2027 |
Counting your birthday as day 1 of 60. Confirm the exact end date with the insurer, and apply well before it.
Watch your mail: California law requires your insurer to notify you of this right 30 to 60 days before your window opens. If that letter arrives, it is your reminder to compare prices.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Plan G With Extras Still Counts as Plan G
Some California insurers sell versions of their plans with added perks, often called “extra” plans, that bundle things like dental, vision or fitness benefits. That raises a fair question: if you own a Plan G with extras, can you use the birthday rule to move to a plain Plan G?
Extras are not counted. According to an analysis in California Broker Magazine by Bonnie Burns, a longtime California Medigap consumer advocate, insurers may not count extra benefits like vision or dental when deciding “same or lesser,” so a plain Plan G matches a Plan G with extras.
The reverse can work too. A Plan G with extras can generally replace a plain Plan G, because the core Medigap benefits are identical.
High-deductible plans are narrow. High-deductible Plan F can only be replaced with high-deductible Plan F under California’s rule.
Before you drop a plan with extras, add up what you actually use. If you never touch the dental or vision perks, a plain Plan G from another company may cost less.
Extra Guaranteed Rights Only California Gives You
Federal law already protects you in your first six months on Part B and in certain other events. California adds more. The CDI senior advisory lists these state-level protections:
Your employer plan stops paying the 20%. You can buy a Medigap policy with no health screening or new waiting period when an employer stops providing coverage that pays all of Medicare’s 20% coinsurance.
Your COBRA or CalCOBRA ends. Open enrollment rights also apply when you lose that extension of employer coverage.
Your Medi-Cal changes to share of cost. If higher income or assets leave you eligible only for Medi-Cal with a share of cost, you gain open enrollment rights.
No medical questions allowed. When you have one of these rights, the insurer cannot ask for medical information on your application.
Leaving Medicare Advantage: California law also includes an added 60-day Medigap open enrollment period for some people whose Medicare Advantage coverage ends. Check the exact rules with HICAP or a licensed agent before you leave a plan.
Where You Live in California Changes Your Price
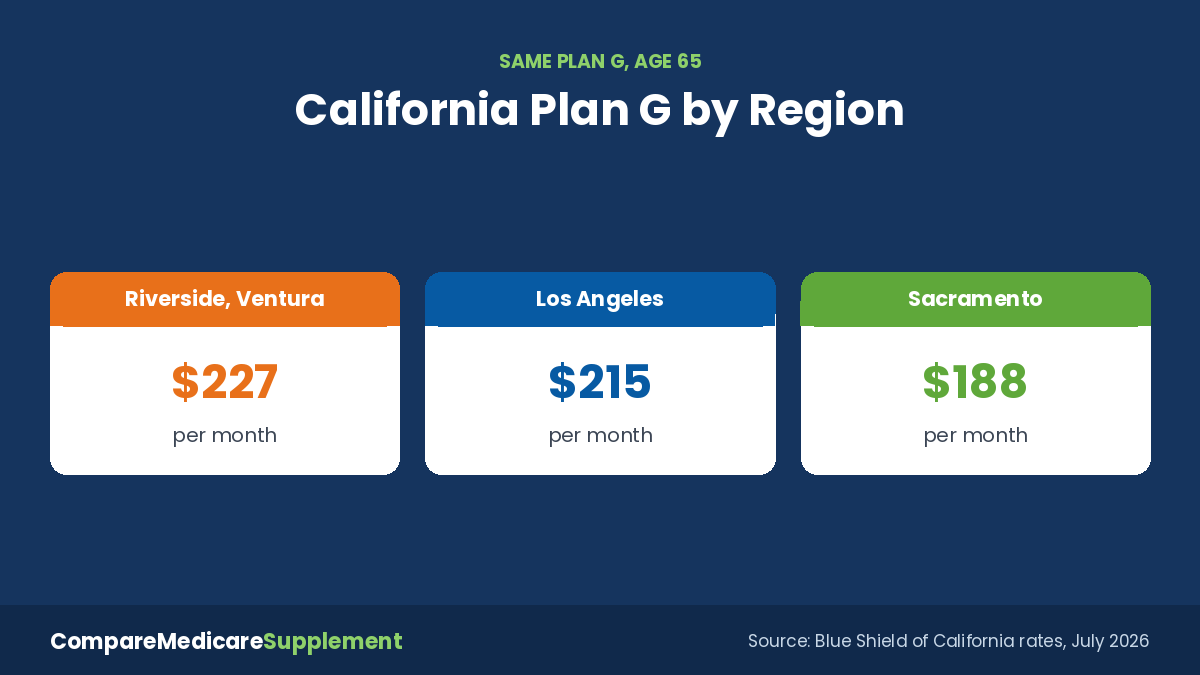
California is too big for one price. Most insurers split the state into rating regions. To show the effect, we read Blue Shield of California’s Medicare Supplement rate sheet effective July 1, 2026, for a 65-year-old non-tobacco user.
| Region (sample counties) | Plan G at 65 | Plan N at 65 |
|---|---|---|
| Region 4: Riverside, Ventura | $227 | $206 |
| Region 2: Orange | $222 | $188 |
| Region 1: most of Los Angeles | $215 | $193 |
| Region 7: Alameda, Contra Costa, Napa | $199 | $181 |
| Region 8: San Francisco, Santa Clara, Fresno | $191 | $171 |
| Region 9: Sacramento, Marin, El Dorado | $188 | $169 |
Source: Blue Shield of California Medicare Supplement rate sheet, all regions, effective July 1, 2026, single-party monthly dues before its 7% household discount. Six of nine regions shown.
That is a $39 a month, or $468 a year, gap for the same company and the same Plan G, based only on address. The sheet also uses attained-age pricing, so these prices rise each year as you get older.
How to Price California Plans With the State's Own Tool
California law requires the Insurance Commissioner to publish an annual Medigap rate guide with sample rates, pricing methods and waiting periods for each company. Today it is an online search on the CDI website called the 2026 Guide on Medicare Supplement Insurance.
Choose individual coverage. Pick the individual policy type unless you are buying through a group.
Select your age and enter your ZIP code and county. The tool shows yearly premiums approved by the state for a non-tobacco California resident.
Compare one letter at a time. Line up Plan G, then Plan N, across companies. Divide the yearly figure by 12 to compare with monthly quotes.
Check the pricing method. Attained-age plans rise with your age. Issue-age plans are priced on the age you buy at.
Companies on our list to compare in California include HealthSpring, Mutual of Omaha, Wellabe and Blue Shield of California. Our best Medicare Supplement plans for 2027 guide explains how to weigh price against rate history.
California Medigap Rules for People Under 65
Nearly 464,000 Californians on Medicare are under 65, most because of a disability. California requires Medigap insurers that sell to people 65 and older to offer certain plans to younger members too.
| Under-65 rule in California | What it means for you |
|---|---|
| Plans that must be offered | At least A, B, D and G, plus K or L and M or N if the insurer sells them |
| Kidney failure (ESRD) | These required-offer rules do not apply |
| Price | Insurers may charge more than they charge people 65 and older |
| Turning 65 | You get the federal six-month Medigap open enrollment period at standard rates |
Sources: healthinsurance.org California Medicare guide (updated September 2026) and California Broker Magazine.
Under-65 prices can be high, so many younger members compare a Medigap quote with a Medicare Advantage plan before deciding, then revisit Medigap at 65.
Bottom Line
California gives Medigap buyers more protection than most states: 60 days every year starting on your birthday, extra guaranteed rights when employer or Medi-Cal coverage changes, and required plans for people under 65. Use those rights. Price your exact region, compare the same letter across companies, and check again every birthday.
Get 2027 Medicare Supplement prices for your California ZIP code
Medicare Supplement Plans in California — Frequently Asked Questions
➤ Does California’s Medigap birthday window start before my birthday?
No. The window starts on your birthday and lasts 60 days, according to the California Department of Insurance. Some other states open their window before the birthday, but California does not.
➤ Can I switch from Plan G to Plan N on my California birthday?
Generally yes, because Plan N has fewer benefits than Plan G. Moving from Plan N up to Plan G is not covered by the birthday rule.
➤ Will my insurer remind me about my birthday window?
It should. California law requires the insurer to notify you of your rights 30 to 60 days before the window begins.
➤ Is a Plan G with dental and vision extras treated differently in California?
Not for the birthday rule. Extra benefits are not counted when deciding “same or lesser,” so a Plan G with extras and a plain Plan G match.
➤ Why does Plan G cost more in Riverside than in Sacramento?
Insurers set prices by region. On Blue Shield of California’s July 2026 rate sheet, Plan G at 65 was $227 a month in Riverside and Ventura counties and $188 in the Sacramento region.
➤ My employer plan is ending. Can I get Medigap without health questions?
Often, yes. California gives you guaranteed issue when an employer stops coverage that pays Medicare’s 20% coinsurance, and when COBRA or CalCOBRA ends.
➤ Where can I look up official California Medigap prices?
The Department of Insurance runs an online rate guide. Enter your age, ZIP code and county to see yearly premiums the state has approved for each company.
➤ Who gives free Medicare counseling in California?
HICAP, the Health Insurance Counseling and Advocacy Program, offers free, unbiased help in every county. A licensed agent can also compare several companies for you at no cost.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll