Medicare Supplement Plan F 2027: Who Can Still Buy It and Whether to Keep It
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 29, 2026
Medicare Supplement Plan F can only be bought in 2027 by people who were eligible for Medicare before January 1, 2020, and anyone who already has Plan F can keep it for life as long as they pay the premium. Plan F pays every Medicare gap, including the Part B deductible projected at $292 for 2027, but in official rate data its extra premium over Plan G usually costs more than that deductible.
2027 by the Numbers
Jan 1, 2020
Medicare eligibility cutoff: eligible before this date to buy Plan F (federal law, MACRA)
$3,050
2027 high-deductible Plan F deductible (CMS)
$292
projected 2027 Part B deductible, the one gap F pays that G does not (Trustees)
5 of 5
companies we checked where Plan F cost more per year than the $292 deductible at age 75 (Maryland July 2026 guide, our math)
Plan F used to be the plan almost everyone bought. Then Congress closed it to new Medicare enrollees starting in 2020, so the people who hold it today are getting older, and nobody new is joining the group. That raises two real questions for 2027: can you still get Plan F, and if you have it, is it still worth what you pay?
This page answers both with real numbers. For the plan that replaced F for most new enrollees, see our Medicare Supplement Plan G 2027 guide, and for every plan letter in one table, the 2027 comparison chart.
Check 2027 Plan F and Plan G Rates
Who Is Still Allowed to Buy Plan F in 2027
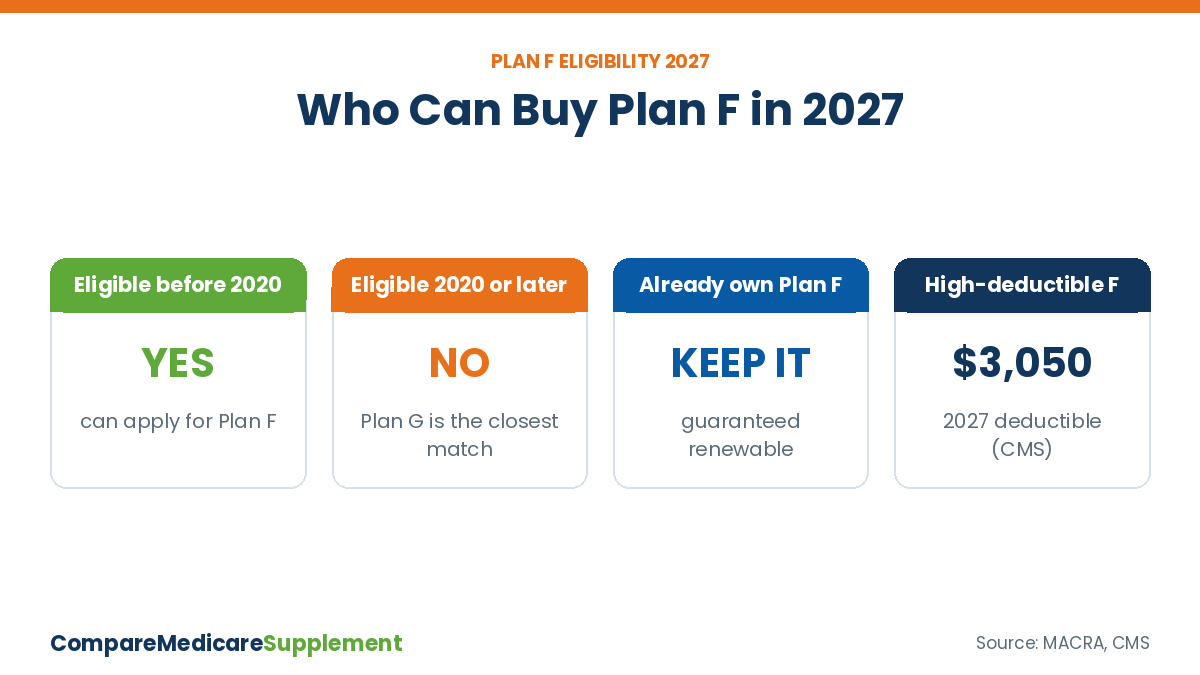
The rule comes from the Medicare Access and CHIP Reauthorization Act (MACRA). Since January 1, 2020, Medigap plans sold to people newly eligible for Medicare cannot pay the Part B deductible. That closed Plan F and Plan C, plus high-deductible F, to anyone whose Medicare eligibility started on or after that date.
You turned 65 before 2020. You can apply for Plan F in 2027, even if you delayed Part B and only enroll now.
You had Medicare from a disability before 2020. Eligibility counts from when you first qualified, not from your 65th birthday.
You first became eligible in 2020 or later. Plan F is off the table. Plan G is the closest match.
You already own Plan F. Nothing forces you off it. Medigap policies are guaranteed renewable while you pay the premium.
Age check: Anyone who reached 65 before 2020 is at least 72 by the end of 2027. That is why we use age-75 rates below, not age-65 rates. Most people shopping for Plan F today are well past 65.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
What Plan F Pays in 2027
Plan F is the only plan still on the market, for those who qualify, that leaves you with no Medicare-approved costs at all. You pay your monthly premiums and that is it.
| 2027 Medicare cost | Amount | Plan F pays |
|---|---|---|
| Part B deductible | $292 (projected) | Yes, in full |
| Part A hospital deductible | $1,788 per benefit period (projected) | Yes, in full |
| Part B 20% coinsurance | No yearly cap in Original Medicare | Yes, in full |
| Part B excess charges | Up to 15% above Medicare’s amount | Yes, in full |
| Emergency care abroad | Full bill outside the U.S. | 80% after a $250 deductible, to plan limits |
2027 Part A and B deductibles are Medicare Trustees projections; CMS announces final amounts, usually in November.
Plan F still does not pay for prescriptions, routine dental, eyeglasses, hearing aids or long-term custodial care. You need a separate Part D drug plan.
High-Deductible Plan F: The $3,050 Version
High-deductible Plan F has the same benefits as Plan F, but you pay the first $3,050 of covered costs in 2027 before it pays anything. In return, the premium is a fraction of regular Plan F. It follows the same eligibility rule, so only people eligible for Medicare before 2020 can buy it.
| Maryland, man 75 (July 2026) | Monthly premium | Worst-case 2027 year (our math) |
|---|---|---|
| Medico Plan F | $312 | $3,744 premium + $0 = $3,744 |
| Medico high-deductible F | $94 | $1,128 premium + $3,050 = $4,178 |
Source: Maryland Insurance Administration Medicare Supplement rate guide, rates as of July 1, 2026, male preferred, age 75. Worst case = 12 months of premium plus the most you could pay in covered costs.
In a healthy year, the high-deductible version saved $2,616 in premiums in this example. In a year with heavy medical bills, it cost $434 more. Few companies sell it, so check whether it is offered in your state at all.
Keep Plan F or Switch to Plan G? Our Rate Math
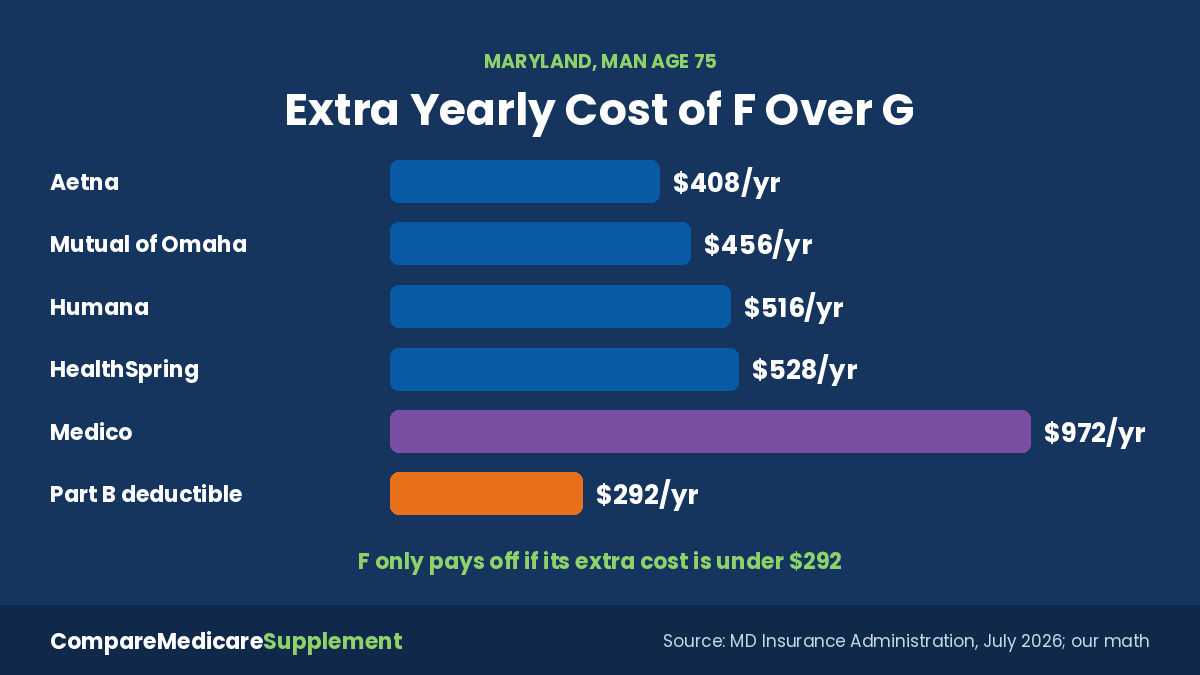
Plan F and Plan G differ by one item: F pays the Part B deductible. So the test is simple. If F costs more per year than the deductible, you are paying extra for nothing. We used Maryland’s official July 2026 rate guide, which lists Plan F and Plan G side by side for every company, at age 75.
| Company (Maryland, man 75) | Plan F / month | Plan G / month | Extra cost of F per year | Minus $292 deductible F pays |
|---|---|---|---|---|
| Aetna | $409 | $375 | $408 | F costs $116 more |
| Mutual of Omaha | $407 | $369 | $456 | F costs $164 more |
| Humana | $301 | $258 | $516 | F costs $224 more |
| HealthSpring | $359 | $315 | $528 | F costs $236 more |
| Medico | $312 | $231 | $972 | F costs $680 more |
Source: Maryland Insurance Administration rate guide, rates as of July 1, 2026, male preferred or non-tobacco, age 75. Our math. Prices in your state will differ.
At every company we checked, keeping Plan F cost more than the deductible it saves. At age 65 the gap is usually smaller. HealthSpring’s age-65 rates were $264 for F and $241 for G, a $276 yearly gap, just under the deductible. But hardly anyone buying F today is 65.
Broker tip: Do not cancel Plan F until a Plan G policy is approved in writing. Outside your open enrollment or a guaranteed issue right, most companies can ask health questions for Plan G, and you could be turned down.
When Switching From F to G Is Easier
Check for a birthday or anniversary rule. Some states give you a yearly window to move to a plan with equal or fewer benefits without health questions. Plan G has fewer benefits than F, so it usually qualifies.
Check your state for year-round rights. A handful of states let you change Medigap plans any time of year under their own rules.
Get Plan G quotes at your current age. Compare at least three companies. The cheapest F company is not always the cheapest G company.
Apply, wait for approval, then cancel F. Ask the new company for your policy start date and cancel F so it ends the day before.
Our guide to comparing Medicare Supplement plans explains pricing methods and rate history, which matter more as you get older.
Mutual of Omaha Plan F and Other Companies
Plan F benefits are identical from every company, so the company changes only the price, the discounts and the service. Mutual of Omaha is one of the names people search most for Plan F. In Maryland’s July 2026 guide, its Plan F for a non-tobacco man was $320 a month at 65 and $407 at 75, with a 12% household discount for those who qualify.
Mutual of Omaha. Sells Plan F to people eligible before 2020, plus Plan G and N for everyone.
HealthSpring (formerly Cigna). Lists Plan F and high-deductible F for pre-2020 eligibles on its Medicare Supplement page.
Humana and Aetna. Both listed Plan F rates in Maryland’s 2026 guide.
Medico. One of the few companies in that guide that also listed high-deductible F.
If Plan F prices feel high, Plan N is the other plan many long-time F holders look at. See what it leaves you to pay in our Medigap Plan N guide.
Bottom Line
Plan F is still for sale in 2027, but only to people eligible for Medicare before 2020, and current owners can keep it as long as they pay. In Maryland’s official rate data, F cost more per year than the $292 deductible it covers at every company we checked, so if you are healthy enough to pass health questions, compare Plan G quotes before your next renewal.
See 2027 Plan F and Plan G prices for your ZIP code
Medicare Supplement Plan F 2027 — Frequently Asked Questions
➤ Can I enroll in Plan F if I turned 65 in 2019 but never signed up for Part B?
Yes. What matters is when you first became eligible for Medicare, not when you enrolled. If you were eligible before January 1, 2020, you can still apply for Plan F.
➤ Will my Plan F be canceled because it is closed to new people?
No. Medigap policies are guaranteed renewable, so your company cannot cancel Plan F as long as you pay your premiums and told the truth on your application.
➤ Why does my Plan F premium keep going up?
Premiums can rise with your age, medical inflation and each company’s rate filings. Because no new people can join Plan F, the group of members only gets older, which can add pressure on rates over time.
➤ How much is Mutual of Omaha Plan F?
It depends on your state, age, sex and tobacco use. In Maryland’s July 2026 rate guide, Mutual of Omaha Plan F for a non-tobacco man was $320 a month at age 65 and $407 at age 75.
➤ What is the high-deductible Plan F deductible for 2027?
CMS set it at $3,050 for 2027. You pay covered costs up to that amount, then the plan pays like regular Plan F for the rest of the year.
➤ Is Plan C the same as Plan F?
No. Plan C pays the Part B deductible like F but does not pay Part B excess charges. It has the same rule: only people eligible for Medicare before 2020 can buy it.
➤ Do I need health questions to switch from Plan F to Plan G?
Usually, yes, unless your state has a birthday, anniversary or year-round rule, or you have a guaranteed issue right. Keep your Plan F until the Plan G application is approved.
➤ Does Plan F cover prescription drugs?
No. No Medicare Supplement plan sold today covers prescriptions. You need a separate Part D plan, which in 2027 has a deductible of up to $700 and a $2,400 yearly out-of-pocket cap.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll