Medicare Supplement Plans Under 65 for 2027: State Rules, Price Caps and Your Second Chance at 65
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 8, 2026
People under 65 on Medicare can buy a Medicare Supplement plan in 2027 only where state law or an insurer allows it: 38 states require insurers to offer at least one Medigap policy to under-65 beneficiaries with disabilities, but federal law does not. Prices vary from the regular age-65 rate in states with caps, such as Kansas and Virginia, to more than 11 times that rate where no cap applies.
2027 by the Numbers
38
states that require at least one Medigap policy for under-65 enrollees with disabilities (KFF, Oct. 2026)
11.2x
under-65 vs age-65 Plan G price on one Tennessee rate sheet (our math)
200%
Texas cap on most under-65 ESRD/ALS Medigap prices since Sept. 2025
6 months
new Medigap open enrollment when you turn 65
If you qualify for Medicare before 65 because of a disability, end-stage renal disease (ESRD) or ALS, the federal six-month Medigap open enrollment period does not protect you yet. Whether a company must sell you a policy, which plans it must offer and what it can charge all come from your state.
We pulled those rules from the state insurance laws and official guides behind our state pages and lined them up, then added the real under-65 prices we could find on filed rate sheets. If you are close to 65, also read our Medicare Supplement open enrollment 2027 guide, because your rights improve on your 65th birthday.
Check 2027 Under-65 Medicare Supplement Options
What Federal Law Does and Does Not Give You Before 65
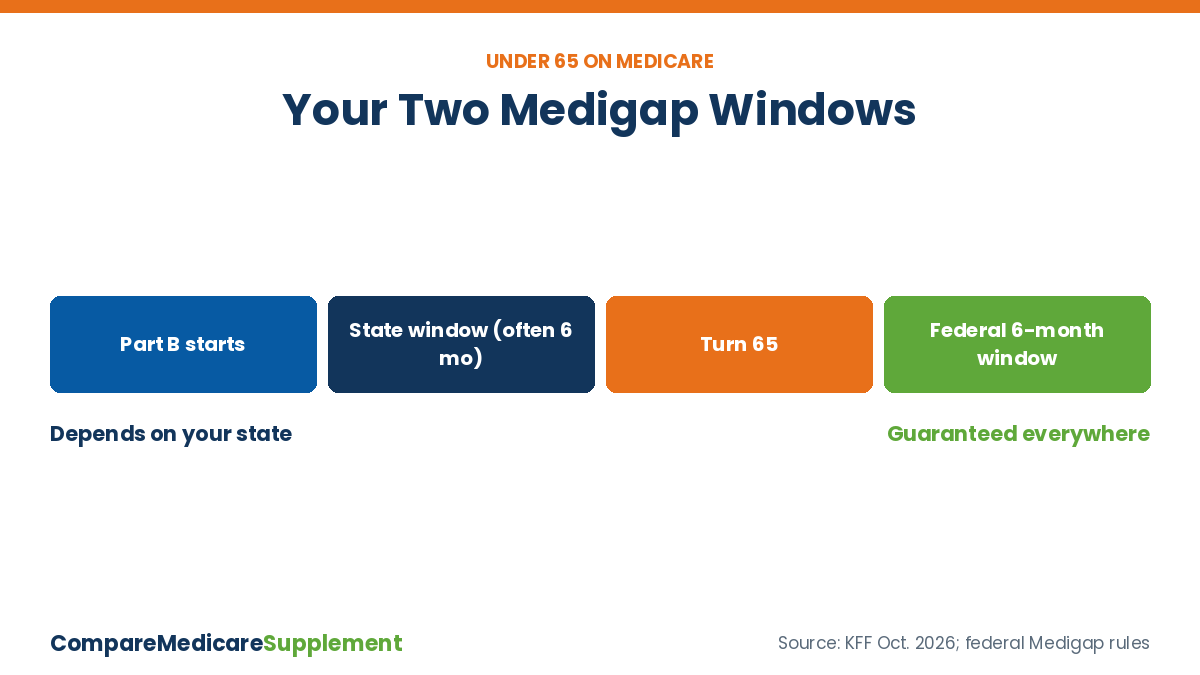
No federal right to buy. Federal law does not require Medigap insurers to sell to people under 65. Without a state rule, a company can decline you or price you on your health.
A federal right at 65. When you turn 65 you get the same six-month Medigap open enrollment period as everyone else, starting the month you are 65 and enrolled in Part B.
State rules fill the gap. KFF’s October 2026 review counts 38 states that require at least one policy for under-65 enrollees with disabilities. 12 states and DC do not.
ESRD is treated differently in many places. KFF found California, Massachusetts, Vermont and Nebraska do not require insurers to sell to people with ESRD under their under-65 rules, and six other states are silent on it.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Our State-by-State Table: Who Must Sell and at What Price
| State | Who must sell, and which plans | Price rule |
|---|---|---|
| New York | Any plan sold in your area, any month of the year | Community rated: same price as every other age |
| Kansas | Every plan the company sells to people 65+ | No more than the age-65 price |
| Virginia | At least one plan, disability or ESRD | Since 2024, no higher than the age-65 price |
| Texas | ESRD or ALS: same plans sold at 65+ (HB 2516) | A, B and D at age-65 rate; others up to 200% |
| Illinois | Every plan type, if you apply within 6 months of Part B | Insurer sets its own under-65 rate |
| Nevada | Any plan sold to new 65+ customers, since Oct. 1, 2025 | Insurer sets its own under-65 rate |
| Tennessee | Same plans sold at 65, within 6 months of Part B | May differ if actuarially sound |
| North Carolina | Plans A, D or G | Often higher than age-65 rates |
| New Jersey | Plan D, or Plan C if eligible before 2020 | Insurer filed rate |
| Nebraska | Plan A only | Insurer filed rate |
Compiled from each state’s insurance law or official Medicare Supplement guide as summarized on our state pages, and KFF, October 2026. Rules change; confirm with your state insurance department.
The pattern is clear: guaranteed access is common, but a price cap is not. In most of the states above, the law makes a company sell you a policy without capping what it charges. Our New York and Kansas pages cover the two strongest rules in detail.
Real Under-65 Prices: Our Math on Filed Rate Sheets
| Example | Under-65 price | Comparison | Our math |
|---|---|---|---|
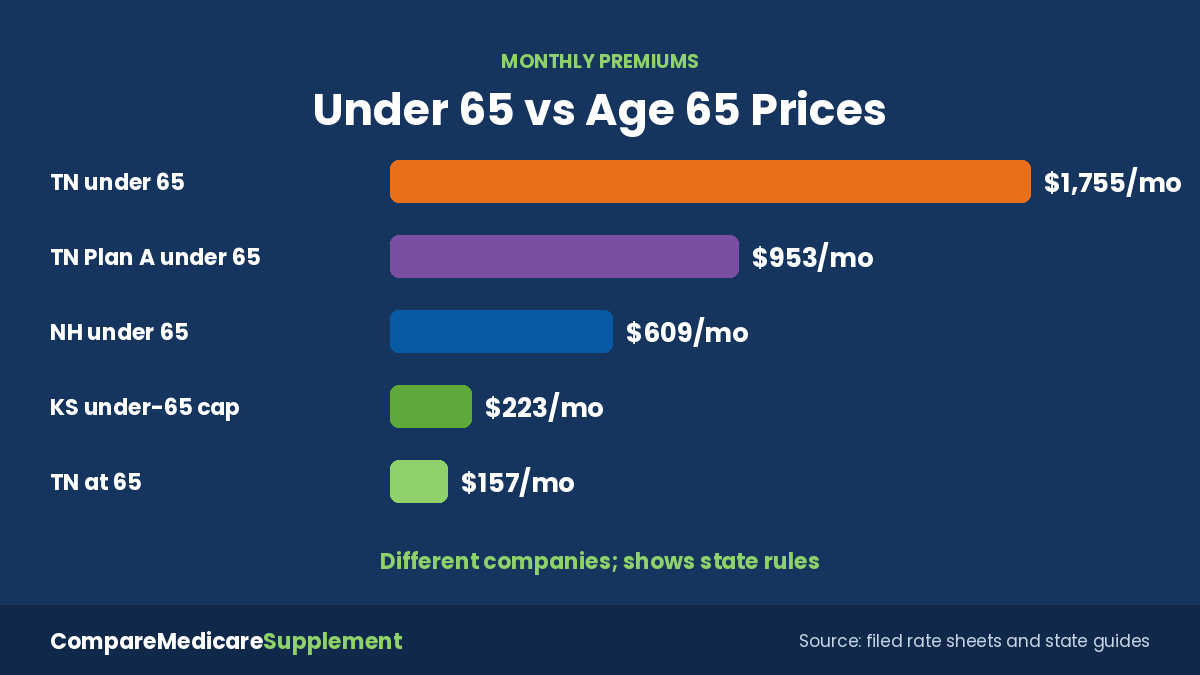
| Tennessee, BlueCross BlueShield BlueElite Plan G, man | $1,755.32 a month | $157.34 at age 65 | 11.2 times higher; $19,175.76 more a year |
| Tennessee, BlueElite Plan A, man | $953.16 a month | $157.34 Plan G at 65 | Even the basic plan is 6 times the age-65 Plan G |
| New Hampshire, Harvard Pilgrim Plan G | $609 a month | – | $7,308 a year |
| Kansas, BCBS of Kansas Plan G, man (standard 2026) | Capped at $222.94 | Age-65 rate | $2,675.28 a year at most |
Sources: BCBST BlueElite rate sheet and NH Insurance Department guide as cited on our Tennessee and New Hampshire pages; Kansas Insurance Department 2026 shopper’s guide and Kansas law. Different companies; shown to compare state rules, not insurers.
What a cap is worth: For the same coverage, the Tennessee under-65 Plan G above costs $18,388.56 a year more than the most a Kansas resident could be charged for the Kansas Plan G shown. State law, not the plan letter, drives that difference.
Under-65 Rates Can Rise Faster Too
Rate increases are often filed separately for under-65 policyholders. Humana’s September 2026 notice for Kentucky shows the gap.
| Humana, Kentucky, effective Sept. 1, 2026 | Under 65 | 65 and older |
|---|---|---|
| Plan G | +30.57% to +30.61% | +29.0% |
| Plan A | +30.55% to +30.60% | +29.0% |
| Plan N | +30.56% to +30.58% | +29.0% |
| High-deductible Plan G | +9.21% to +9.47% | +8.0% |
Source: Humana, Premium Rate Changes September 2026 notice to agents.
Our math: on a $500 under-65 premium, a 30.6% increase adds $153 a month, $1,836 a year. That is one reason many under-65 enrollees treat their first policy as a bridge to age 65 rather than a permanent choice.
Your Second Chance at 65
Buy what your state allows now. Use your under-65 window, usually six months from Part B, if a state rule gives you one.
Mark your 65th birthday. A new six-month Medigap open enrollment starts then. Companies must sell you any plan they offer, at their regular rates, with no health questions.
Re-shop at 65. Compare age-65 prices from several companies. Moving from an under-65 rate to an age-65 rate can cut the premium sharply.
Watch pre-existing waits. If you had continuous coverage, waiting periods are usually reduced or waived; ask the company in writing.
Timing tip: Do not drop your current policy until the new one is approved and in force. A gap in coverage can cost you your guaranteed rights.
Choices When Medigap Is Not Affordable Before 65
Medicaid and Medicare Savings Programs. If your income is limited, your state may pay Part B premiums and cost sharing, which can make Medigap unnecessary.
Medicare Advantage. Plans have a yearly out-of-pocket limit and generally accept under-65 enrollees. Our Medicare Advantage vs Medicare Supplement 2027 page compares the two.
Employer or union coverage. If you or a spouse still have it, it may coordinate with Medicare until you reach 65.
Keep in mind that leaving Medicare Advantage later for Medigap can require health questions outside guaranteed windows. Our guide to switching from Medicare Advantage to Medicare Supplement explains when you can move without them.
Bottom Line
Under 65, your Medicare Supplement options depend on your state: 38 states require at least one policy for people with disabilities, but only a few cap the price at the age-65 rate. If your state allows it, buy what you can now, then use your federal six-month open enrollment at 65 to move to regular age-65 pricing.
See which 2027 plans you can buy under 65 in your ZIP code
Medicare Supplement Plans Under 65 — Frequently Asked Questions
➤ Can I get a Medicare Supplement plan if I am under 65?
Yes, in many states. KFF counts 38 states that require insurers to offer at least one Medigap policy to under-65 enrollees with disabilities. In the others, a company may sell to you but does not have to.
➤ Why are under-65 Medigap premiums so high?
Most states let companies set separate under-65 rates. On one Tennessee rate sheet, Plan G for a man under 65 was about 11 times the age-65 price.
➤ Which states cap Medigap prices under 65?
Among the states we checked, Kansas and Virginia limit the price to the age-65 rate, New York uses community rating, and Texas caps most ESRD and ALS prices at 200% of the age-65 rate.
➤ Do I get another Medigap open enrollment at 65?
Yes. Federal law gives you a new six-month open enrollment period when you turn 65, with no health questions and regular rates.
➤ Can I buy Medigap under 65 with ESRD?
It depends on the state. Texas requires it for ESRD and ALS, while California, Massachusetts, Vermont and Nebraska do not require insurers to sell to people with ESRD.
➤ Which plans can I buy under 65?
Your state decides. Nebraska limits under-65 buyers to Plan A, North Carolina allows A, D or G, and New York allows any plan sold in your area.
➤ When should I apply under 65?
In most states with a rule, within six months of your Part B start date. Missing that window can mean health questions.
➤ Do under-65 Medigap rates go up faster?
They can. Humana’s September 2026 Kentucky notice raised under-65 Plan G rates about 30.6%, against 29.0% for people 65 and older.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll