Switch From Medicare Advantage to Medicare Supplement 2027: Deadlines, Guaranteed Rights and the Plan N Catch
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 7, 2026
To switch from Medicare Advantage to a Medicare Supplement for 2027, apply for the Medigap policy first, then leave your Medicare Advantage plan during Open Enrollment (October 15 to December 7, 2026) or the Medicare Advantage Open Enrollment Period (January 1 to March 31, 2027), and add a stand-alone Part D plan. Unless you have a guaranteed issue right, such as your plan ending or your first-year trial right, the Medigap company can ask health questions and turn you down.
2027 by the Numbers
3.1 million
Medicare Advantage enrollees whose plans end December 31, 2026 (KFF, Oct. 2026)
1.4 million
more moved into a consolidated plan, with no federal Medigap guarantee (KFF)
March 4, 2027
last day to use a guaranteed right if your plan ends Dec. 31, 2026 (our math, 63 days)
$2,400
2027 Part D out-of-pocket cap (CMS)
Leaving Medicare Advantage is easy. Getting a Medicare Supplement after you leave is the hard part, because outside a few protected situations Medigap companies are allowed to medically underwrite you. That makes the order of your steps, and whether you hold a guaranteed issue right, more important than the plan letter you pick.
This page lays out the 2027 switching calendar, the exact federal rights and their deadlines, and two details many guides skip: which plan letters those rights actually cover, and why people moved into a consolidated plan get no guarantee at all. If you are still deciding between the two paths, start with our Medicare Advantage vs Medicare Supplement 2027 cost comparison.
Compare 2027 Medigap Plans Before You Switch
The Two 2027 Windows for Leaving Medicare Advantage
Medicare gives you two regular chances to drop a Medicare Advantage plan and return to Original Medicare. Either one works for the Medicare side. Neither one, by itself, forces a Medigap company to accept you.
| Window | Dates | What you can do | Coverage starts |
|---|---|---|---|
| Open Enrollment | Oct. 15 to Dec. 7, 2026 | Leave Medicare Advantage, join a Part D plan | January 1, 2027 |
| Medicare Advantage Open Enrollment | Jan. 1 to Mar. 31, 2027 | One switch to Original Medicare plus a Part D plan | First of the month after you switch |
| Special Enrollment Period | Varies | Leave after a move, a plan ending or other qualifying event | Depends on the event |
Windows set by Medicare. A Medigap policy is a separate purchase from a private insurer and follows its own rules.
The Medigap open enrollment that guarantees you any plan happens only once, in the six months after you are 65 and enrolled in Part B. Most people leaving Medicare Advantage are past it. Our Medicare Supplement open enrollment 2027 guide explains that window.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Federal Guaranteed Rights: Who Has One and What It Covers
A guaranteed issue right means the company must sell you a policy, cannot add a pre-existing condition wait, and cannot charge more for your health. Federal rules list three situations that matter for Medicare Advantage members.
| Your situation | Plans you can buy | When to apply |
|---|---|---|
| Your plan leaves Medicare, stops serving your area, or you move out of its area | A, B, D, G, K or L (plus C or F if eligible for Medicare before 2020) from any company in your state | From 60 days before to 63 days after your plan coverage ends |
| Trial right: you joined Medicare Advantage when first eligible at 65 and leave within the first year | Any Medigap policy sold in your state | Same 60-day / 63-day window |
| Trial right: you dropped a Medigap policy to try Medicare Advantage for the first time and leave within a year | Your old policy if the same company still sells it; otherwise A, B, D, G, K or L | Same 60-day / 63-day window |
Source: Medicare guaranteed issue rights as published by the Indiana State Health Insurance Assistance Program from Medicare’s Medigap guide. Your state may add more rights.
The Plan N catch: Plan N is not on the federal list for a plan termination or a move. Unless your state adds it or you are using the age-65 trial right, a company can underwrite you for Plan N even while it must accept you for Plan G.
Our Math: Your 2027 Deadline if Your Plan Is Ending
KFF counted 3.1 million Medicare Advantage enrollees, including about 300,000 in special needs plans, whose plans end on December 31, 2026. Four parent companies account for about half of the general-enrollment losses: Humana (530,000), UnitedHealth Group (367,000), CVS Health (254,000) and Aware Integrated in Minnesota (249,000). If you are one of them, here is the window, counted from that end date.
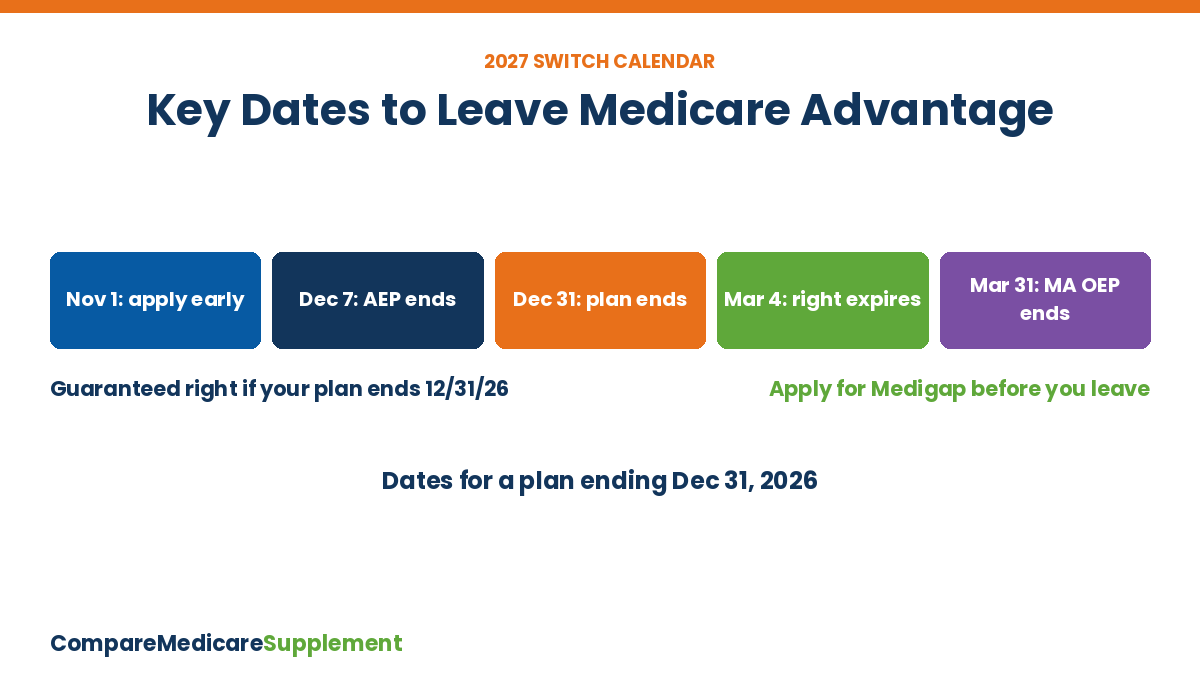
November 1, 2026: earliest application. Federal rules let you apply as early as 60 days before your plan coverage ends, so you can line up the policy before you lose anything.
December 7, 2026: Open Enrollment ends. Choose a Part D plan by this date so drug coverage starts January 1 alongside the Medigap policy.
December 31, 2026: Medicare Advantage coverage ends. Your Medigap policy can start the next day if your application is approved.
March 4, 2027: last day. 63 days after December 31. Apply after this and the guarantee is gone, so the company may ask health questions.
Keep the termination notice your plan mailed you. Medigap companies can ask for proof that your coverage ended, and the notice is the simplest proof.
Consolidated Plans and Other Cases With No Guarantee
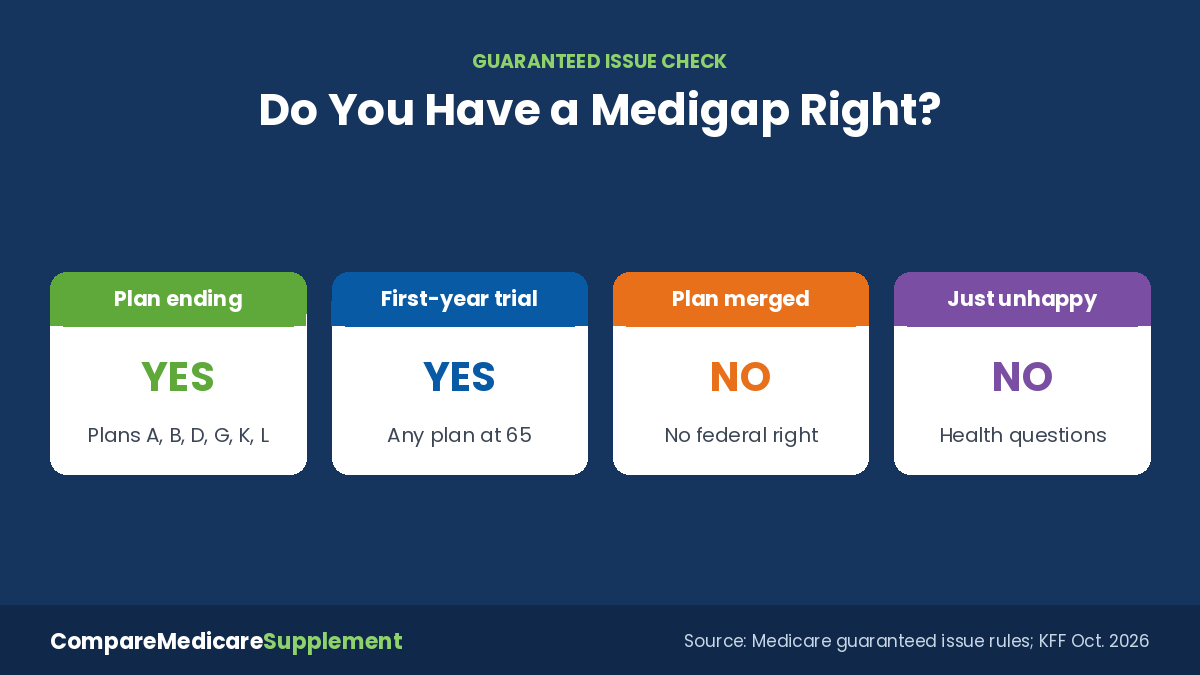
Not every plan change creates a right. KFF found about 1.4 million more Medicare Advantage enrollees are being moved into another plan from the same insurer for 2027. Because those enrollees are moved automatically and their plan is not counted as terminated, they do not have federal guaranteed issue rights if they switch to Original Medicare.
Crosswalked to a new plan. Your insurer combined your plan with another one. No federal Medigap guarantee, even if the network or benefits changed.
Unhappy with costs or networks. Leaving because of higher copays, prior authorization or a doctor leaving the network does not create a federal right on its own.
Past your first year. The trial right ends 12 months after you first joined Medicare Advantage. After that, ordinary underwriting rules apply.
In these cases the company can review your health history. If you have conditions that may lead to a denial, read our guide to changing Medicare Supplement plans with pre-existing conditions before you leave your current plan.
What Underwriting Can Cost: A Real Rate Sheet Example
Underwriting is not only about yes or no. Some companies also price differently depending on whether you buy with a guaranteed right. Blue Cross Blue Shield of Arizona publishes a discounted BlueValue rate for people with guaranteed issue rights and a higher standard rate for people who apply without one.
| AZ Blue Senior Saver Plan G, man 70, Region 1 | Monthly | Yearly |
|---|---|---|
| BlueValue rate (guaranteed issue) | $257.13 | $3,085.56 |
| Standard rate (no guaranteed right) | $560.52 | $6,726.24 |
| Difference | $303.39 | $3,640.68 |
Source: Blue Cross Blue Shield of Arizona 2026 Medicare Supplement rate sheet, non-tobacco, Maricopa and Pinal counties. Yearly figures and difference are our math. Other companies and states differ.
At a company priced this way, using a guaranteed right instead of applying a few weeks late would be worth about $3,640 a year at age 70. See more Arizona prices on our Arizona Medicare Supplement plans 2027 page.
The Safe Order of Steps for a 2027 Switch
Check for a guaranteed right. Read any plan notice for words like terminating or leaving your service area. Note your first Medicare Advantage start date if you might still have a trial right.
Apply for the Medigap policy first. Get approval in writing before you disenroll. If you are denied, you can stay in Medicare Advantage instead of ending up with no supplement.
Pick a Part D plan. Medigap plans sold today do not cover drugs. For 2027, the Part D deductible can be up to $700 and the out-of-pocket cap is $2,400. KFF counts an average of nine stand-alone drug plans per beneficiary for 2027.
Leave Medicare Advantage. Enrolling in the Part D plan during an enrollment window generally ends your Medicare Advantage plan automatically; you can also contact the plan or Medicare.
Line up start dates. Ask for the Medigap policy and the drug plan to begin the same day your Medicare Advantage coverage ends.
New York and Massachusetts allow continuous Medigap enrollment, according to the NAIC state chart dated May 11, 2026, which makes switching there far simpler. Most states have no such rule, so the order above matters most.
Bottom Line
Switching from Medicare Advantage to a Medicare Supplement for 2027 is a two-part move: leaving the plan is guaranteed, getting the supplement often is not. If your plan is ending December 31, 2026, your federal right runs until March 4, 2027 and covers Plan G but not Plan N. Without a right, apply and get approved before you leave.
See Medicare Supplement prices in your ZIP code
Switching From Medicare Advantage to Medicare Supplement — Frequently Asked Questions
➤ Can I switch from Medicare Advantage to a Medicare Supplement at any time?
You can leave Medicare Advantage only during set windows, mainly October 15 to December 7, 2026 and January 1 to March 31, 2027. A Medigap company can sell you a policy any time, but it can ask health questions unless you have a guaranteed right.
➤ Do I have a guaranteed right if my Medicare Advantage plan is ending in 2027?
Yes, if your plan is leaving Medicare or your area and you return to Original Medicare. You can apply from 60 days before to 63 days after the plan ends.
➤ Can I get Plan N with a guaranteed right?
Not under the federal plan-termination right, which lists Plans A, B, D, G, K and L, plus C and F for people eligible before 2020. The age-65 trial right lets you buy any plan.
➤ What is the Medicare Advantage trial right?
If you joined Medicare Advantage when first eligible at 65, or dropped a Medigap policy to try it for the first time, you can return within 12 months with guaranteed Medigap rights.
➤ My plan was merged into another plan. Do I get a guaranteed right?
Usually no. KFF notes enrollees moved into a consolidated plan from the same insurer do not have federal guaranteed issue rights if they switch.
➤ Should I cancel Medicare Advantage before applying for Medigap?
No. Apply first and wait for approval, then leave. That way a denial does not leave you without supplemental coverage.
➤ Do I need a separate drug plan after switching?
Yes. Medigap plans sold today do not include drug coverage, so join a stand-alone Part D plan. The 2027 out-of-pocket cap is $2,400.
➤ Is it easier to switch in some states?
Yes. The NAIC chart lists New York and Massachusetts with continuous Medigap enrollment. Other states may add their own rights, so check with your state insurance department.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll