Medicare Supplement Open Enrollment 2027: Your 6-Month Window, Dates and Rights
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 1, 2026
Medicare Supplement open enrollment is a one-time, 6-month window that starts the first month you have Medicare Part B and are 65 or older; during it, any company selling Medigap in your state must sell you any plan it offers for the same price it charges people in good health. It is not the fall Annual Enrollment Period, and once the six months pass, most states let insurers use medical underwriting.
2027 by the Numbers
6 months
length of your one-time federal Medigap open enrollment window (Medicare.gov)
$1,626.84
yearly gap between the cheapest and priciest Plan G a 65-year-old man could choose in NJ, September 2026 chart (our math)
16
states with a yearly birthday-style switch window in 2027, counting New Mexico’s new rule (NAIC chart, state laws)
$209.40
2027 Part B monthly premium, which you must be paying to use the window (CMS)
Many people hear “open enrollment” every fall and assume it applies to Medicare Supplement insurance. It does not. Medigap has its own personal enrollment window, tied to the date your Part B coverage begins, and it only happens once.
This guide shows how to find your exact 2027 dates, what the law protects during those six months, and where state rules give extra chances later. If you are still choosing a plan letter, start with our 2027 Medicare Supplement plans overview.
Check 2027 Medigap Prices Before Your Window Closes
How the 6-Month Window Is Set
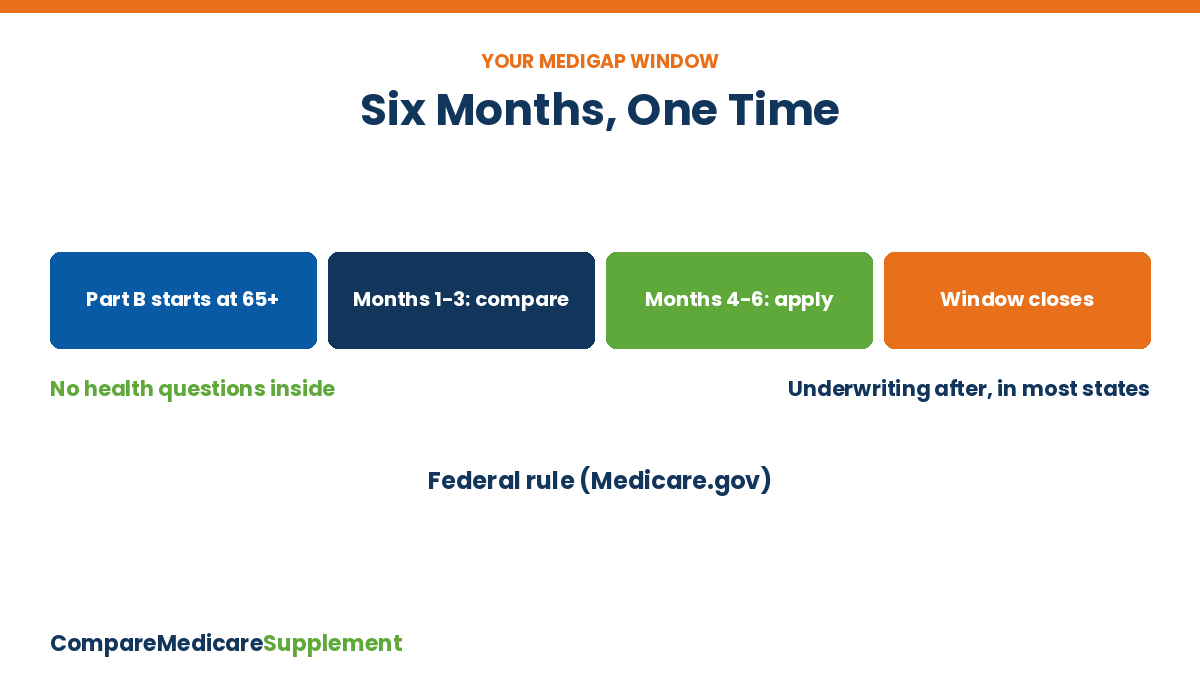
Your Medigap open enrollment period begins on the first day of the first month in which you are both 65 or older and enrolled in Part B. It runs for six full months and then closes for good. Nobody picks the date for you, and you do not have to apply for it; it simply starts when Part B starts.
It is personal. Two neighbors born a month apart will have windows a month apart. There is no national start date.
It follows Part B, not Part A. If you delay Part B because you are still covered by a large employer plan, your window waits too, and starts when Part B finally begins.
It does not repeat. Under federal law you get one window. Switching plans later depends on health answers or a state rule.
Birthday on the 1st? Social Security starts Medicare the month before your birthday month in that case, so your window starts a month earlier too.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Your 2027 Dates at a Glance
We worked out the window for the most common Part B start dates around 2027. Find the month your Part B card shows and read across.
| Part B starts | Window opens | Window closes |
|---|---|---|
| December 1, 2026 | December 1, 2026 | May 31, 2027 |
| January 1, 2027 | January 1, 2027 | June 30, 2027 |
| March 1, 2027 | March 1, 2027 | August 31, 2027 |
| June 1, 2027 | June 1, 2027 | November 30, 2027 |
| October 1, 2027 | October 1, 2027 | March 31, 2028 |
Our calculation from the federal rule: six months beginning the first month you have Part B at 65 or older.
Date to circle: Many companies accept applications up to six months before your Part B start date so the policy begins the same day as Part B. Waiting until the last week of the window leaves no room for paperwork delays.
What Insurers Cannot Do During Open Enrollment
Medicare.gov lists the protections. During your window a company cannot refuse to sell you any Medigap policy it offers, cannot charge you more because of health conditions, and cannot make you wait for coverage because of your health, with one exception.
| During your window | After it closes (most states) |
|---|---|
| Any plan letter the company sells must be offered | The company can decline your application |
| No higher price for health conditions | Health can push you into a higher rate class |
| Pre-existing condition wait only if you lacked 6 months of prior creditable coverage | Health questions decide whether you are accepted at all |
| You can pick any company in your state | Your choices shrink to companies that accept your answers |
Federal Medigap open enrollment protections (Medicare.gov). A waiting period of up to six months can apply to pre-existing conditions if you had no creditable coverage before.
The window protects your choice of company as much as your acceptance. That matters because prices for the same plan letter vary widely, which the next section puts in dollars.
Why the Window Is Worth Real Money
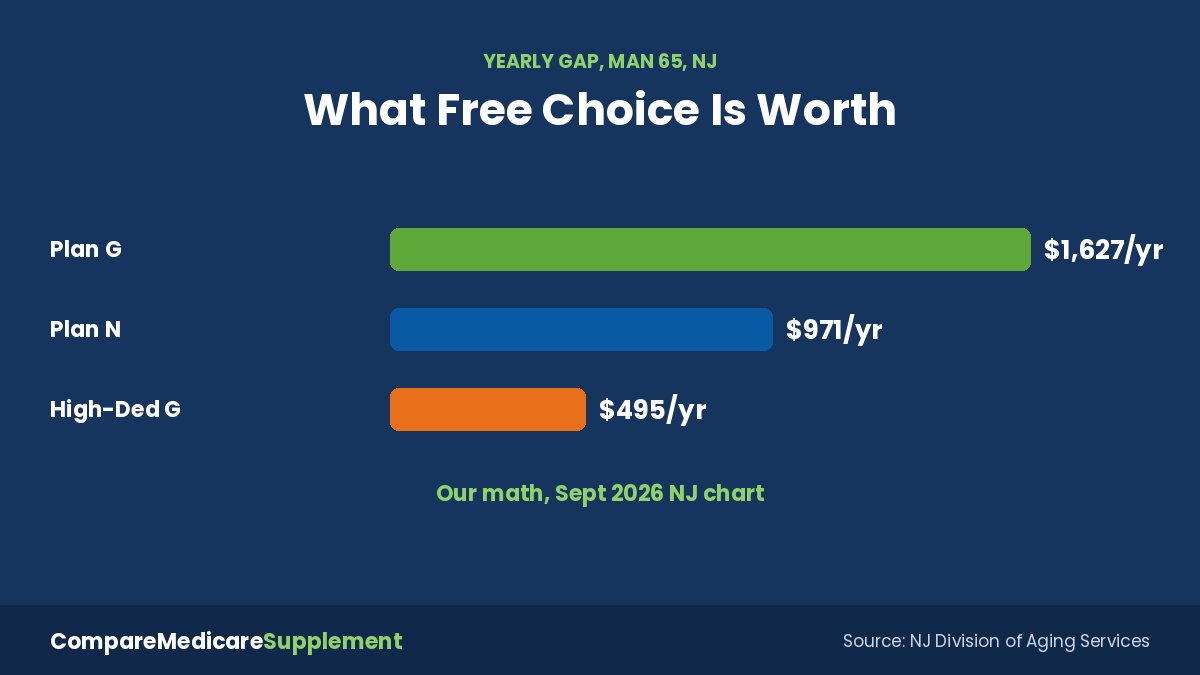
New Jersey’s Division of Aging Services publishes every company’s monthly rate for a 65-year-old. On the September 2026 male chart, Plan G ran from $164.31 to $299.88 a month. Because every company must accept you during open enrollment, all of those prices are open to you. We did the yearly math.
| Plan, man 65, NJ Sept 2026 | Lowest monthly | Highest monthly | Yearly gap (our math) |
|---|---|---|---|
| Plan G | $164.31 | $299.88 | $1,626.84 |
| Plan N | $119.90 | $200.84 | $971.28 |
| High-Deductible G | $50.83 | $92.08 | $495.00 |
Source: NJ Division of Aging Services, Male Preferred Rates at Age 65, September 2026 (revised 8/26/2026). Gap = (highest minus lowest) x 12.
Outside the window, a buyer with a recent heart procedure or a new diabetes diagnosis might be accepted only by some companies, or by none. Using the window means the cheapest company is a real option instead of a theory. Our 2027 Medicare Supplement cost guide shows full-year totals, including Part B.
Other Chances to Buy or Switch After 2027 Begins
Missing the window does not always mean underwriting. Federal guaranteed issue rights cover specific events, and a growing number of states add yearly switching windows.
Trial right. If you joined a Medicare Advantage plan when first eligible at 65 and leave within 12 months, you can buy a Medigap policy without health questions.
Losing certain coverage. If your Advantage plan leaves your area or your employer retiree plan ends, a guaranteed issue right usually lasts 63 days after the coverage ends.
Birthday-style rules. About 16 states in 2027, including California, Kentucky, Oklahoma and, from January 1, 2027, New Mexico, give a yearly window to move to equal or lesser benefits.
Year-round states. New York and Connecticut require insurers to accept applicants all year; Missouri uses a policy-anniversary window instead.
Keep in mind: The fall Annual Enrollment Period, October 15 to December 7, changes Advantage and Part D plans only. It gives no right to buy or switch a Medigap policy.
A Simple Plan for Using Your Window
Confirm your Part B start date. It is printed on your red, white and blue Medicare card. That date sets your whole window.
Pick a plan letter first. Most new enrollees choose between Plan G and Plan N; our Plan G vs Plan N cost test shows which saves money for your doctor habits.
Price several companies for that letter. Benefits are standardized, so only price, rate history and discounts differ.
Apply early in the window. Apply in the months before Part B starts if you can, so coverage lines up with no gap.
Keep proof of prior coverage. If you are leaving employer coverage, keep the letter showing your end date in case an insurer asks.
If you are still deciding between plan letters, our side-by-side Medicare Supplement comparison lays out what each letter pays.
Bottom Line
Your Medigap open enrollment period is six months long, starts with Part B at 65 or older, and is the one time federal law guarantees you any company’s plan at the same price healthy buyers pay. Mark your dates now and compare companies inside the window, because the price spread for the same plan can top $1,600 a year.
See which companies sell Medigap in your ZIP code
Medicare Supplement Open Enrollment 2027 — Frequently Asked Questions
➤ When does Medicare Supplement open enrollment start in 2027?
It starts the first month you have Part B and are 65 or older. If your Part B begins January 1, 2027, your window runs through June 30, 2027.
➤ Is Medigap open enrollment the same as the October 15 to December 7 period?
No. The fall period is for Medicare Advantage and Part D changes. Medigap open enrollment is a separate 6-month window that is personal to you.
➤ Can I be turned down during my open enrollment window?
No. During the window a company must sell you any Medigap plan it offers and cannot charge more because of your health.
➤ What if I delayed Part B because I was still working?
Your window waits. It starts when your Part B starts, as long as you are 65 or older, so you keep the protection after leaving employer coverage.
➤ Can a company make me wait for coverage of a pre-existing condition?
Only if you did not have at least six months of creditable coverage before applying. Even then, the wait cannot be longer than six months.
➤ Do I get another Medigap open enrollment later?
Not under federal law. Some states add birthday or anniversary windows, and certain life events create guaranteed issue rights.
➤ Can I use open enrollment if I am under 65 and on disability?
The federal window starts at 65, so you get a fresh one then. Some states also require insurers to sell to people under 65, often at higher prices.
➤ Should I apply before my Part B start date?
Usually yes. Applying in the months before Part B begins lets the Medigap policy start the same day, so there is no gap in coverage.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll