Medicare Advantage vs Medicare Supplement 2027: Three Cost Scenarios and the Break-Even Point
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 3, 2026
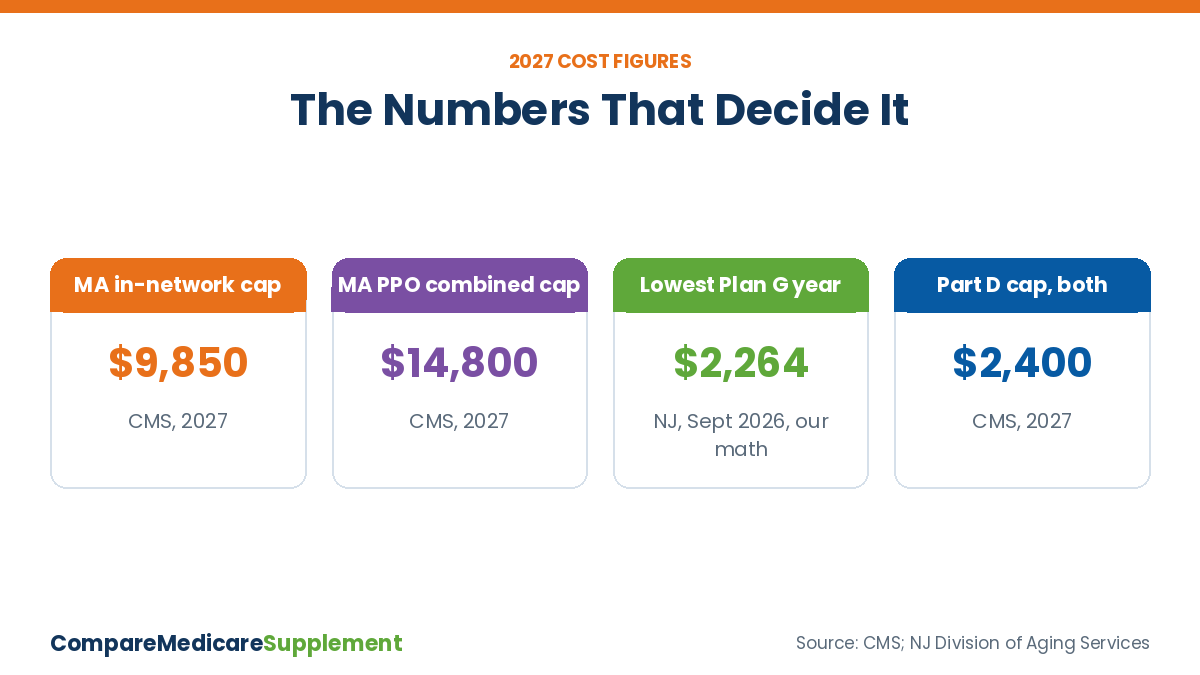
For 2027, Medicare Advantage usually wins on cost in a light-use year, and a Medicare Supplement wins once your Medicare Advantage copays pass roughly $1,800 to $2,300 a year. In a worst-case year, a $0-premium Medicare Advantage plan can cost up to the $9,850 in-network cap CMS set for 2027, while the lowest Plan G on New Jersey’s September 2026 chart totals about $2,264.
2027 by the Numbers
$9,850
2027 in-network out-of-pocket cap for Medicare Advantage (CMS)
$2,263.72
yearly Plan G premium plus projected Part B deductible, lowest NJ rate, man 65, September 2026 (our math)
$2,400
2027 Part D out-of-pocket cap, the same on both paths (CMS)
7.7%
share of Medicare Advantage prior authorization requests denied in 2024 (KFF)
Most comparisons of these two paths list features and stop. This one puts dollar figures on three kinds of 2027 years, using CMS’s new Medicare Advantage limits and real Medicare Supplement premiums filed with one state. It also covers the rule that matters most after the numbers: leaving Medicare Advantage later is not always a two-way street.
The premiums below come from New Jersey’s September 2026 rate chart. Your state’s prices will differ, so treat the dollar amounts as a worked example. For the full New Jersey chart see our New Jersey Medicare Supplement plans 2027 page.
See 2027 Plan G, N and HD-G Prices
The 2027 Numbers Behind Each Path
Both paths start with Part A and Part B, and both pay the Part B premium, $209.40 a month for 2027. What differs is who pays the rest of the bill and how much of it lands on you.
| 2027 figure | Medicare Advantage | Medicare Supplement path |
|---|---|---|
| Monthly plan premium | Average $12.00 across all plans (CMS) | $164.31 to $299.88 for Plan G, man 65, NJ, September 2026 |
| Yearly cap on covered medical costs | $9,850 in-network; $14,800 in and out of network for PPOs (CMS) | No cap needed on Plan G: you pay the projected $292 Part B deductible |
| Prescription drugs | Usually built in; $2,400 yearly cap | Separate Part D plan; same $2,400 cap |
| Plans to pick from | 5,532 nationwide (CMS) | Ten standard plan letters in most states |
CMS 2027 landscape release (Sept. 28, 2026) and CY2027 Part C limits. Part B figures are Trustees projections; CMS announces final 2027 amounts in November.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Our Math: A Light Year, a Busy Year and a Worst-Case Year
We priced three sample years. The light year has $1,000 of Medicare-approved doctor and lab care. The busy year has a hospital stay plus $8,000 of outpatient care. The worst case is a serious illness that pushes a Medicare Advantage member to the plan’s yearly cap. Medigap figures use the lowest New Jersey premiums for each plan.
| Yearly cost, 2027 | Light year | Busy year | Worst case |
|---|---|---|---|
| Plan G ($164.31/mo) | $2,263.72 | $2,263.72 | $2,263.72 |
| Plan N ($119.90/mo) | $1,810.80 | $1,930.80 | $2,130.80 |
| High Deductible G ($50.83/mo) | $1,043.56 | $3,659.96 | $3,659.96 |
| $0-premium Medicare Advantage | Your copays | Your copays | Up to $9,850 |
Our math. Premiums: NJ Division of Aging Services chart, September 2026, man 65. Uses the projected 2027 Part B deductible ($292), Part A deductible ($1,788) and HD-G deductible ($3,050). Plan N assumes 4, 10 and 20 copays of $20. Part B premium, drugs and excess charges left out.
How the math works: Plan G leaves only the Part B deductible, so its total does not move. High Deductible G caps what you pay at $3,050 plus premium. A Medicare Advantage plan sets its own copays, so its light and busy year totals depend on the plan you pick.
Where the Break-Even Point Falls
The useful question is how much a Medicare Advantage plan would have to charge you in copays before a Medicare Supplement becomes the cheaper choice. The answer is simply each Medigap plan’s yearly total from the table above.
Plan N. Cheaper than a $0-premium Medicare Advantage plan once your copays pass about $1,811 to $2,131 a year.
Plan G. Cheaper once copays pass $2,263.72, at any level of use.
High Deductible G. Cheaper once copays pass $1,043.56 in a light year; in a heavy year the line moves to $3,659.96.
At the 2027 cap. Plan G costs $7,586.28 less than a Medicare Advantage member who reaches $9,850.
In short, a Medicare Advantage plan with low copays can come out ahead for several healthy years. One year near the cap can wipe out years of premium savings. To see how the high-deductible version works, read our High Deductible Plan G 2027 guide.
The One-Way Door: Getting Back Into Medigap After Medicare Advantage
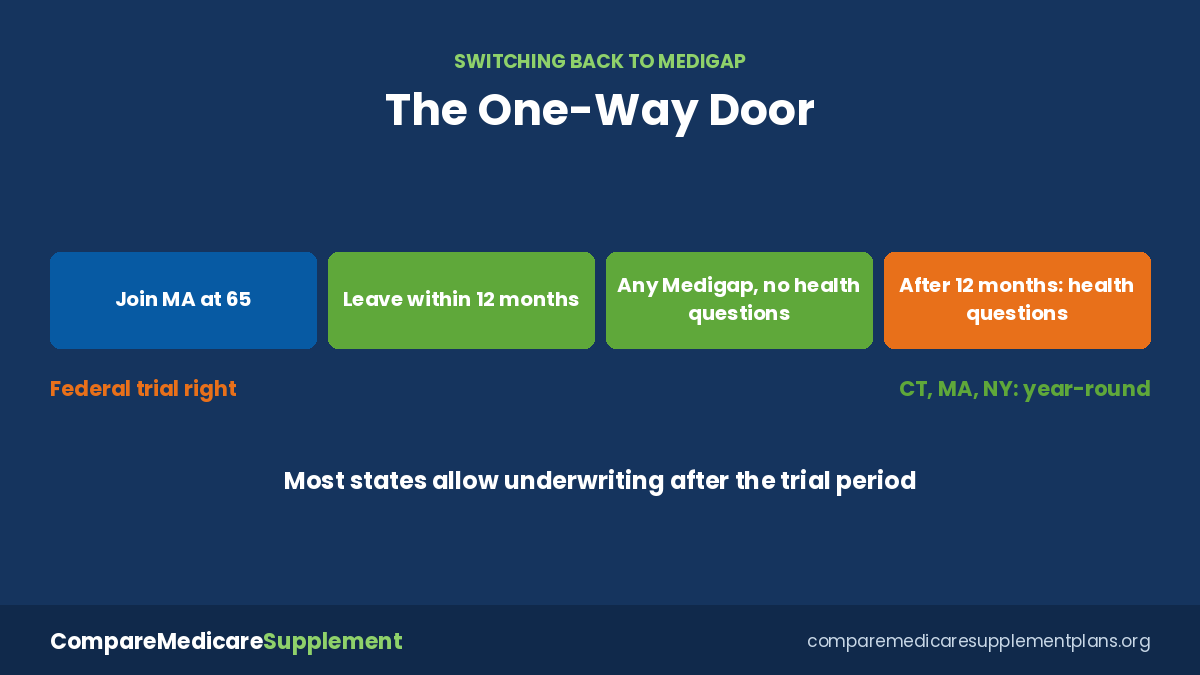
You can drop Medicare Advantage for Original Medicare each fall or from January 1 to March 31. Buying a Medicare Supplement at that point is the hard part. Outside your first six-month Medigap window and a few protected situations, most states let insurers ask health questions and decline you.
Federal trial right. Joined Medicare Advantage when first eligible at 65? Leave within 12 months and any Medigap plan sold in your state must accept you.
Dropped a Medigap policy? If it was your first Medicare Advantage plan, leaving within 12 months generally restores your right to that same policy.
Year-round states. Connecticut, Massachusetts and New York require insurers to sell Medigap to people 65 and older at any time, per KFF.
Maine. Insurers must offer at least Plan A during a one-month window each year, per KFF.
Connecticut, Maine and New York may still apply a pre-existing condition waiting period of up to six months. Your own guaranteed window is explained on our Medicare Supplement open enrollment 2027 page.
Prior Authorization and Networks: Costs That Are Not in Dollars
Two features of Medicare Advantage do not show up in a premium comparison. Plans use networks, and plans can require approval before covering a service. Original Medicare uses prior approval for only a narrow set of services, and a Medicare Supplement follows Medicare’s decision.
| Medicare Advantage prior authorization, 2024 | KFF figure |
|---|---|
| Requests insurers decided | 52.8 million |
| Requests per enrollee | 1.7 |
| Requests fully or partly denied | 7.7% (4.1 million) |
| Denials that were appealed | 11.5% |
| Appeals fully or partly overturned | 80.7% |
Source: KFF analysis of Medicare Advantage insurer data for 2024.
Worth knowing: Most denials are never appealed, yet most appeals succeed. Anyone on Medicare Advantage can ask the plan for a written reason and file an appeal.
Which Path Tends to Fit Which Person
Medicare Advantage may fit a person with few health needs, local doctors in the plan’s network and the savings to cover a year at the $9,850 cap.
A Medicare Supplement may fit a person who travels, sees specialists, wants any doctor that takes Medicare, or wants a fixed yearly cost.
Decide during your first Medigap window because it is the one time every insurer must accept you in most states.
Compare plan letters, not just paths since Plan N and High Deductible G change the break-even point. See our Plan G vs Plan N comparison.
Bottom Line
For 2027, Medicare Advantage is the lower-cost path in a healthy year, and a Medicare Supplement is the lower-cost path in a year with real medical bills. Our math puts the break-even near $1,800 to $2,300 in yearly copays, with the $9,850 cap as the downside. Because switching back to Medigap can require health questions, the first choice tends to stick.
Check Medicare Supplement prices for 2027 in your ZIP code
Medicare Advantage vs Medicare Supplement 2027 — Frequently Asked Questions
➤ Which costs less in 2027, Medicare Advantage or a Medicare Supplement?
It depends on how much care you use. A $0-premium Medicare Advantage plan costs less if your copays stay low, while Plan G’s yearly total stays near $2,264 at the lowest New Jersey rate no matter how sick you get.
➤ How does the 2027 Medicare Advantage cap compare with Plan G?
CMS set the 2027 in-network cap at $9,850. The lowest New Jersey Plan G premium plus the projected $292 deductible comes to $2,263.72 for the year.
➤ Does the $2,400 drug cap apply on both paths?
Yes. The 2027 Part D out-of-pocket cap of $2,400 applies to drug coverage inside a Medicare Advantage plan and to a standalone Part D plan used with Medigap.
➤ What copay total makes a Medicare Supplement the better buy?
In our New Jersey example, Plan N wins once Medicare Advantage copays pass about $1,811 to $2,131 a year, and Plan G wins above $2,263.72.
➤ Which states let people buy Medigap at any time after leaving Medicare Advantage?
Connecticut, Massachusetts and New York sell Medigap year-round to people 65 and older. Maine has a yearly one-month window for at least Plan A.
➤ Is High Deductible Plan G a middle ground?
It can be. Its low premium beat the other Medigap plans in our light year, and its $3,050 deductible still caps costs far below the Medicare Advantage limit.
➤ Do Medicare Supplement plans use prior authorization?
No. A Medicare Supplement pays after Original Medicare approves a claim, and Original Medicare requires prior approval for only a limited set of services.
➤ When can I change paths for 2027?
Fall open enrollment runs October 15 to December 7, 2026. Medicare Advantage members can also switch from January 1 to March 31, 2027, though Medigap may then ask health questions.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll