Minnesota Medicare Supplement Plans 2027: Basic vs Extended Basic, Real Premiums and the New Enrollment Windows
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 18, 2026
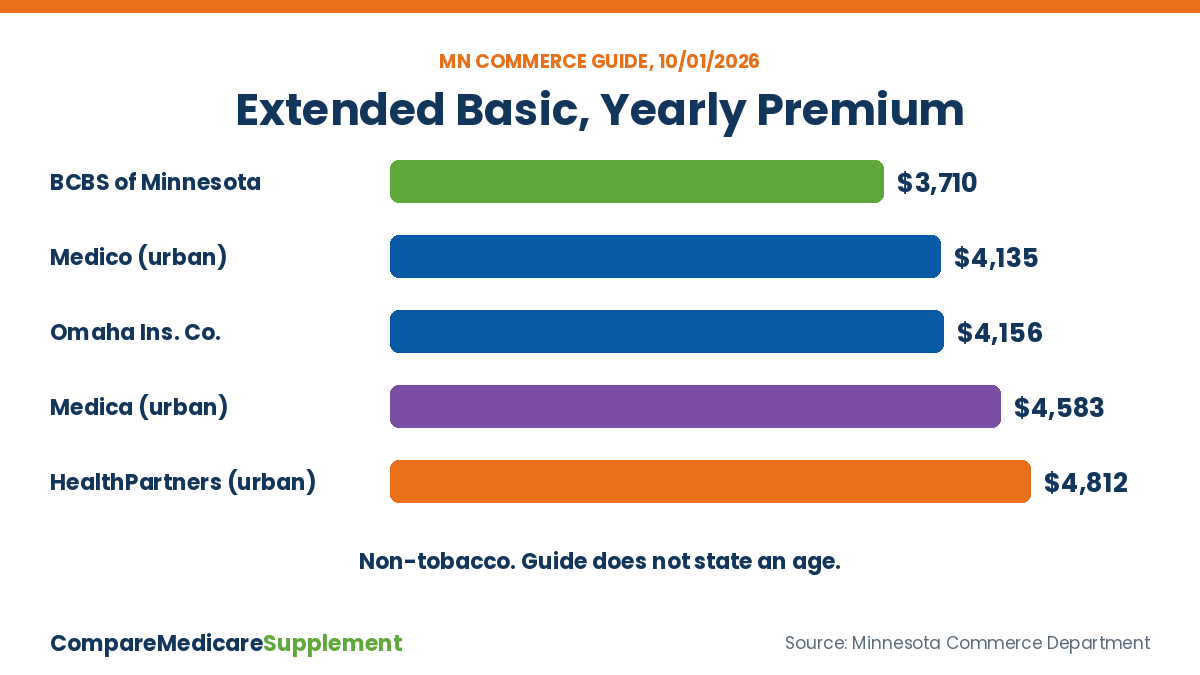
Minnesota Medicare Supplement plans for 2027 are sold as the state’s own Basic and Extended Basic plans plus optional riders, not as Plan G or Plan N, because Minnesota has a federal waiver to standardize Medigap its own way. On the Commerce Department’s October 2026 premium guide, Extended Basic runs from about $3,710 to $4,812 a year (non-tobacco) at the companies we compared, and a new law opens yearly guaranteed issue windows for first-time buyers ages 65 to 70, with a premium surcharge.
2027 by the Numbers
$3,710
lowest Extended Basic annual premium we found, BlueCross BlueShield of Minnesota, non-tobacco (MN Commerce, 10/01/2026)
Aug 1, 2026
start of Minnesota’s new Medigap guaranteed issue windows for ages 65-70 (Bulletin 2026-3)
15% / 20%
surcharge on policies issued through those windows in 2026 / 2027 (Minn. Stat. 62A.31)
$302-$761
yearly savings from Basic plus a Part A deductible rider vs Extended Basic at five carriers (our math)
Shoppers moving to Minnesota are often surprised that no one quotes them Plan G. Minnesota is one of three states, with Massachusetts and Wisconsin, that standardizes Medicare Supplement coverage under its own law. Its menu is built around a Basic plan, an Extended Basic plan and riders you can add one by one.
This page prices those choices using the state Commerce Department’s annual premium guide, shows when adding riders beats buying Extended Basic, and explains the guaranteed issue windows that began on August 1, 2026. For how standard plan letters compare in other states, see our 2027 Medicare Supplement comparison chart.
Compare 2027 Minnesota Medigap Premiums
Minnesota's Two Core Plans and Their Riders
Minnesota Statutes 62A.315 and 62A.316 set what each plan must pay. Every company selling the Basic plan must also offer four riders, so you can build coverage close to Extended Basic piece by piece.
| Benefit | Basic plan | Extended Basic plan |
|---|---|---|
| Part A hospital coinsurance and extra hospital days | Yes | Yes |
| Part A deductible ($1,776 in 2027) | Optional rider | Yes |
| Skilled nursing facility daily copay | Yes | Yes |
| Part B coinsurance | Yes (after Part B deductible) | Yes |
| Part B deductible | Optional rider, not for newly eligible | Only if eligible before 2020 |
| Part B excess charges | Optional rider | Yes, 100% |
| Preventive care not covered by Medicare | Optional rider, up to $120 a year | Yes, up to $120 a year |
| Foreign travel emergencies | 80% | 80% |
| Non-Medicare immunizations and routine cancer screening | 100% | 100% |
Source: Minnesota Statutes 62A.315 and 62A.316. Both plans also cover home health and hospice cost sharing and the first three pints of blood. 2027 Part A deductible from CMS.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
State-Published Premiums at Five Carriers
The Minnesota Commerce Department’s Annual Premium Guide (updated 10/01/2026) lists one yearly premium per company, split by tobacco use and, for some companies, rural or urban area. The guide does not state an age, and it notes that rates can change during the year.
| Company, non-tobacco | Basic (yearly) | Part A deductible rider | Extended Basic (yearly) | Extended Basic per month (our math) |
|---|---|---|---|---|
| BlueCross BlueShield of Minnesota | $2,999 | $409 | $3,710 | $309.17 |
| Medico Insurance Company (urban) | $3,593 | $406 | $4,135 | $344.58 |
| Omaha Insurance Company (Mutual of Omaha) | $3,426 | $480 | $4,156 | $346.33 |
| Medica Health Plans (urban) | $3,285 | $537 | $4,583 | $381.92 |
| HealthPartners (urban) | $3,831 | $597 | $4,812 | $401.00 |
Source: MN Commerce Department, Annual Premium Guide: Medicare Supplement, updated 10/01/2026. Rural rates at Medico, Medica and HealthPartners are lower. Tobacco users pay more.
Carrier details for several of these companies are on our Medico, Mutual of Omaha and Blue Cross 2027 pages.
Our Math: Basic Plus a Rider vs Extended Basic
For people new to Medicare, the biggest practical difference between the two plans is the Part A deductible. Basic plus the Part A deductible rider covers it too, so we added the two and compared the total with Extended Basic at the same company.
| Company (non-tobacco) | Basic + Part A rider | Extended Basic | Yearly savings with Basic + rider |
|---|---|---|---|
| BlueCross BlueShield of Minnesota | $3,408 | $3,710 | $302 |
| Medico (urban) | $3,999 | $4,135 | $136 |
| Omaha Insurance Co. (Mutual of Omaha) | $3,906 | $4,156 | $250 |
| Medica (urban) | $3,822 | $4,583 | $761 |
| HealthPartners (urban) | $4,428 | $4,812 | $384 |
Our calculation from the 10/01/2026 guide. Extended Basic still adds excess-charge coverage, preventive care up to $120 and broader coverage of some non-Medicare costs.
Minnesota detail: Minnesota is one of eight states that do not allow Part B excess charges for care received in the state, so the excess-charge coverage built into Extended Basic mainly matters for care you get outside Minnesota.
The New Guaranteed Issue Windows and Their Surcharge
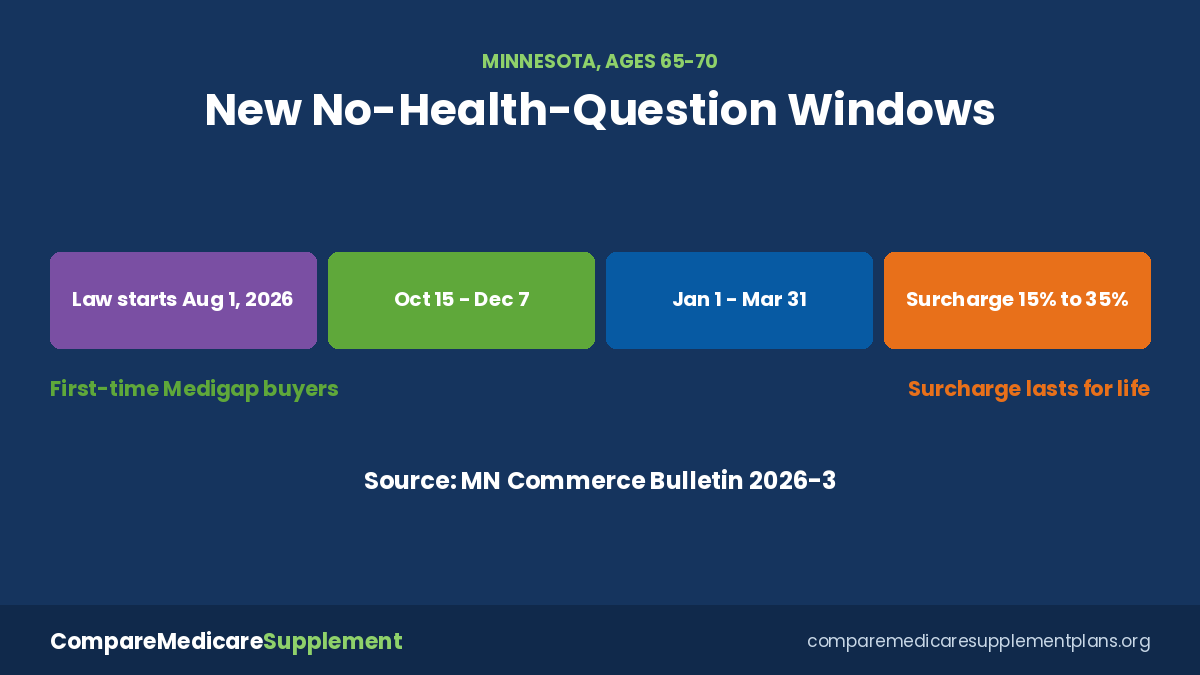
Minnesota’s Commerce Department confirmed in Administrative Bulletin 2026-3 (August 31, 2026) that changes to Minnesota Statutes 62A.31 took effect August 1, 2026. People ages 65 to 70 applying for Medigap for the first time can now buy without health questions in two yearly windows.
October 15 to December 7. Coverage starts January 1 of the next year. The 2026 window is open now.
January 1 to March 31. Coverage starts the first day of the next month.
Age 71 or older. Not eligible for these windows. You can still apply at any time with medical underwriting.
Already have Medigap. The windows are for first-time buyers. Switching policies generally still means health questions.
| Year you enroll in a window | Surcharge | BCBS MN Extended Basic with surcharge (our math) |
|---|---|---|
| 2026 | 15% | $4,266.50 a year |
| 2027 | 20% | $4,452.00 a year |
| 2028 | 25% | $4,637.50 a year |
| 2030 and later | 35% | $5,008.50 a year |
Surcharge levels from Bulletin 2026-3. It applies every year for the life of the policy, on top of tobacco and area factors. Our example applies it to the $3,710 non-tobacco premium from the 10/01/2026 guide.
Lower-Premium Options in Minnesota
Besides Basic and Extended Basic, some companies file cost-sharing, copay and high-deductible designs. Omaha Insurance Company’s non-tobacco row in the 10/01/2026 guide shows the range one carrier offers.
| Omaha Insurance Co. plan (non-tobacco) | Yearly premium | Per month (our math) |
|---|---|---|
| High-deductible plan | $671 | $55.92 |
| 50% cost-sharing plan | $1,858 | $154.83 |
| $20 and $50 Part B copay plan | $2,350 | $195.83 |
| 75% cost-sharing plan | $2,642 | $220.17 |
| Basic plan | $3,426 | $285.50 |
| Extended Basic plan | $4,156 | $346.33 |
Source: MN Commerce Department Annual Premium Guide, updated 10/01/2026.
The 50% and 75% plans work like Plans K and L elsewhere, sharing costs up to a yearly cap. Our Medicare Supplement Plan K 2027 page shows how to run break-even math on a cost-sharing plan.
How to Choose a Minnesota Plan for 2027
Start in your six-month open enrollment if you can. When your Part B starts at 65 or older, federal rules let you buy any plan without health questions.
Decide on the Part A deductible first. One hospital stay in 2027 could cost $1,776. Basic plus the rider covers it for $136 to $761 less a year than Extended Basic at the five carriers above.
Ask whether you will pay the surcharge. If you are 65 to 70 and using the new October 15 to December 7 window, compare the surcharged price with an underwritten quote if you are in good health.
Compare rural and urban rates. Several carriers price by area, and the gap can be several hundred dollars a year.
Timing rules for the rest of the country are in our Medicare Supplement open enrollment 2027 guide.
Bottom Line
Minnesota Medigap shoppers choose between the state’s Basic and Extended Basic plans, plus riders and lower-cost designs, instead of Plan G. On the October 2026 state guide, Basic plus a Part A deductible rider saved $136 to $761 a year over Extended Basic at the five carriers we compared, and first-time buyers ages 65 to 70 can now enroll without health questions in exchange for a lifelong surcharge.
See Basic and Extended Basic rates for your Minnesota ZIP
Minnesota Medicare Supplement Plans 2027 — Frequently Asked Questions
➤ Can I buy Plan G in Minnesota?
No. Minnesota uses its own standardized plans under a federal waiver. The closest match to Plan G is the Extended Basic plan or the Basic plan with riders added.
➤ What is the difference between Basic and Extended Basic in Minnesota?
Extended Basic adds the Part A deductible, Part B excess charges, preventive care up to $120 a year and broader coverage of some costs Medicare does not pay. Basic covers those only through optional riders.
➤ Who qualifies for Minnesota’s new Medigap guaranteed issue windows?
People ages 65 to 70 applying for Medigap for the first time. The windows run October 15 to December 7 and January 1 to March 31, starting August 1, 2026.
➤ How much is the surcharge for enrolling through the new windows?
Bulletin 2026-3 sets it at 15% for 2026 enrollments, 20% for 2027, 25% for 2028, 30% for 2029 and 35% from 2030 on. It stays on the policy for life.
➤ Does the surcharge apply if I buy during my first six months on Part B?
The bulletin ties the surcharge to policies issued through the new windows. Your federal six-month Medigap open enrollment is a separate right; ask the insurer to confirm which rate applies to your application.
➤ Which companies sell Medicare Supplement plans in Minnesota?
The October 2026 state guide lists companies including BlueCross BlueShield of Minnesota, Medica, HealthPartners, Medico, Omaha Insurance Company, State Farm, Washington National and UnitedHealthcare.
➤ Do Minnesota doctors charge Part B excess charges?
Minnesota does not allow Part B excess charges for care received in the state. You could still face them when you get care in another state.
➤ Does Minnesota’s Basic plan pay the Part B deductible?
Not for people newly eligible for Medicare. Federal law and Minnesota law bar Medigap plans from paying the Part B deductible for anyone first eligible in 2020 or later.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll