How to Change Medicare Supplement Plans With Pre-Existing Conditions in 2027
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 5, 2026
You can change Medicare Supplement plans with pre-existing conditions without health questions only if you have a federal guaranteed issue right or live in a state with a birthday, anniversary or year-round switching rule. Otherwise the new insurer may ask about your health and can decline you or charge more, so keep your current policy until the new one is approved.
2027 by the Numbers
63 days
federal window after most coverage losses to buy Medigap with no health questions
20+
states with a birthday, year-round or other yearly Medigap switching rule on the NAIC May 2026 chart (our count)
Jan 1, 2027
New Mexico’s new birthday rule takes effect (NAIC chart)
$1,626.84
yearly gap between the lowest and highest Plan G rate for a 65-year-old man in New Jersey, September 2026 (our math)
After your six-month Medigap open enrollment period ends, a new Medicare Supplement policy is usually medically underwritten. That means the application asks about diagnoses, treatments and medications, and the insurer can say no. A health condition does not trap you, though. Federal law and a growing list of state rules carve out moments when the health questions are not allowed.
This guide sorts those moments into federal rights, state rules (including several that changed in 2026 and one that starts in 2027) and what to do when you have neither. If you are still inside your first open enrollment, read our Medicare Supplement open enrollment 2027 guide first.
See Which 2027 Plans You Qualify For
When an Insurer Can and Cannot Ask Health Questions
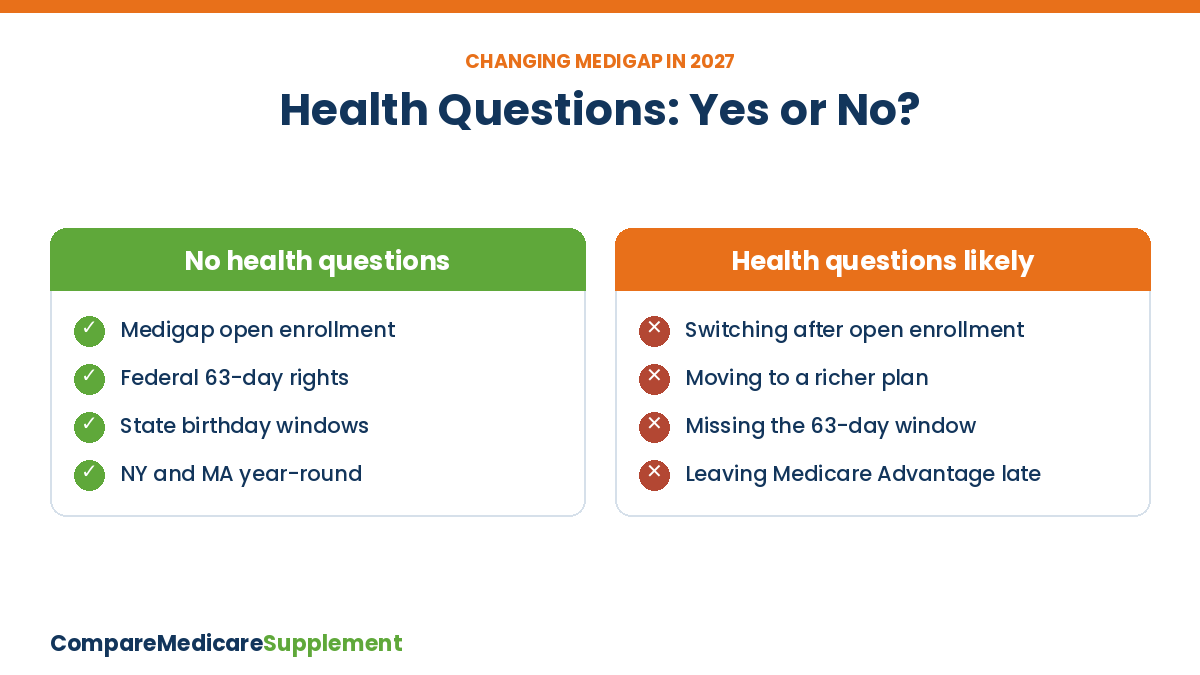
Cannot ask: your Medigap open enrollment. The six months starting the month your Part B begins at 65 or older. Any company must sell you any plan it offers at its best standard rate.
Cannot ask: a guaranteed issue right. Federal situations such as losing employer coverage or your Medicare Advantage plan leaving your area, each with a 63-day window.
Cannot ask: a state switching window. States with a birthday, anniversary or continuous enrollment rule let you move to an equal or lesser plan without underwriting during set dates.
Can ask: every other time. Changing plans, even to fewer benefits, normally means a health questionnaire, and the insurer may decline or rate you up.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Federal Guaranteed Issue Rights That Override Your Health History
| Situation | When to apply | Plans you can buy |
|---|---|---|
| Medicare Advantage plan leaves Medicare, stops serving your area, or you move out of its area | From 60 days before coverage ends to 63 days after | A, B, C*, D*, F*, G*, K, L |
| Employer, retiree, COBRA or union coverage that pays after Medicare is ending | Up to 63 days after the coverage end date, notice or claim denial | A, B, C*, D*, F*, G*, K, L |
| Medigap insurer goes bankrupt or coverage ends through no fault of yours | Up to 63 days after coverage ends | A, B, C*, D*, F*, G*, K, L |
| Trial right: joined Medicare Advantage at 65 and leave within the first year | From 60 days before to 63 days after coverage ends | Any Medigap plan sold in your state |
| Trial right: dropped Medigap for Medicare Advantage for the first time and leave within a year | From 60 days before to 63 days after coverage ends | Your old policy if still sold, otherwise A, B, C*, D*, F*, G*, K, L |
| Insurer or plan broke the rules or misled you | Up to 63 days after coverage ends | A, B, C*, D*, F*, G*, K, L |
Source: Indiana SHIP summary of federal Medigap rights. *Plans C and F only for people eligible for Medicare before 2020; D and G for people newly eligible in 2020 or later. Plan N is not on the federal guaranteed issue list.
Easy to miss: Plan N is not one of the plans federal guaranteed issue rights require insurers to sell. If Plan N is your goal, ask the insurer or your state whether it will accept you without health questions.
State Rules That Let You Switch Without Underwriting
The National Association of Insurance Commissioners keeps a state-by-state chart of these rules; the version below reflects its May 11, 2026 update. Most rules allow a move only to a plan with equal or lesser benefits, and several limit you to your current insurer.
| State | Rule | Key limits |
|---|---|---|
| California, Oregon | Birthday rule | CA: 60+ days from your birthday. OR: 30 days before to 30 days after. Equal or lesser plan, any insurer |
| Idaho, Louisiana, Wyoming | Birthday rule, 63 days | Equal or lesser plan; Louisiana limits you to your current insurer or affiliates |
| Illinois | Birthday rule, 45 days | Ages 65-75, current insurer or affiliate only |
| Kentucky, Oklahoma, Nevada | Birthday rule, 60 days | KY: same plan, different company. NV: from the 1st of birth month (since Oct 1, 2025) |
| Maryland | Birthday rule, 30 days | Equal or lesser benefits |
| Delaware, Indiana | New in 2026 | DE: birthday window, equal or lesser plan. IN: switch to another insurer’s version of your current plan |
| West Virginia | New June 11, 2026 | Every two years, after 24 months of continuous coverage, usually same insurer |
| New Mexico | Starts January 1, 2027 | At least 60 days from your birthday month, equal or lesser plan, any insurer |
| New York, Massachusetts | Year-round | Continuous open enrollment |
| Maine, Washington | Anytime switching | ME: equal or lesser plan with no 90-day gap. WA: switch among Plans B-N |
Source: NAIC Medigap birthday rule chart, May 11, 2026. Virginia, Rhode Island and Utah also have switching windows. Rules change often; confirm with your state insurance department before you cancel anything.
Our state guides list each local rule in more detail, such as Illinois 2027 and California.
How a Medically Underwritten Switch Works
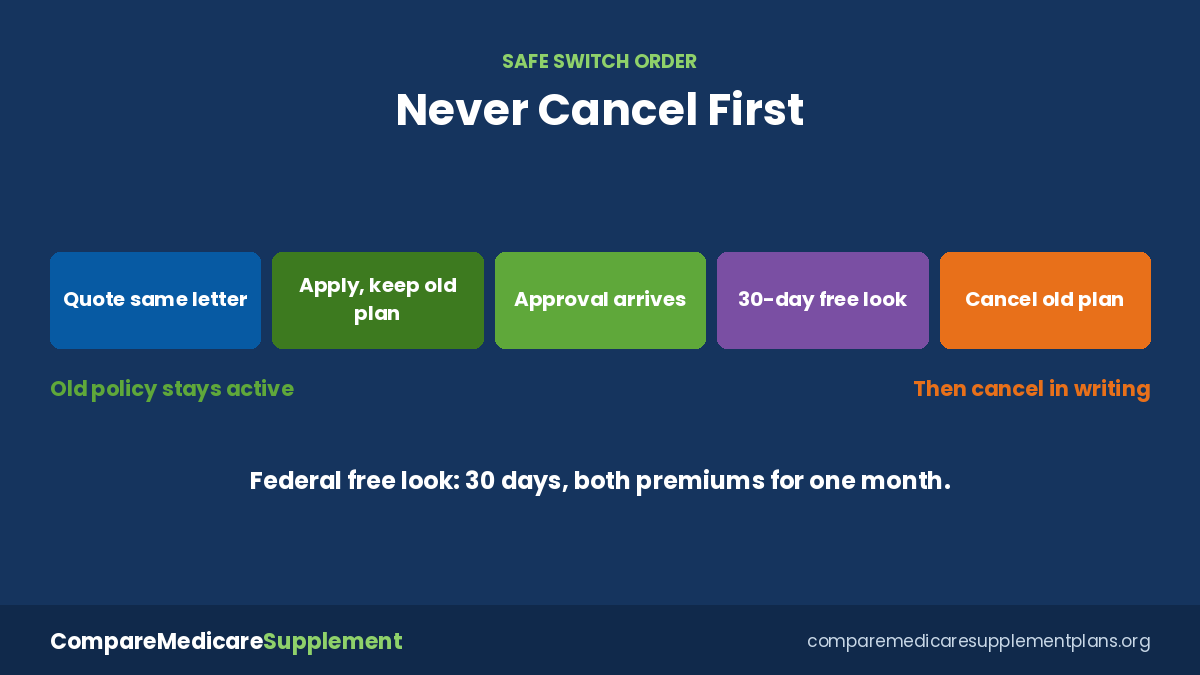
Get quotes for the same plan letter first. Every Plan G pays the same benefits by law, so a cheaper Plan G from another company is a pure price change.
Read the health questions before you apply. Applications usually ask about specific conditions, recent hospital stays and planned surgery within set look-back periods. Answer every question accurately.
Apply while your current policy stays active. Do not cancel anything until you have the new approval and policy number in hand.
Use the free look. Federal rules give you 30 days to review a new Medigap policy. You pay both premiums for that month, then cancel the old policy in writing.
Ask about a lower plan if declined. Some insurers will approve a plan with fewer benefits, such as Plan N, when they decline Plan G.
Is Switching Worth the Paperwork?
Price spreads for the same plan are large. New Jersey’s Division of Aging Services chart for a 65-year-old man, September 2026, shows these ranges for identical benefits.
| Plan (NJ, man 65) | Lowest monthly | Highest monthly | Yearly difference (our math) |
|---|---|---|---|
| Plan G | $164.31 | $299.88 | $1,626.84 |
| Plan N | $119.90 | $200.84 | $971.28 |
| High-deductible Plan G | $50.83 | $92.08 | $495.00 |
Rates effective September 2026 (revised 8/26/2026). New Jersey has no birthday rule on the NAIC chart, so switches there are usually underwritten.
If the gap at your age is a few dollars, the risk of losing an approved policy may not be worth it. If it is over $1,000 a year, getting quotes is usually worthwhile. Our 2027 rate increase guide explains how to read a renewal letter before you shop.
If You Are Declined
Your current plan cannot drop you. Medigap is guaranteed renewable. As long as you pay the premium, your insurer cannot cancel you because of your health.
Watch for a state window. If you live in a birthday-rule state, mark your birthday window on the calendar; New Mexico residents gain one starting January 1, 2027.
Medicare Advantage is a one-way door for many. You can join Medicare Advantage during the October 15 to December 7 enrollment period without health questions, but returning to Medigap later may require underwriting. See Medicare Advantage vs Medicare Supplement 2027.
Bottom Line
Pre-existing conditions only block a Medicare Supplement change when you have no guaranteed issue right and no state switching window. Check the federal situations, then your state’s rule, and never cancel your current policy before the new one is approved.
Compare 2027 Medicare Supplement rates for your situation
Changing Medicare Supplement Plans With Pre-Existing Conditions — Frequently Asked Questions
➤ Can a Medicare Supplement company deny me for a pre-existing condition?
Yes, outside your open enrollment period, a guaranteed issue right or a state switching window. In those cases the insurer can review your health and decline the application or charge a higher rate.
➤ Does my current Medigap insurer need to approve a switch to a lower plan?
Usually the new policy is underwritten even when it has fewer benefits, unless your state has a birthday, anniversary or year-round rule that covers the move.
➤ Which states have a Medigap birthday rule in 2027?
The NAIC’s May 2026 chart lists birthday rules in states including California, Delaware, Idaho, Illinois, Kentucky, Louisiana, Maryland, Nevada, Oklahoma, Oregon, Virginia and Wyoming, with New Mexico’s rule starting January 1, 2027.
➤ Is there a waiting period for pre-existing conditions on a new Medigap policy?
A new policy can exclude pre-existing conditions for up to six months, but not if you had at least six months of prior creditable coverage without a long break. Most people replacing a Medigap policy meet that test.
➤ Can I switch from Medicare Advantage back to Medigap with health problems?
Only with a trial right, a guaranteed issue situation such as your plan leaving the area, or a state rule. Otherwise the Medigap insurer can underwrite you.
➤ Do I lose my right to switch if I miss the 63-day window?
Yes, for that federal guaranteed issue situation. You can still apply with health questions, or wait for a state window if your state has one.
➤ Can I have two Medigap policies while I switch?
Yes, briefly. The 30-day free look lets you keep both while you decide, but you pay both premiums for that month.
➤ Does Minnesota have a new rule for people with health conditions?
Minnesota added guaranteed issue windows starting August 1, 2026 for people ages 65 to 70 buying Medigap for the first time, with a premium surcharge. It does not cover people switching from one Medigap policy to another.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll