Medicare Supplement Rate Increases 2027: What State Filings Show and How to Respond
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 1, 2026
Medicare Supplement rate increases for 2027 are running from about 5% to 25% in the public state filings we reviewed, with closed plans such as Plan F and Plan C seeing the largest requests. In Connecticut, Anthem asked for 5.2% on Plan G and 13% on Plan N for January 2027, while Transamerica asked for 25%; final increases depend on each state’s review.
2027 by the Numbers
5.2% to 25%
range of 2026 Connecticut Medigap rate requests we reviewed (CT Insurance Department notices)
9 of 18
New Jersey companies that raised their age-65 Plan G price between April and September 2026 (our math)
25.5%
largest jump on that NJ list: UnitedHealthcare’s standard Plan G, $188.97 to $237.23 (our math)
65% / 75%
federal minimum loss ratios for individual and group Medigap policies (GAO)
Every Medigap company files new rates with state regulators, and most policyholders see at least one increase a year. With 2027 notices arriving this fall, the useful question is not whether rates rise but how much, why, and what you can do about it.
We pulled real numbers from two public sources: Connecticut’s 2026 public hearing notices on Medigap rate requests and New Jersey’s official age-65 price charts from April and September 2026. For what different plans cost today, see our 2027 Medicare Supplement cost guide.
Compare 2027 Rates Before You Renew
Real 2027 Rate Requests From Connecticut
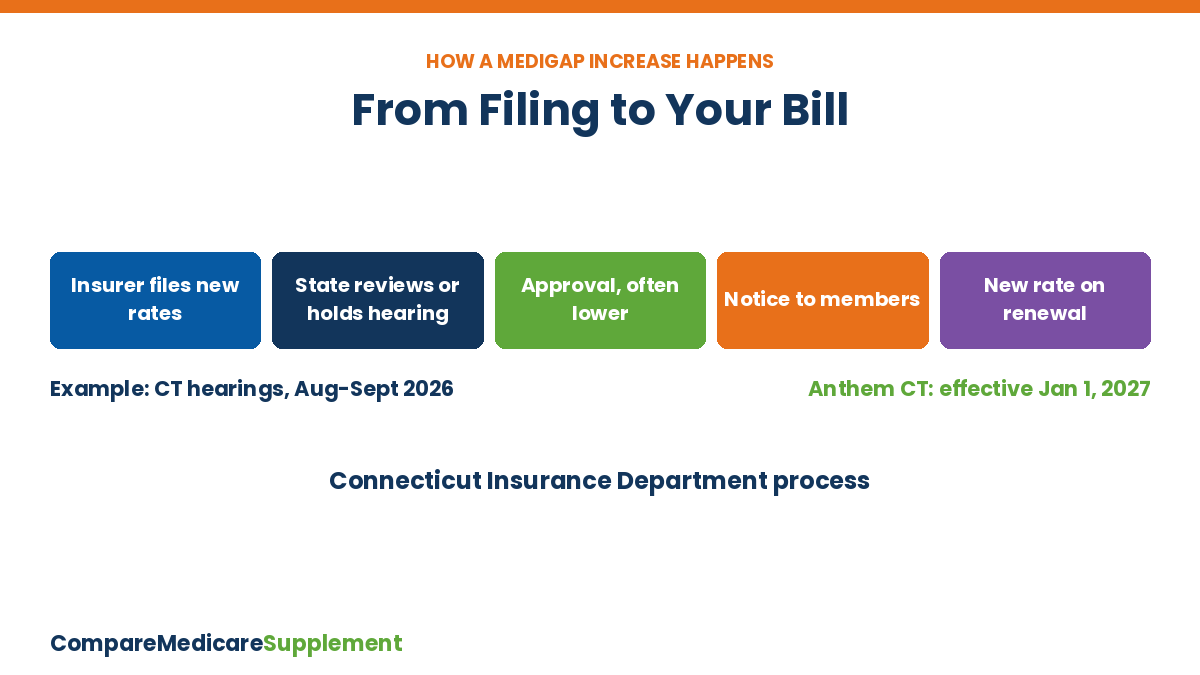
Connecticut holds public hearings when insurers ask to raise Medigap rates, and it posts each request. Three 2026 notices give a clear look at what companies are asking for heading into 2027.
| Company (Connecticut) | Plans | Requested increase | Hearing |
|---|---|---|---|
| Anthem Blue Cross and Blue Shield | Modernized Plan G and Plan F | 5.2% | September 1, 2026 |
| Anthem Blue Cross and Blue Shield | Modernized Plan N | 13.0% | September 1, 2026 |
| Anthem Blue Cross and Blue Shield | High-deductible F and standardized Plan C | 19.9% | September 1, 2026 |
| Bankers Life and Casualty | Individual Plan F and high-deductible F | 20.0% | August 11, 2026 |
| Transamerica Life | Plans A, F, G, K, L and N on one policy form | 25.0% | August 21, 2026 |
Source: Connecticut Insurance Department public hearing notices, dockets LH-26-68 through LH-26-72. These are requests; the department can approve less. Connecticut’s rate list shows Anthem’s new rates approved September 3, 2026, effective January 1, 2027.
What stands apart: The largest requests land on plans closed to new buyers. Plan F and Plan C cannot be sold to anyone eligible for Medicare from 2020 on, so their pools only get older.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Our Tally: New Jersey Price Changes During 2026
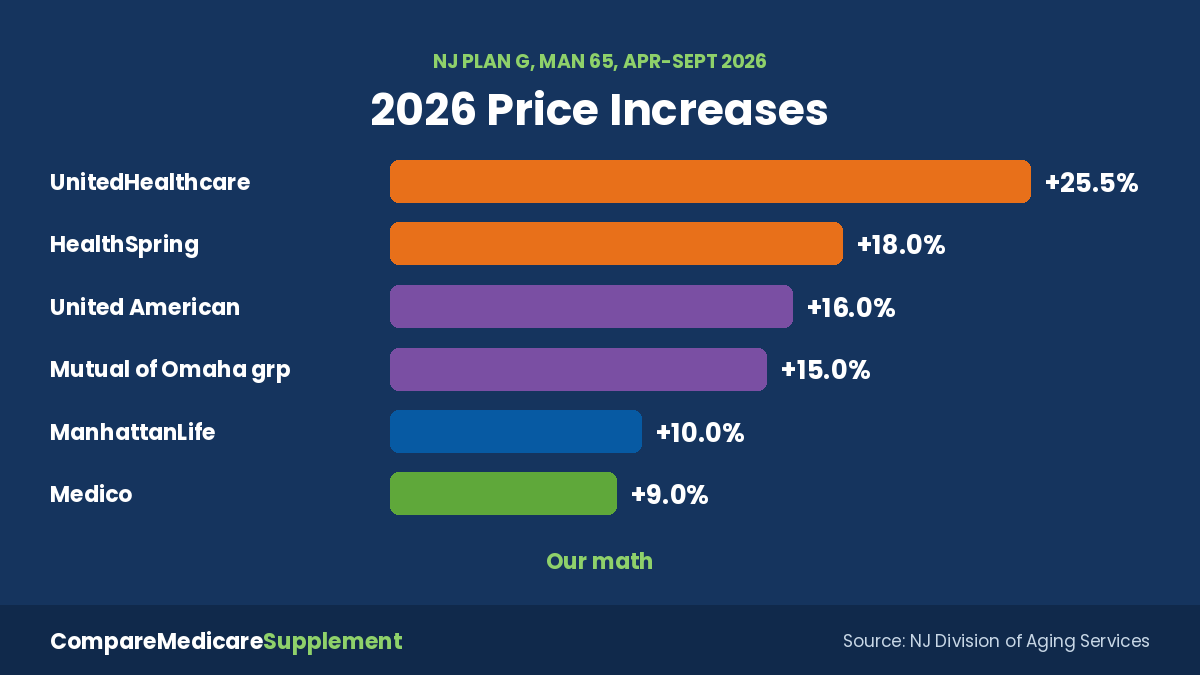
New Jersey’s Division of Aging Services republishes every company’s age-65 rates several times a year. We matched the April 2026 and September 2026 male charts company by company for Plan G.
| Company (NJ Plan G, man 65) | April 2026 | September 2026 | Our math |
|---|---|---|---|
| UnitedHealthcare (standard) | $188.97 | $237.23 | +25.5%, +$579 a year |
| United American | $243.00 | $282.00 | +16.0%, +$468 a year |
| Aflac (Tier One) | $196.68 | $226.18 | +15.0%, +$354 a year |
| ManhattanLife | $205.42 | $226.00 | +10.0%, +$247 a year |
| LifeShield National | $189.92 | $207.02 | +9.0%, +$205 a year |
| Nine other companies | — | — | No change |
Our comparison of NJ Division of Aging Services Male Preferred Rates at Age 65 charts, April 2026 and September 2026 (revised 8/26/2026). Four more companies with increases are not shown. The median Plan G price across the 18 companies rose from $199.27 to $219.65.
High-deductible G moved too: HealthSpring’s NJ price went from $61.39 to $92.08, a 50% jump, though from a small base. These are new-buyer prices at 65; existing members see changes on their own renewal dates.
Why Medigap Rates Keep Rising
Medical costs. Medigap pays a share of every Medicare-approved bill, so when doctor and hospital spending grows, claims grow with it.
Age-based pricing. Under attained-age pricing your premium also steps up as you get older, separate from any filed increase.
Aging pools. When few new people join a plan, the remaining group gets older and costlier, which drives bigger increases on closed plans.
Loss ratio rules. Federal standards expect insurers to pay out at least 65% of premiums on individual policies and 75% on group policies; regulators review filings with that in mind.
Medicare’s own costs rise as well. The Part B premium is $209.40 a month for 2027 and the Part B deductible at $292, per CMS.
What a Rate Increase Means in Dollars
Percentages hide the real cost. We applied common increase levels to a $220 monthly Plan G, close to New Jersey’s September 2026 median for a 65-year-old man.
| Increase | New monthly premium | Extra per year | If repeated 3 years in a row |
|---|---|---|---|
| 5.2% | $231.44 | $137.28 | $256.14 a month |
| 10% | $242.00 | $264.00 | $292.82 a month |
| 15% | $253.00 | $396.00 | $334.59 a month |
| 25% | $275.00 | $660.00 | $429.69 a month |
Our math on a $220 starting premium. Attained-age increases would add to these figures.
Three straight 10% increases raise a premium by 33%, not 30%, because each increase builds on the last. That compounding is why a company’s rate history matters as much as its starting price.
Your Options When the 2027 Notice Arrives
Compare the same plan letter elsewhere. Benefits are identical, so a lower price at another A-rated company is a pure saving. Our 2027 company scorecard shows who moved prices in 2026.
Check your state’s switching rules. About 16 states have birthday-style windows in 2027, and New York and Connecticut accept applicants all year.
Consider a lower-premium letter. Moving from Plan G to Plan N often saves more than a typical increase; see our Plan G vs Plan N cost test.
Ask about discounts. A household discount can offset part of an increase if you did not claim it at purchase.
Keep your policy if your health makes switching hard. A guaranteed renewable policy cannot be canceled for health reasons as long as you pay the premium.
When Staying Put Is the Better Call
Outside a protected window, most states let a new company ask health questions. If you have a recent diagnosis or upcoming surgery, a modest increase on a policy you cannot lose may be worth more than a cheaper policy you might not be approved for.
Before you cancel: Never drop your current policy until the new one is approved in writing and its start date is set. Medigap companies allow a 30-day free look on a replacement policy, so the two can overlap briefly.
If you are not yet enrolled, pricing several companies during your Medicare Supplement open enrollment window is the best protection against future increases, because every company must accept you then.
Bottom Line
Public filings point to 2027 Medigap increases of roughly 5% to 25%, highest on closed plans like F and C, and half the companies on New Jersey’s chart raised Plan G prices during 2026. When your notice arrives, compare the same plan letter elsewhere, check your state’s switching rules and only switch once a new policy is approved.
See if another company charges less for your plan in 2027
Medicare Supplement Rate Increases 2027 — Frequently Asked Questions
➤ How much will Medicare Supplement rates go up in 2027?
It depends on the company and state. Connecticut’s 2026 filings ranged from 5.2% for Anthem’s Plan G to 25% for Transamerica, and final approvals can be lower than requests.
➤ Why is my Plan F increase bigger than my neighbor’s Plan G increase?
Plan F has been closed to people new to Medicare since 2020, so its pool is aging and costs rise faster. Connecticut requests for Plan F reached 20%.
➤ Who approves Medigap rate increases?
Your state insurance department reviews each company’s filing. Some states, like Connecticut, hold public hearings first.
➤ Can my Medigap company cancel me for filing claims?
No. Medigap policies sold today are guaranteed renewable, so the company cannot cancel you as long as you pay the premium.
➤ Is it worth switching companies after a rate increase?
Often, if you can pass health questions or use a state switching window. Coverage is identical, so only price and stability change.
➤ Do rates go up on my birthday?
With attained-age pricing, your premium can step up as you age, often on your policy anniversary, in addition to filed increases.
➤ Does the Part B premium increase affect my Medigap premium?
Not directly. They are separate bills, but both tend to rise with medical costs.
➤ How can I protect myself from big increases before I buy?
Compare prices at older ages, ask about recent rate history and buy during your open enrollment window when every company must accept you.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll