Best Medicare Supplement Plans 2027
Best Medicare Supplement Plans 2027: The Right Plan for Your Budget and Health
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 29, 2026
The best Medicare Supplement plan for most people in 2027 is Plan G, because it leaves only the Part B deductible (projected at $292) uncovered. Plan N is often the better value if you are healthy and rarely see doctors, and high-deductible Plan G is the cheapest way to protect against a bad year if you can afford its $3,050 deductible.
2027 by the Numbers
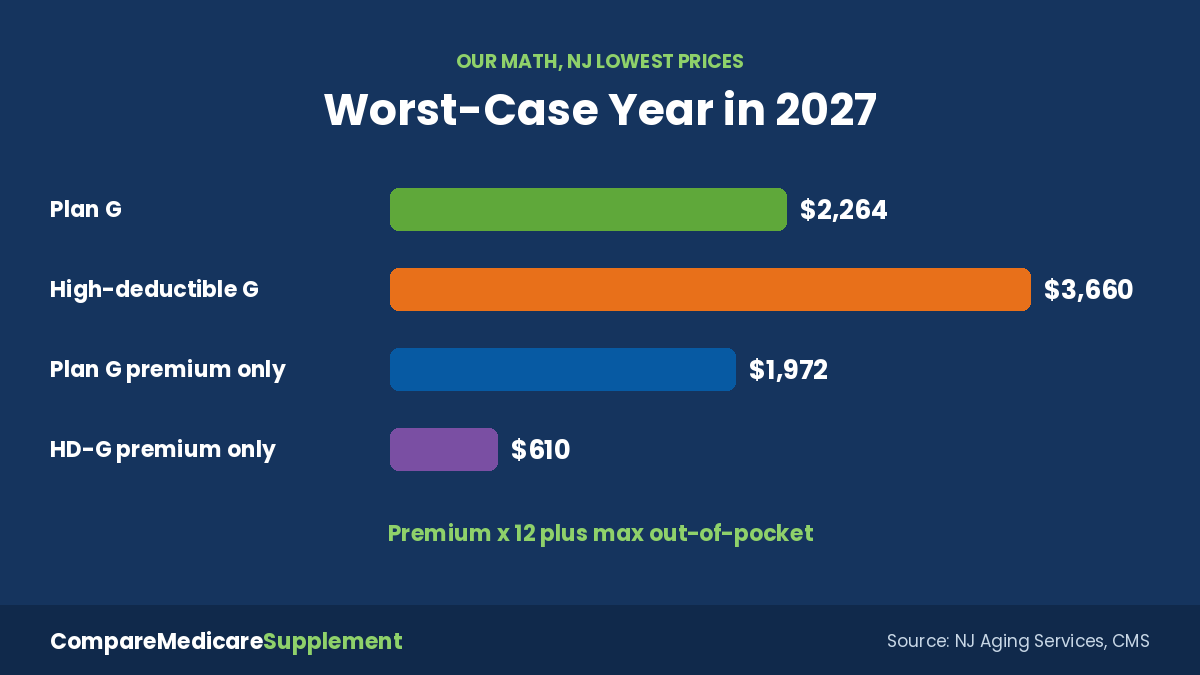
$2,264
Plan G worst-case year: lowest NJ premium x 12 + projected $292 Part B deductible (our math)
$3,660
High-deductible G worst-case year: lowest NJ premium x 12 + $3,050 deductible (our math)
$3,050
2027 high-deductible G deductible (CMS)
Lists of the “best” Medicare Supplement plans usually rank insurance companies. That skips the decision that matters first: which plan letter fits you. Plan benefits are standardized by law, so the plan letter decides your coverage, and the company decides your price and how that price changes later.
Below we compare the three plans that make sense for most people new to Medicare in 2027, using real premiums from New Jersey’s official September 2026 rate chart and the 2027 amounts CMS has published. We show what each plan costs in a quiet year and in a year with a hospital stay, so you can pick on numbers instead of labels. For the full list of all 10 plans, see Medicare Supplement plans 2027.
See the Best 2027 Medicare Supplement Rates Near You
How We Judge the Best Medicare Supplement Plan
A plan is only “best” for a specific person. We use four tests, in this order.
Worst-case year. What is the most you could pay in premiums plus out-of-pocket costs if you had a major illness? Lower is safer.
Quiet-year cost. What do you pay if you only see a doctor for routine visits? This is where low-premium plans win.
Who can buy it. Plans F and C are closed to anyone who became eligible for Medicare on or after January 1, 2020.
Future price. How the company prices the plan and how often it has raised rates. This matters more over 15 years than the first-year premium.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Plan G: Best All-Around Medicare Supplement Plan for 2027
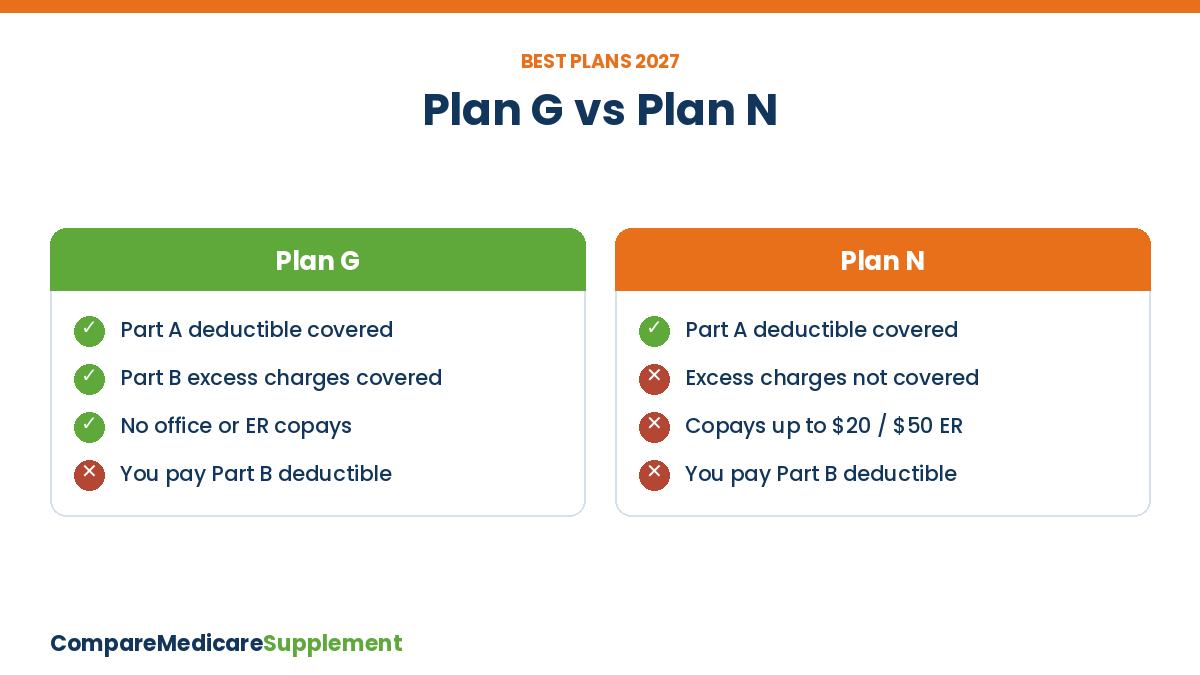
Plan G pays the Part A hospital deductible, all Part A and Part B coinsurance, skilled nursing coinsurance, Part B excess charges and 80% of emergency care abroad (after a $250 deductible, up to plan limits). The only Medicare gap it leaves is the Part B deductible, projected at $292 for 2027.
| Plan G, New Jersey, man age 65 | Monthly | Yearly |
|---|---|---|
| Lowest-priced company | $164.31 | $1,971.72 |
| Highest-priced company | $299.88 | $3,598.56 |
| Worst-case year with lowest price (premium + $292) | — | $2,263.72 |
Premiums: NJ Division of Aging Services chart, September 2026 rates. Yearly and worst-case figures are our calculation.
Who it suits: People who see specialists, have a chronic condition, travel, or simply want to know their maximum cost each year. You can learn the plan’s details in our Medicare Supplement Plan G 2027 guide.
Plan N: Best Value If You Rarely Go to the Doctor
Plan N covers the same big costs as Plan G but asks you to share small ones. You pay the Part B deductible, a copay of up to $20 for some office visits, up to $50 for an emergency room visit that does not end in admission, and any Part B excess charges if a doctor does not accept Medicare’s approved amount.
In New Jersey’s chart the lowest Plan N premium was $119.90 a month versus $164.31 for the lowest Plan G, a gap of $532.92 a year. At up to $20 a visit, you would need more than 26 copay visits in a year before Plan N cost more than Plan G at those prices, not counting excess charges.
Watch out for: Excess charges. Eight states ban them (Connecticut, Massachusetts, Minnesota, New York, Ohio, Pennsylvania, Rhode Island and Vermont). Elsewhere a doctor who does not accept assignment can bill up to 15% above Medicare’s amount, and Plan N does not cover it. Compare the two plans in detail in our Plan N overview.
High-Deductible Plan G: Best for a Tight Monthly Budget
High-deductible Plan G has the same benefits as Plan G, but only after you pay $3,050 in covered costs in 2027. Until then you pay what Medicare does not. Its premium is a fraction of regular Plan G.
| Plan | Lowest NJ monthly premium | Premium per year | Worst-case year |
|---|---|---|---|
| Plan G | $164.31 | $1,971.72 | $2,263.72 |
| High-deductible Plan G | $50.83 | $609.96 | $3,659.96 |
Worst case = yearly premium plus the plan’s maximum out-of-pocket (projected $292 Part B deductible for Plan G; $3,050 deductible for high-deductible G). Our calculation from NJ September 2026 rates.
In a healthy year the high-deductible version saves about $1,360 in premium. In a bad year it costs about $1,396 more. If you have savings to cover the deductible and you are in good health, it can be the best value of the three.
Best Plan by Situation
| Your situation | Best fit for 2027 | Why |
|---|---|---|
| New to Medicare, want the most coverage you can buy | Plan G | Only the Part B deductible is left to you |
| Healthy, few doctor visits, live where excess charges are banned | Plan N | Lower premium, and the excess-charge risk disappears |
| Healthy with savings, want the lowest premium | High-deductible Plan G | Same protection after $3,050 |
| Eligible for Medicare before 2020 | Plan F or Plan G | Compare prices; F also pays the Part B deductible |
| Want a hard yearly cap with low premiums | Plan K or Plan L | 2027 out-of-pocket caps of $8,360 and $4,180 |
Not sure how Medigap compares with Medicare Advantage at all? Our Medicare Advantage overview explains the other path.
How to Pick the Best Company for Your Plan
Compare the same letter. Get Plan G or Plan N quotes from several companies in your ZIP code. Coverage is identical, so you are comparing price and stability.
Check the pricing method. Attained-age plans rise as you age, issue-age plans are priced on your age when you buy, and community-rated plans charge everyone the same. Which methods exist depends on your state.
Look at rate history. Ask how much the company has raised that plan in recent years. A low starting price followed by steep increases can cost more over time.
Ask about discounts. Many companies offer household or other discounts. They vary by company and state, so compare final prices, not list prices.
Bottom Line
For most people new to Medicare in 2027, Plan G is the best Medicare Supplement plan because it caps your yearly Medicare costs at the Part B deductible. Plan N wins on price if you are healthy and live where excess charges are banned, and high-deductible G is the cheapest protection if you can cover $3,050 in a bad year. Choose the letter first, then compare companies.
Compare Plan G, Plan N and high-deductible G in your ZIP
Best Medicare Supplement Plans 2027 — Frequently Asked Questions
➤ What is the best Medicare Supplement plan for 2027?
For most new enrollees it is Plan G, which pays everything Original Medicare leaves except the Part B deductible. Plan N and high-deductible Plan G can be better values for people who are healthy and want lower premiums.
➤ Is Plan N better than Plan G?
Plan N has a lower premium, but you pay small copays, the Part B deductible and any excess charges. If you see doctors often or live where excess charges are allowed, Plan G is usually the safer choice.
➤ Is high-deductible Plan G worth it in 2027?
It can be if you are healthy and can afford the $3,050 deductible. Using New Jersey’s lowest prices, it saves about $1,360 a year in premiums but can cost about $1,396 more in a year with heavy medical use.
➤ Which Medicare Supplement plan covers the most?
Plan F covers the most, including the Part B deductible, but only people eligible for Medicare before 2020 can buy it. For everyone else, Plan G covers the most.
➤ Are the best plans the same in every state?
The benefits of each lettered plan are the same in every state except Massachusetts, Minnesota and Wisconsin, which use their own designs. Prices and the companies selling them vary by state.
➤ Which company has the best Medicare Supplement plan?
No single company is best everywhere. Because coverage is identical, the best company is the one with a fair price in your ZIP code and a steady history of rate increases.
➤ Does the best plan change as I get older?
Your needs may change, but switching later usually means answering health questions. That is why many people choose the plan they would want at 80 when they first enroll.
➤ Do any Medicare Supplement plans cover prescriptions?
No. You need a separate Part D plan, which in 2027 has a deductible of up to $700 and a $2,400 yearly out-of-pocket cap.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll