Medigap Plan N 2027: Copays, Excess Charges and When It Beats Plan G
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 29, 2026
Medigap Plan N in 2027 pays the same hospital and doctor costs as Plan G, except that you pay the Part B deductible (projected at $292), copays of up to $20 per office visit and up to $50 per ER visit, and any Part B excess charges. In exchange, Plan N usually costs hundreds of dollars a year less than Plan G, and anyone with Medicare Part A and Part B can buy it.
2027 by the Numbers
$20 / $50
most you pay per covered office visit / ER visit not followed by an inpatient admission (CMS Plan N rules)
15%
most a non-participating doctor can bill above Medicare’s approved amount, which Plan N does not pay
$672-$1,272
yearly premium saved with Plan N vs Plan G, man 65, five companies (Maryland July 2026 guide, our math)
34-64
office copays it would take to use up those savings (our math)
Plan N is the Medigap plan people pick when they want strong protection against big hospital bills but do not want to pay Plan G prices for small bills they can handle themselves. The trade is a few copays and one risk most people never hear about: excess charges.
Below we explain exactly when the copays apply, how large the excess charge risk really is, and how many doctor visits it takes before Plan N stops saving money, using official rate data. For the full picture of Plan G, see our Medicare Supplement Plan G 2027 guide.
Compare 2027 Plan N and Plan G Rates
How the Plan N Copays Really Work
Plan N’s copays come from federal rules written by the NAIC and CMS. The details are narrower than most people think, and they can save you money.
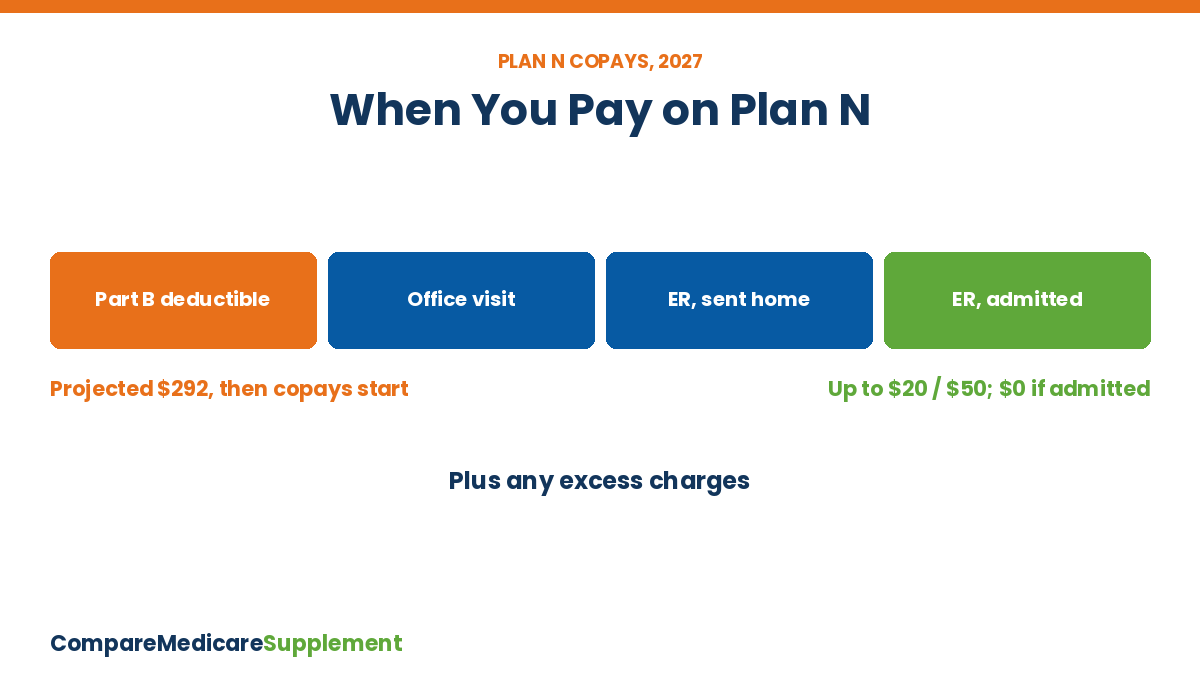
Office visits: up to $20. Charged per covered office visit after you meet the Part B deductible. If the 20% Medicare coinsurance on the visit is less than $20, you pay the smaller amount.
ER visits: up to $50. Charged per covered emergency room visit. It is waived if you are admitted to the hospital and the visit is covered under Part A.
No copay for lab work or X-rays. Under CMS’s Plan N guidance, lab, X-ray and medical equipment charges do not trigger the office copay.
Two visits, two copays. If you see two doctors on the same day, each office visit can carry its own copay.
Watch out for observation status: The ER copay is waived only for an inpatient admission covered by Part A. If the hospital keeps you overnight under outpatient observation instead, the visit is billed under Part B and the $50 copay may still apply. Ask the hospital whether you are admitted or under observation.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
What You Pay With Plan N in a Typical 2027 Year
Here is a sample year for someone who sees a doctor a few times and makes one ER trip. The amounts are what you pay on top of your monthly premiums.
| 2027 event | You pay with Plan N | You pay with Plan G |
|---|---|---|
| First doctor bills of the year | Up to $292 Part B deductible (projected) | Up to $292 Part B deductible (projected) |
| 6 office visits after the deductible | Up to $120 in copays | $0 |
| 1 ER visit, sent home | Up to $50 | $0 |
| 3-day hospital stay | $0 (Plan N pays the projected $1,788 Part A deductible) | $0 |
| Lab work and X-rays | $0 after the deductible | $0 after the deductible |
Our illustration. 2027 Part A and B deductibles are Medicare Trustees projections; CMS announces final amounts, usually in November.
In this example, Plan N’s extra out-of-pocket cost is up to $170 for the year, before any excess charges. The real question is whether your Plan N premium savings beat that number.
Excess Charges: The Real Risk With Plan N
Doctors who accept Medicare assignment take Medicare’s approved amount as full payment. Doctors who take Medicare but do not accept assignment on a claim can bill you up to 15% more. That extra is an excess charge, and Plan N does not pay it.
| Medicare-approved amount | Most a non-assigned doctor can add (15%) | Who pays it |
|---|---|---|
| $200 specialist visit | $30 | You, on Plan N |
| $2,000 surgeon’s fee | $300 | You, on Plan N |
| $10,000 in outpatient treatment | $1,500 | You, on Plan N |
Our illustration of the 15% limiting charge. Plan G and Plan F pay excess charges in full.
Ask before you book. Ask each doctor’s office: do you accept Medicare assignment? A yes means no excess charges.
Check your state. A few states, such as New York, Ohio and Pennsylvania, ban or limit excess charges, which makes Plan N safer there.
Use Medicare’s Care Compare tool. It shows whether a doctor or clinic accepts assignment.
When Plan N Beats Plan G: Our Break-Even Math
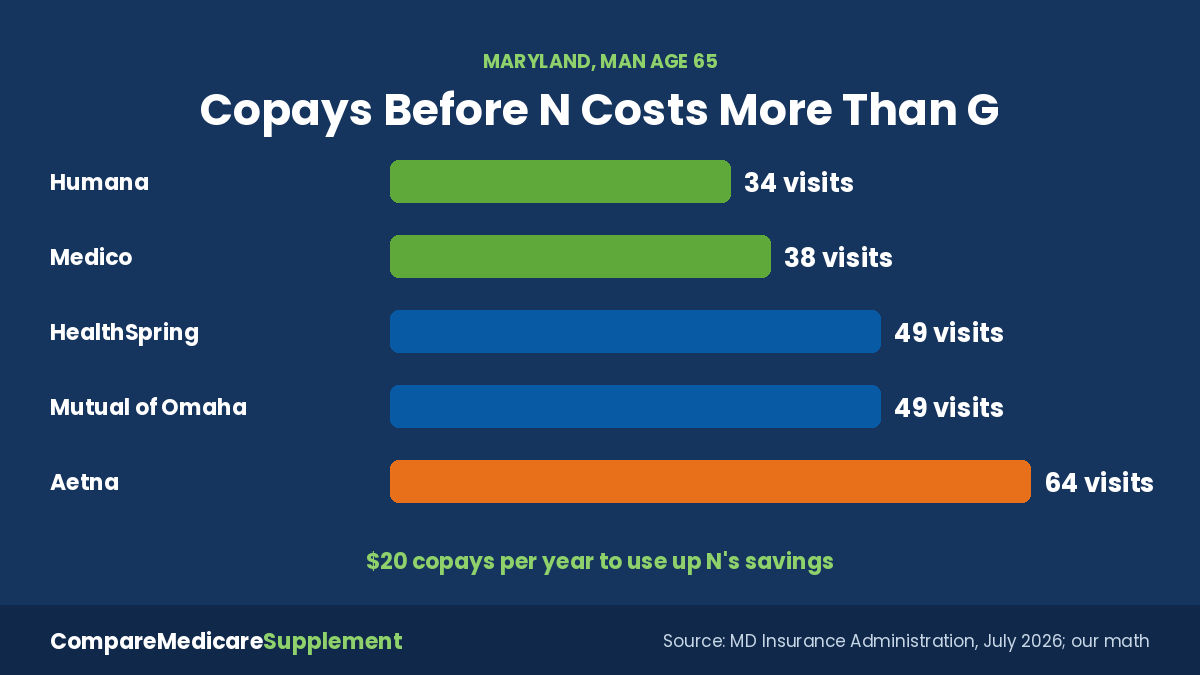
Both plans make you pay the Part B deductible, so the deductible cancels out. What matters is the yearly premium you save with N versus the copays and excess charges you might pay. We used Maryland’s official July 2026 rate guide, which lists Plan G and Plan N for each company at ages 65 and 75.
| Company (Maryland, man 65) | Plan G / month | Plan N / month | Yearly savings with N | Office copays to break even |
|---|---|---|---|---|
| Humana | $205 | $149 | $672 | 34 |
| Medico | $215 | $152 | $756 | 38 |
| HealthSpring | $241 | $160 | $972 | 49 |
| Mutual of Omaha | $278 | $197 | $972 | 49 |
| Aetna | $300 | $194 | $1,272 | 64 |
Source: Maryland Insurance Administration Medicare Supplement rate guide, rates as of July 1, 2026, male preferred or non-tobacco, age 65. Our math: savings divided by the $20 maximum office copay, rounded up. Ignores excess charges.
The gap grows with age. At 75 in the same guide, the yearly savings ranged from $636 at Humana to $1,428 at Aetna. Unless you see a doctor more than about three times a month, Plan N’s copays alone are unlikely to cost more than it saves.
Who Plan N Fits and Who Should Skip It
Good fit: healthy, few visits. You see a doctor a handful of times a year and want low premiums with full hospital protection.
Good fit: excess-charge-limited state. If your state bans or limits excess charges, Plan N’s main risk mostly goes away.
Think twice: many specialists. Frequent specialist care means more copays and more chances to meet a doctor who does not accept assignment.
Think twice: switching later. Moving from N up to G later usually means health questions, unless your state has a birthday or similar rule.
Still undecided? Our best Medicare Supplement plans 2027 page ranks plans by budget and health.
Buying Plan N for 2027
Plan N has no eligibility cutoff, unlike Plan F. Anyone with Part A and Part B can apply. Your best time is your six-month Medigap open enrollment period, when no company can turn you down or charge more for your health.
Compare the same plan across companies. Plan N benefits are identical everywhere, so price, discounts and rate history decide the pick.
Companies to compare. HealthSpring, Mutual of Omaha, Humana, Aetna and Medico all listed Plan N rates in Maryland’s 2026 guide. Availability varies by state.
Look for household discounts. Many companies discount premiums when another adult lives with you. In Maryland, Mutual of Omaha listed 12%.
See every plan letter side by side in our 2027 comparison chart.
Bottom Line
Medigap Plan N in 2027 gives you the same protection as Plan G against big hospital and doctor bills, in exchange for copays of up to $20 and $50 and the risk of excess charges. In Maryland’s official rate data, it took 34 to 64 office copays a year to wipe out Plan N’s premium savings, so it is a strong value for people who see the doctor occasionally and use doctors who accept assignment.
Price Plan N for your ZIP code
Medigap Plan N 2027 — Frequently Asked Questions
➤ Do I pay the $20 copay for my annual wellness visit on Plan N?
Medicare covers the yearly wellness visit and most preventive screenings at no cost when your doctor accepts assignment, so there is normally no coinsurance for Plan N to share. If other problems are treated at the same visit, a copay may apply to that part.
➤ Is the Plan N ER copay waived if I am kept overnight?
Only if you are formally admitted as an inpatient and the stay is covered by Part A. Overnight observation is outpatient care billed under Part B, so the copay of up to $50 may still apply.
➤ Does Plan N have an out-of-pocket maximum?
No. Plan N has no yearly cap, but its copays are small and it pays the 20% Part B coinsurance in full apart from them. Only Plans K and L have a yearly limit.
➤ Do I pay Plan N copays before meeting the Part B deductible?
No. You first pay the Part B deductible, projected at $292 for 2027. The copays start after that.
➤ How do I know if a doctor charges excess charges?
Ask whether the doctor accepts Medicare assignment. Doctors who do cannot bill excess charges. You can also check Medicare’s Care Compare tool.
➤ Does Plan N cover urgent care visits?
Yes. Plan N pays its share of covered urgent care like other Part B services. Whether a copay applies depends on how the visit is billed, so ask the clinic.
➤ Can I switch from Plan N to Plan G later?
You can apply at any time, but outside your open enrollment or a guaranteed issue right most companies can ask health questions. Some states have birthday or anniversary rules that may help.
➤ Is Plan N available everywhere?
Plan N is sold in every state that uses the standard plan letters. Massachusetts, Minnesota and Wisconsin use their own plan designs instead.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll