Medicare Advantage 2027 vs Medicare Supplement: An Honest Side-by-Side Guide
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 29, 2026
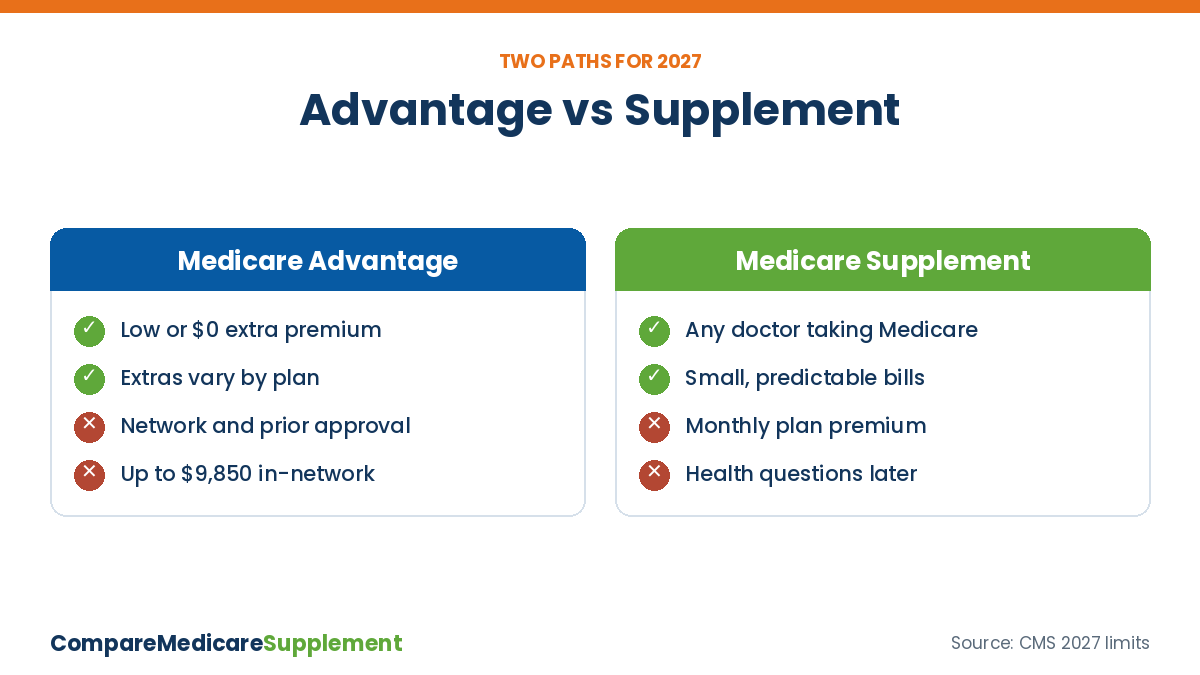
Medicare Advantage is a private plan that replaces Original Medicare, usually with a provider network, low or no extra premium and a 2027 in-network out-of-pocket limit of up to $9,850, while a Medicare Supplement keeps Original Medicare, works with any doctor that takes Medicare and costs a monthly premium. The biggest difference to weigh in 2027 is that switching from Medicare Advantage back to a Medicare Supplement later can require passing health questions.
2027 by the Numbers
$9,850
most a 2027 Medicare Advantage plan can make you pay for in-network covered care, up from $9,250 in 2026 (CMS)
$14,800
2027 combined in- and out-of-network limit for PPO plans (CMS)
12 months
trial period to leave Medicare Advantage and buy a Medigap plan with no health questions, in set situations
$2,264
worst-case covered costs for a year on the lowest-priced Plan G (premium + projected $292 deductible, NJ September 2026 chart, man 65, our math)
Every person on Medicare chooses between two paths. One is Original Medicare with a Medicare Supplement plan and a Part D drug plan. The other is a Medicare Advantage plan, also called Part C, run by a private insurer.
This site sells Medicare Supplement plans, so we want to be clear: Medicare Advantage is a good fit for some people. This guide lays out how each path works in 2027, what each one costs in a good year and a bad year, and the one rule that makes the first choice matter so much. New to Medicare? Start with Medicare basics 2027.
Compare 2027 Medicare Supplement Plans
How Medicare Advantage Works in 2027
With Medicare Advantage you still have Medicare and still pay your Part B premium, but a private company approved by Medicare pays your claims instead of the federal government. The plan must cover everything Original Medicare covers, though it sets its own copays, networks and rules.
Networks. Most plans are HMOs or PPOs. HMOs generally cover only in-network care except emergencies. PPOs pay for out-of-network care at a higher cost.
Prior authorization. Plans can require approval before certain services, such as some scans, surgeries or skilled nursing stays.
Extra benefits. Many plans include drug coverage and some dental, vision or hearing benefits that Original Medicare does not cover. What is included varies by plan and area and can change every year.
Yearly cap. Every plan has a maximum out-of-pocket limit for covered Part A and Part B services.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Side by Side: Medicare Advantage vs Medicare Supplement
| Medicare Advantage | Original Medicare + Medicare Supplement | |
|---|---|---|
| Doctors and hospitals | Plan network; out-of-network rules vary | Any provider in the U.S. that accepts Medicare |
| Monthly premium | Often low or $0 beyond Part B | Plan premium plus Part B |
| Costs when you get care | Copays and coinsurance up to the plan’s limit | Little or none, depending on the plan letter |
| Prior authorization | Common for some services | Generally not required by Original Medicare for most services |
| Drug coverage | Usually built in | Separate Part D plan |
| Dental, vision, hearing extras | Often some, varies by plan | Not included |
| Changing later | Each fall during open enrollment | Can require health questions outside protected windows |
General comparison. Individual plans and state rules differ.
What Each Path Can Cost You in a Bad Year
A healthy year looks cheap on either path. The real test is a year with a cancer diagnosis, a heart surgery or a long hospital stay.
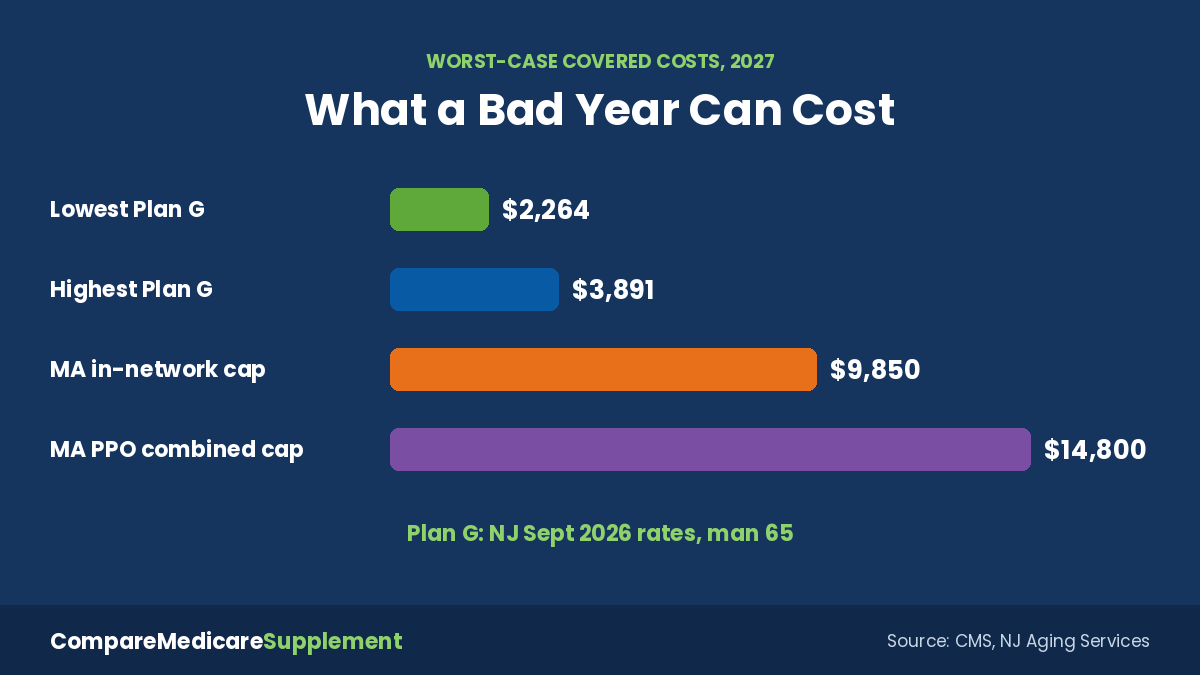
| Worst-case covered costs for 2027 | Amount | Basis |
|---|---|---|
| Medicare Advantage, in-network, $0-premium plan | Up to $9,850 | 2027 CMS in-network limit; many plans set a lower cap |
| Medicare Advantage PPO, in- and out-of-network | Up to $14,800 | 2027 CMS combined limit |
| Lowest-priced Plan G | $2,263.72 | $1,971.72 yearly premium + $292 projected Part B deductible |
| Highest-priced Plan G on the same chart | $3,890.56 | $3,598.56 yearly premium + $292 projected Part B deductible |
Our math. Plan G premiums: NJ Division of Aging Services chart, September 2026 rates, man age 65. Part B and Part D premiums apply on both paths and are left out. Drug costs are separate on both paths.
The trade-off in plain terms: Medicare Advantage usually costs less in the months you are well and can cost more in the year you are sick. A Medicare Supplement costs more every month, and in exchange your bills stay small and predictable. See what plan letters pay in our 2027 Medicare Supplement comparison chart.
The Switching Trap: Going Back to a Medicare Supplement
You can leave Medicare Advantage for Original Medicare each fall, from October 15 to December 7, or during the Medicare Advantage Open Enrollment Period from January 1 to March 31. The catch is the Medicare Supplement. In most states, once your first 6-month Medigap window has passed, an insurance company can ask health questions and turn you down or charge more, unless you have a guaranteed issue right.
Trial right at 65. If you joined Medicare Advantage when you were first eligible at 65 and leave within the first 12 months, you can buy any Medigap plan sold in your state without health questions.
Trial right after dropping Medigap. If you dropped a Medigap policy to join Medicare Advantage for the first time and leave within 12 months, you can generally get your old policy back if the company still sells it, or buy another plan.
Plan leaves or you move. If your Medicare Advantage plan stops serving your area or you move out of it, you also get a guaranteed issue right.
Timing: For these federal rights you can generally apply as early as 60 days before your Medicare Advantage coverage ends and no later than 63 days after it ends. Miss that window and health questions can apply again.
States With Extra Protections for People Leaving Medicare Advantage
A few states go further than federal law. According to a KFF review of state Medigap rules published October 2026:
| State | Extra protection |
|---|---|
| Connecticut and New York | Medigap is sold year-round to people 65 and older regardless of health |
| Maine | Stretches the Medicare Advantage trial period from 1 year to 3 years |
| Rhode Island | Medicare Advantage members 65+ get a yearly Medigap window during fall open enrollment |
| Delaware | Medicare Advantage members 65+ get two yearly windows; companies cannot deny you but may charge more and use a 6-month pre-existing condition wait |
| California | You can buy Medigap from the same company if your Medicare Advantage plan cuts benefits, raises costs or drops your provider |
Source: KFF, October 2026. Check with your state insurance department for current details.
Everywhere else, assume that leaving Medicare Advantage after your trial period means answering health questions.
How to Decide Which Path Fits You
List your doctors and hospitals. If you want any provider that takes Medicare, or you travel or split time between states, a Medicare Supplement avoids network limits.
Run your bad-year number. Ask whether a bill of up to $9,850 in one year would hurt. If it would, the fixed premium of a Medicare Supplement may be worth it.
Think about your health in 10 years. Your first 6-month Medigap window is the only time every company must accept you. If you skip it, getting in later may not be possible.
Price it out. Compare the yearly premium for Plan G or Plan N against the extra benefits and caps of plans in your area.
If you lean toward a Medicare Supplement, our best Medicare Supplement plans 2027 guide explains which plan letters most people pick and why.
Bottom Line
Medicare Advantage and Medicare Supplement plans are both legitimate ways to get Medicare in 2027. Advantage plans trade networks, prior approval and a cap of up to $9,850 for low premiums and extras, while a Medicare Supplement trades a monthly premium for freedom of choice and small, predictable bills. Whichever you pick, decide before your 6-month Medigap window closes, because coming back later can mean health questions.
Compare 2027 Medicare Supplement prices in your ZIP code
Medicare Advantage vs Medicare Supplement 2027 — Frequently Asked Questions
➤ What is the Medicare Advantage out-of-pocket maximum for 2027?
CMS set the 2027 in-network limit at $9,850, up from $9,250 in 2026. For PPO plans the combined in- and out-of-network limit is $14,800, and individual plans may set lower caps.
➤ Can I have Medicare Advantage and a Medicare Supplement at the same time?
No. A Medicare Supplement only works with Original Medicare, and it is illegal for a company to sell you one if you are staying in a Medicare Advantage plan.
➤ Do I still pay the Part B premium with Medicare Advantage?
Yes. You must keep paying your Part B premium, projected at $209.50 a month for 2027, on either path. A few Medicare Advantage plans give back part of it.
➤ Can I switch from Medicare Advantage back to Original Medicare?
Yes, during fall open enrollment from October 15 to December 7 or from January 1 to March 31. Getting a Medicare Supplement at that point may require health questions unless you have a trial right or other guaranteed issue right.
➤ What is the Medicare Advantage trial right?
If you joined Medicare Advantage when first eligible at 65, or dropped a Medigap plan to try Medicare Advantage for the first time, you can leave within 12 months and buy a Medigap plan without health questions.
➤ Is Medicare Advantage cheaper than a Medicare Supplement?
Usually in monthly premiums, often not in a year with heavy medical bills. Our math shows a worst case near $2,264 for the lowest-priced Plan G on New Jersey’s September 2026 chart versus up to $9,850 in-network on Medicare Advantage.
➤ Does a Medicare Supplement include dental and vision?
No. Medicare Supplement plans pay the gaps in Original Medicare only. Many people add a separate dental or vision policy if they want that coverage.
➤ Who might be better off with Medicare Advantage?
People who are comfortable with a local network, want built-in drug and extra benefits, and could handle the plan’s yearly cap if they had a costly year. It is worth comparing both paths before your Medigap window closes.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll