Medicare Supplement Plan G vs Plan N 2027: Our Company-by-Company Cost Test
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 31, 2026
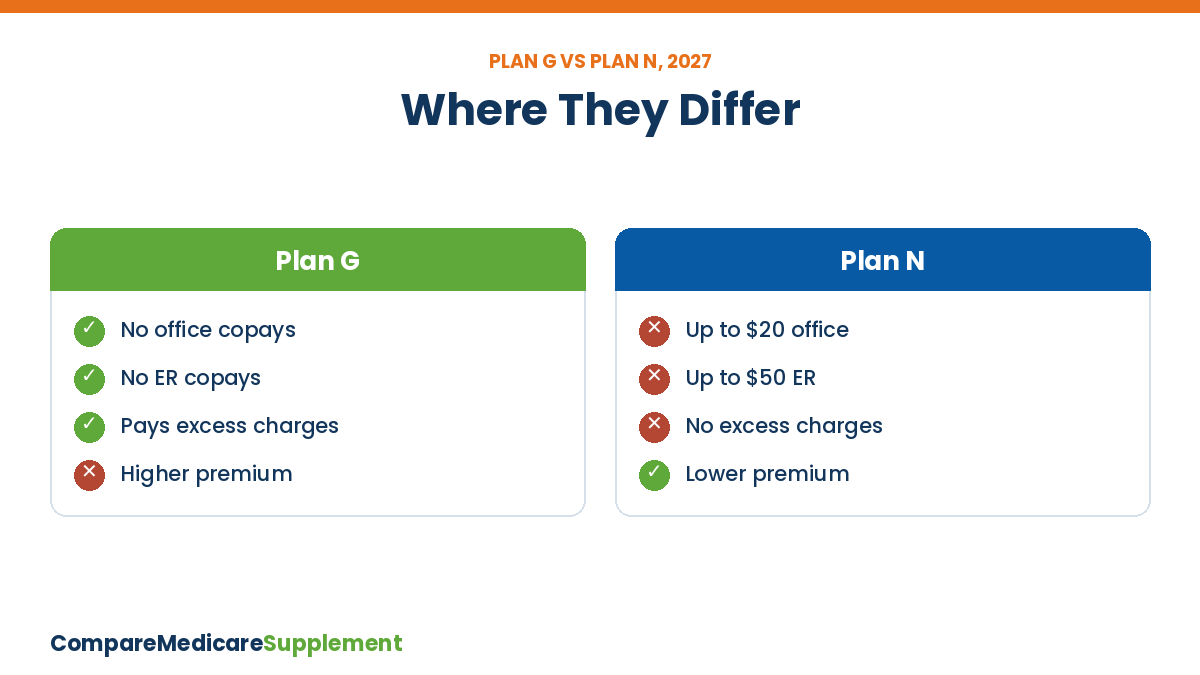
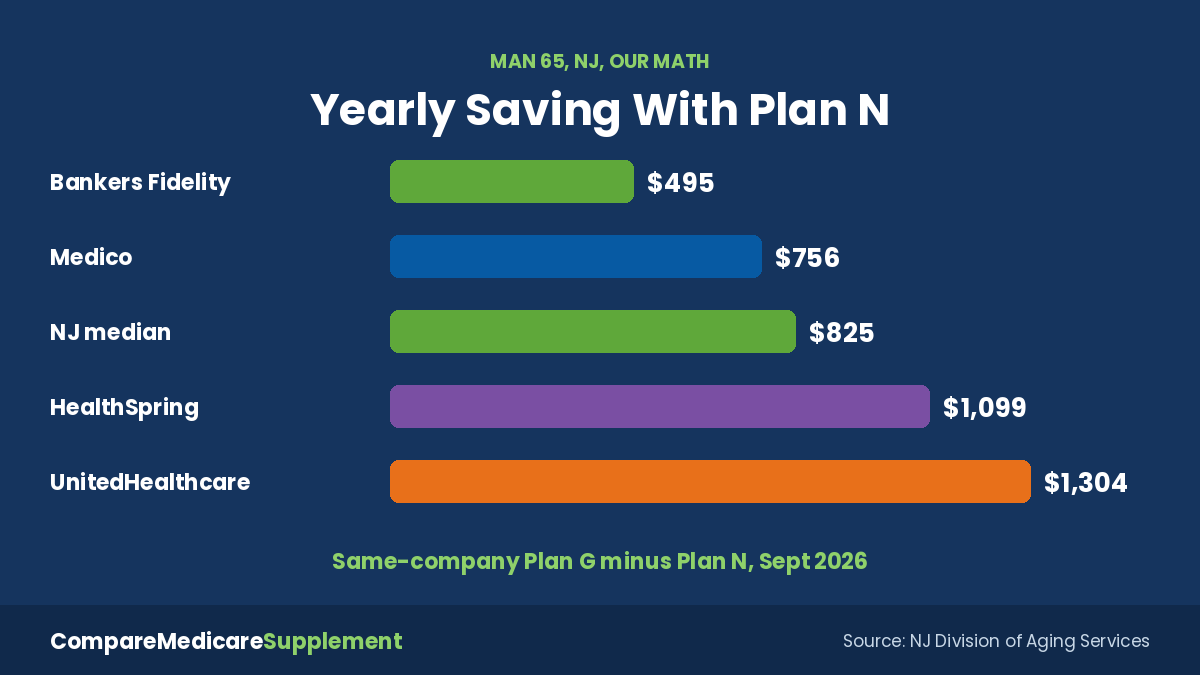
Plan G vs Plan N comes down to this: Plan N charges a lower premium but adds copays of up to $20 at the doctor and up to $50 in the ER, and it does not pay Part B excess charges. On New Jersey’s September 2026 chart, the same company’s Plan N was $41 to $109 a month cheaper than its Plan G for a 65-year-old man, which is $495 to $1,304 a year.
2027 by the Numbers
$68.79
median monthly Plan G minus Plan N gap, same company, man 65, NJ September 2026 (our math)
41
$20 office copays it takes to use up that median yearly saving (our math)
$292
projected 2027 Part B deductible, paid on both plans (Trustees)
5%
most New York doctors can charge above Medicare’s amount, versus 15% elsewhere
Plan G and Plan N are the two Medicare Supplement plans most people new to Medicare choose between. They cover the same hospital costs and both leave you the Part B deductible. The differences are small copays, excess charges and, most of all, price.
Instead of repeating the benefit chart, we ran a cost test on every New Jersey company that lists both plans, and we checked where excess charges are restricted by state law. For each plan on its own, see our Plan G 2027 guide and our Medigap Plan N page.
Compare 2027 Plan G and Plan N Rates
The Only Three Benefit Differences
| Cost | Plan G | Plan N |
|---|---|---|
| Part B deductible ($292 for 2027) | You pay | You pay |
| Office visits after the deductible | $0 | Up to $20 for some visits |
| Emergency room visits | $0 | Up to $50 if you are not admitted |
| Part B excess charges | Plan pays | You pay |
| Part A deductible, hospital and skilled nursing coinsurance | Plan pays | Plan pays |
Standardized Medigap benefits (Medicare.gov). Massachusetts, Minnesota and Wisconsin use their own plan designs.
Everything else, including the projected $1,788 Part A deductible, hospice coinsurance and 80% of emergency care abroad, is the same on both plans.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Our Test: The Plan G vs Plan N Price Gap at 19 Companies
We took every company on New Jersey’s September 2026 chart that lists both Plan G and Plan N for a 65-year-old man and subtracted one from the other. Comparing within the same company removes differences in service and rate history.
| Company, man 65, NJ | Plan G | Plan N | Yearly saving with N |
|---|---|---|---|
| Bankers Fidelity Assurance | $172.82 | $131.58 | $494.88 |
| Bankers Life (Washington National) | $164.31 | $119.90 | $532.92 |
| Medico | $207.42 | $144.45 | $755.64 |
| United World Life (Mutual of Omaha group) | $228.02 | $159.23 | $825.48 |
| HealthSpring National Health | $214.14 | $122.56 | $1,098.96 |
| Humana (Value) | $225.16 | $128.14 | $1,164.24 |
| UnitedHealthcare Ins. Co. of America | $237.23 | $128.53 | $1,304.40 |
Selected rows from our calculation across all 19 companies on the NJ Division of Aging Services male age 65 chart, September 2026 rates. Median gap: $68.79 a month, $825.48 a year.
What stands out: The gap is not a fixed number. At the narrowest company it was $41.24 a month; at the widest it was $108.70. Your decision can flip depending on which insurer you are quoted.
How Many Copays Would Erase Plan N's Savings?
We divided each company’s yearly Plan N saving by the $20 maximum office copay. The answer is the number of copay visits you would need in one year before Plan N stops saving money.
| Yearly saving with Plan N | Office visits at $20 to break even | ER visits at $50 to break even |
|---|---|---|
| $494.88 (narrowest gap) | about 25 | about 10 |
| $825.48 (median gap) | about 41 | about 17 |
| $1,304.40 (widest gap) | about 65 | about 26 |
Our math. Not every visit has a copay, and ER copays are waived if you are admitted, so real break-even counts are usually higher.
Most people do not see a doctor 25 to 65 times a year. That is why Plan N often comes out ahead on copays alone. The bigger question is excess charges.
Excess Charges: Where They Can and Can't Hit You
A doctor who accepts Medicare but not assignment can bill up to 15% above Medicare’s approved amount, called an excess charge. Plan G pays it; Plan N does not. Some states restrict excess charges on their own.
New York. State law limits most charges to 5% above the Medicare-approved amount.
Massachusetts. Doctors who take Medicare cannot bill excess charges.
Minnesota. Excess charges are barred for most services; ambulance and medical equipment are exceptions.
Ohio. Excess charges are treated as balance billing, which the state does not allow.
Outside those states, you can avoid excess charges by asking each doctor whether they accept Medicare assignment. Most do, but if you see specialists who don’t, Plan G’s protection is worth more.
Which Plan Fits Which Person
Plan N fits if: You see the doctor a handful of times a year, your doctors accept assignment, and the premium gap at your company is wide.
Plan G fits if: You have frequent specialist visits, use doctors who don’t accept assignment, or want no surprise bills at all.
Look at HD-G too if: You are healthy and can cover a larger bill; see our high deductible Plan G 2027 page.
Broker tip: Moving from Plan N up to Plan G later usually means passing health questions outside open enrollment. Moving down is generally easier. If you are torn, think about your health five years from now.
How to Compare Plan G and Plan N Quotes for 2027
Price both at the same company. This shows your true premium gap without mixing in carrier differences.
Count last year’s visits. Compare your office and ER visits with the break-even counts above.
Ask your doctors about assignment. If all of them accept it, excess charges are unlikely.
Check several insurers. Our 2027 comparison guide explains how to line quotes up.
Apply during open enrollment. In your six-month Medigap Open Enrollment Period you can buy either plan without health questions.
Bottom Line
Plan G and Plan N pay the same big bills, and the trade-off is a lower Plan N premium for small copays and possible excess charges. In our New Jersey test, the median yearly saving with Plan N would cover about 41 office copays. Price both plans at the same company, then decide based on your doctors and how often you see them.
Price Plan G and Plan N side by side in your ZIP code
Plan G vs Plan N 2027 — Frequently Asked Questions
➤ Is Plan N cheaper than Plan G?
Yes, at every New Jersey company we checked. For a 65-year-old man in September 2026, the same company’s Plan N was $41.24 to $108.70 a month cheaper.
➤ What copays does Plan N have in 2027?
Up to $20 for some office visits and up to $50 for emergency room visits that do not lead to an inpatient admission.
➤ Do both plans make me pay the Part B deductible?
Yes. The Part B deductible, $292 for 2027, is paid by you on both Plan G and Plan N.
➤ What are Part B excess charges?
Extra amounts, up to 15% above Medicare’s approved amount, that doctors who don’t accept assignment may bill. Plan G covers them; Plan N does not.
➤ Which states do not allow excess charges?
Massachusetts, Minnesota for most services and Ohio bar them, and New York limits most to 5%. Elsewhere the federal 15% limit applies.
➤ How many doctor visits make Plan G worth it?
At the median New Jersey price gap, it takes about 41 $20 office copays a year before Plan N’s savings are used up.
➤ Can I switch from Plan N to Plan G later?
You can apply, but outside open enrollment or a guaranteed issue right, most companies can ask health questions and turn you down.
➤ Do Plan G and Plan N cover the same hospital costs?
Yes. Both pay the Part A deductible, hospital coinsurance and skilled nursing coinsurance in full.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll