Compare Medicare Supplement Plans 2027
Compare Medicare Supplement Plans 2027: How to Compare Quotes the Right Way
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 29, 2026
To compare Medicare Supplement plans for 2027, choose one plan letter first, then compare that same letter from several companies on price, pricing method, rate-increase history and discounts. Coverage for a given letter is identical by law, so two Plan G quotes differ only in cost and in how the company is likely to raise that cost later.
2027 by the Numbers
20
Medicare Supplement company listings on New Jersey’s September 2026 chart
$135.57
monthly gap between the lowest and highest Plan G price on that chart (our math)
$3,050
2027 high-deductible Plan G deductible (CMS)
Comparing Medicare Supplement plans is different from comparing car or home insurance. You are not weighing better or worse coverage inside the same plan letter, because federal law fixes what each letter pays. That makes the comparison simpler than it looks, but only if you compare the right things.
This guide gives you a six-point checklist and uses New Jersey’s official September 2026 premium chart to show how far apart companies can be for the exact same plan. To see every letter’s benefits side by side, open our 2027 Medicare Supplement comparison chart.
Compare 2027 Medicare Supplement Rates in Your Area
Step One: Compare Plan Letters Before Companies
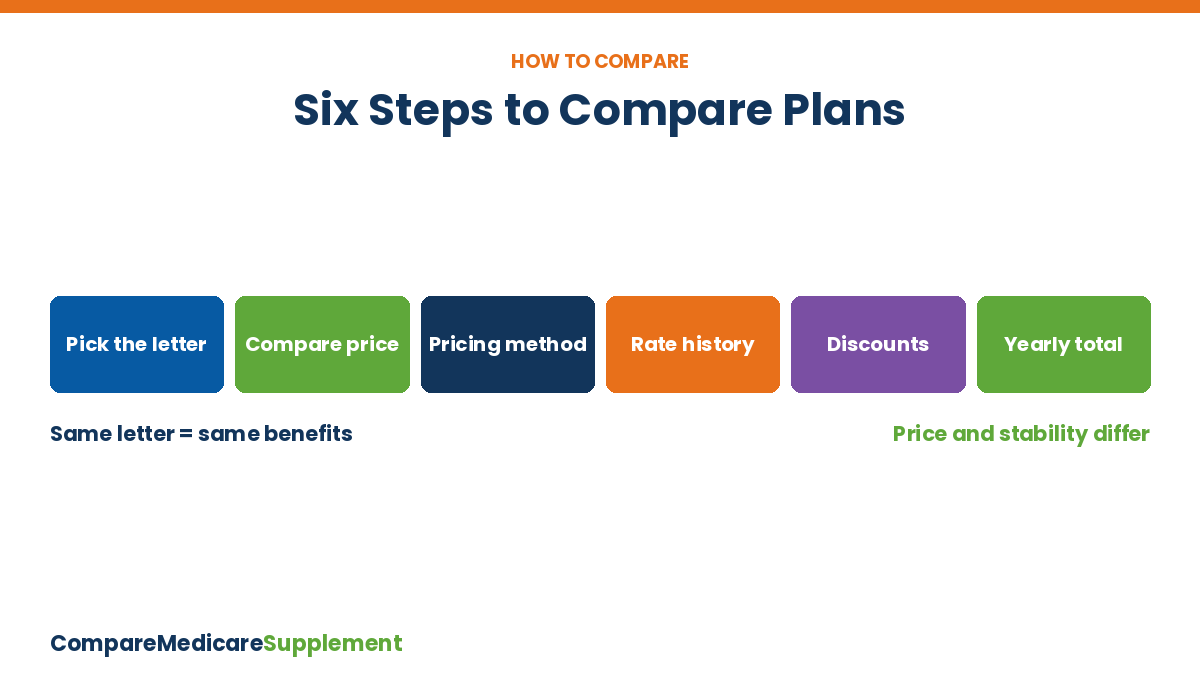
Decide which letter fits you before you collect quotes. Otherwise you end up comparing a cheap Plan N against an expensive Plan G and calling it a company comparison.
| If you want… | Compare quotes for |
|---|---|
| The most coverage available to new enrollees | Plan G |
| Lower premiums and are fine with small copays | Plan N |
| The lowest premium with full coverage after a deductible | High-deductible Plan G ($3,050 in 2027) |
| A yearly out-of-pocket cap with low premiums | Plan K ($8,360 cap) or Plan L ($4,180 cap) |
Our guide to the best Medicare Supplement plans for 2027 walks through the cost math for each of these.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Step Two: Compare Prices for the Same Plan
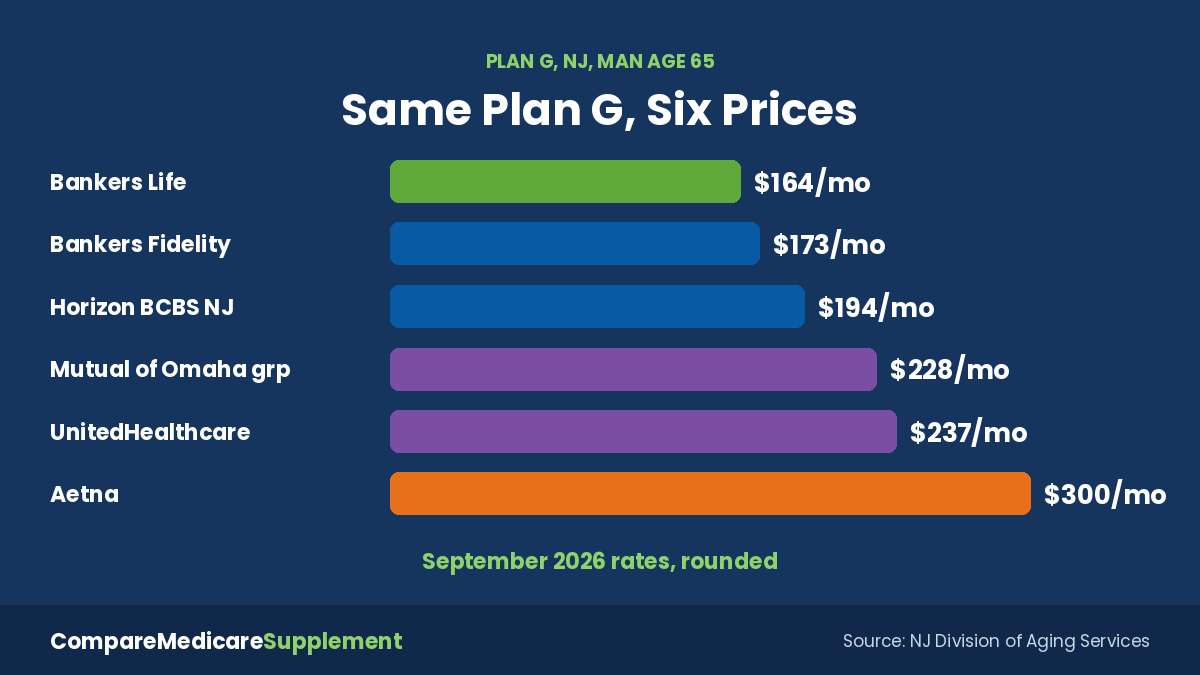
Once the letter is fixed, price is the first real difference. New Jersey’s chart for a 65-year-old man shows how wide the range is for an identical Plan G.
| Plan G company (NJ, man 65) | Monthly premium |
|---|---|
| Bankers Life (Washington National) | $164.31 |
| Bankers Fidelity Assurance Company | $172.82 |
| Horizon Blue Cross Blue Shield of N.J. | $194.32 |
| Mutual of Omaha group (United World Life) | $228.02 |
| UnitedHealthcare Insurance Co. of America | $237.23 |
| Aetna Health Insurance Co. | $299.88 |
Selected rows from the NJ Division of Aging Services chart, September 2026 rates. Your state, age and ZIP will give different prices.
Our math: The highest Plan G on that chart costs $135.57 a month more than the lowest, or $1,626.84 a year, for the same benefits.
Step Three: Compare How Each Company Prices the Plan
Attained age. The price is based on your current age and rises as you get older, on top of any general rate increases.
Issue age. The price is based on your age when you buy. It does not rise because you age, though it can still rise for inflation.
Community rated. Everyone pays the same price regardless of age. Some states require this method.
A low attained-age price at 65 can pass an issue-age price by your mid-70s. Ask each company which method it uses where you live.
Step Four: Compare Rate-Increase History
Every company raises Medicare Supplement rates over time as claims and costs grow. What differs is how often and by how much. A plan that starts cheap and rises sharply can cost more over ten years than one that started higher but rises steadily.
Ask for the last three years of increases. An agent or the company can tell you what the plan’s rate changes have been in your state.
Compare like with like. Look at the same plan letter, in the same state, for the same pricing method.
Be wary of new blocks. A brand-new plan block may start low because it has few claims yet. Ask how long the company has sold the plan in your state.
Step Five: Compare Discounts and Underwriting
Many companies offer a household discount when two people in the same home buy coverage, and some offer others. Discounts vary by company and state, so compare the final price you would pay, not the advertised rate.
Timing matters: During your six-month Medigap Open Enrollment Period, which starts when you are 65 and enrolled in Part B, a company cannot turn you down or charge more for health reasons. After that, most companies can ask health questions. Our Part B guide explains how your Part B date sets that window.
Step Six: Compare Your Total Yearly Cost
Add up a full year for each finalist: twelve months of premium, plus what you would pay out of pocket in a normal year and in a bad year. For Plan G that out-of-pocket amount is the Part B deductible, projected at $292 for 2027. For high-deductible G it can reach $3,050.
| Finalist | Premium x 12 | Normal year | Bad year |
|---|---|---|---|
| Plan G at $164.31/mo | $1,971.72 | about $2,264 | about $2,264 |
| Plan N at $119.90/mo | $1,438.80 | $1,730.80 + copays | $1,730.80 + copays + excess charges |
| High-deductible G at $50.83/mo | $609.96 | depends on care used | $3,659.96 |
Our calculation using the lowest NJ September 2026 premiums and the projected $292 Part B deductible. Normal-year figures assume you meet the Part B deductible.
Bottom Line
To compare Medicare Supplement plans for 2027, settle on a plan letter first, then compare that same letter across companies on price, pricing method, rate history and discounts. Benefits are identical, but prices for the same Plan G can differ by more than $1,600 a year, and a smart comparison now protects you for years.
Compare 2027 plans side by side for your ZIP code
Compare Medicare Supplement Plans 2027 — Frequently Asked Questions
➤ What should I compare first when shopping Medicare Supplement plans?
Compare plan letters first, because each letter’s benefits are fixed by law. Once you know you want Plan G or Plan N, compare that same letter across companies.
➤ Why do companies charge different prices for the same plan?
Each company sets its own rates based on its costs, claims experience and pricing method. The benefits are identical, so the difference is purely price and future rate behavior.
➤ What is the difference between attained-age and issue-age pricing?
Attained-age prices rise as you get older. Issue-age prices are based on your age when you buy and do not rise because of age, though both can rise for inflation.
➤ Can I compare Medicare Supplement plans online?
Yes. You can get quotes by ZIP code online or with a licensed agent, who can also tell you each company’s pricing method and recent rate increases in your state.
➤ Is the cheapest Medicare Supplement plan the best choice?
Not always. A plan that starts cheapest can raise rates faster. Compare the first-year price together with the company’s rate history and pricing method.
➤ When is the best time to compare and buy?
During your six-month Medigap Open Enrollment Period, when no company can deny you or charge more for health reasons. Outside it, most companies can use medical underwriting.
➤ Do I need to compare drug coverage too?
Yes. Medicare Supplement plans do not cover prescriptions, so compare Part D plans separately. In 2027 Part D deductibles are capped at $700 and out-of-pocket costs at $2,400.
➤ How often should I compare my Medicare Supplement plan?
Review it each year when your rate changes. If your health allows you to pass underwriting, a different company may offer the same plan for less.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll