Medicare Supplement Plans 2027: Every Plan Letter, State Guides and Companies We Compare
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 29, 2026
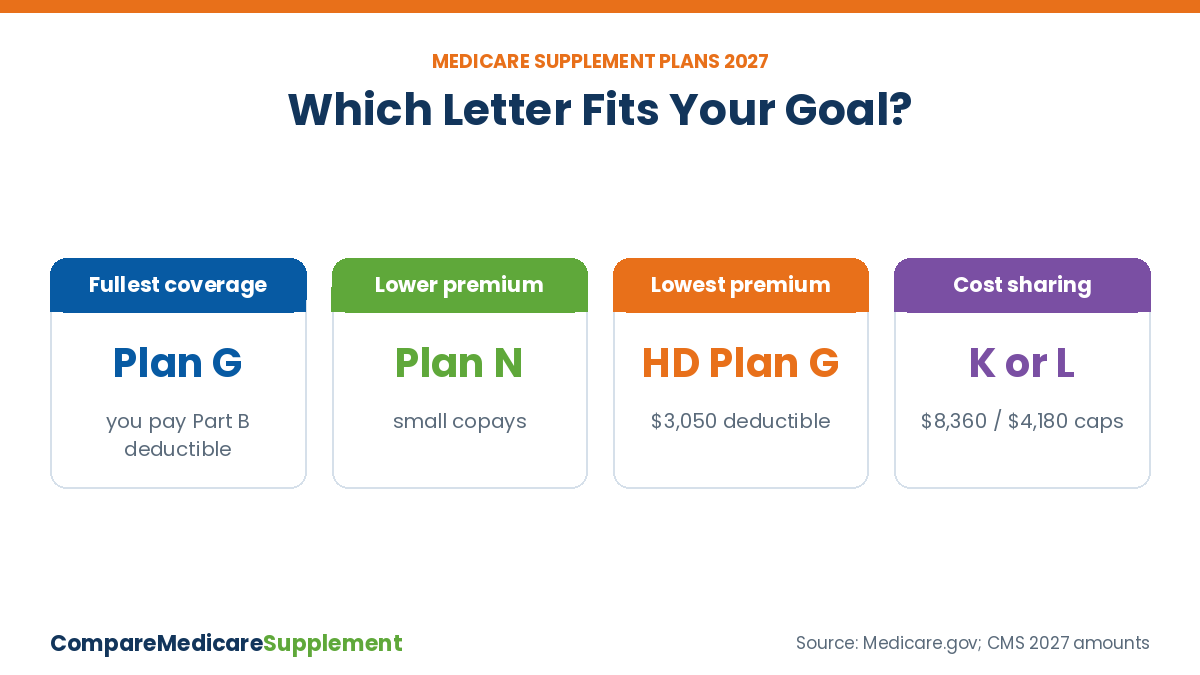
Medicare Supplement plans are 10 lettered policies (A, B, C, D, F, G, K, L, M and N), plus high-deductible versions of F and G, that pay costs Original Medicare leaves to you. Most people new to Medicare in 2027 pick Plan G, Plan N or high-deductible Plan G, then compare the same letter across companies in their state.
2027 by the Numbers
12
plan choices in most states: 10 letters plus high-deductible F and G (Medicare.gov)
9
state guides on this site, each with its own rules and companies
7 of 9
of our state guides cover a state with a yearly switching right (birthday rule or Washington’s any-time rule, KFF October 2026)
$3,050
2027 deductible for high-deductible Plan F and Plan G (CMS)
This page is the map for our whole site. Use it to find the plan letter that fits you, jump to the guide for your state, see which insurance companies we compare, and learn how buying a policy actually works.
If you already know you want the most popular plan, start with the Plan G row in the guide below. If you want every benefit in one grid, use our 2027 comparison chart. If you are brand new to the idea, our Medigap basics guide explains how these policies work with Medicare.
Compare 2027 Plan Letters and Prices
Start Here: Pick Your Path Through This Site
People land on this page with very different questions. Some are turning 65 next month. Some have had a policy for ten years and want to pay less. Some just moved. Pick the path below that sounds most like you.
Turning 65 or starting Part B. Read the plan letter guide below, then your state page. Your six-month Medigap open enrollment window is the best time to buy, because companies cannot turn you down for health reasons.
Already have a policy and want a lower price. Find your state below. Seven of our nine state guides cover a state that gives you a yearly chance to switch without health questions.
Not sure which letter you have. Look at the front page of your policy. Each letter has the same benefits at every company, so the table below tells you what it pays.
Became eligible for Medicare before 2020. You may still buy Plan F or Plan C. Our Plan F guide covers whether keeping it still makes sense.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Every Plan Letter in One Short Guide
Federal law fixes what each letter pays, so Plan N from one company pays exactly what Plan N from another company pays. The middle column shows what you would still owe for Medicare-approved care in 2027. Part A and Part B deductible amounts are projections from the 2026 Medicare Trustees Report until CMS confirms them in November.
| Plan | What you still pay in 2027 | Who it is for |
|---|---|---|
| A | Part A deductible (projected $1,788 per benefit period), Part B deductible (projected $292), skilled nursing coinsurance, excess charges | Tight budgets that want basic hospital and 20% coverage |
| B | Part B deductible, skilled nursing coinsurance, excess charges | People who want the hospital deductible covered but little else |
| C | Part B excess charges only | Only people eligible for Medicare before 2020 |
| D | Part B deductible and excess charges | Plan G shoppers in areas where most doctors accept Medicare’s rate |
| F | Nothing for Medicare-approved care | Only people eligible for Medicare before 2020 |
| G | Part B deductible only | Most new enrollees who want near-complete coverage |
| K | 50% of most costs until the $8,360 limit, plus the Part B deductible | Healthy people who want a cap at a lower premium |
| L | 25% of most costs until the $4,180 limit, plus the Part B deductible | A middle ground between K and full coverage |
| M | Half the Part A deductible, the Part B deductible, excess charges | Rarely sold; check availability |
| N | Part B deductible, copays up to $20 at some office visits and up to $50 for an ER visit without admission, excess charges | People who see doctors a few times a year and want a lower premium |
| High-deductible F | First $3,050 of covered costs, then nothing | Only people eligible for Medicare before 2020 |
| High-deductible G | First $3,050 of covered costs, then the same as Plan G | Low premium seekers who can cover a bad year from savings |
Plan K and L limits and the $3,050 deductible are final 2027 CMS figures. Massachusetts, Minnesota and Wisconsin use their own plan designs.
Quick read: If two letters leave you the same costs, the cheaper one is the better buy. Plan D and Plan G differ only by Part B excess charges, which many doctors never bill.
Which Letters You Can Buy Depends on When You Got Medicare
A 2015 federal law, known as MACRA, stopped the sale of plans that pay the Part B deductible to anyone newly eligible for Medicare on or after January 1, 2020. That is why Plan F, high-deductible Plan F and Plan C are missing from many quotes.
| Your situation | Letters you can apply for |
|---|---|
| Eligible for Medicare before January 1, 2020 | A, B, C, D, F, G, K, L, M, N and both high-deductible plans |
| Eligible on or after January 1, 2020 | A, B, D, G, K, L, M, N and high-deductible G |
| Using a federal guaranteed issue right, eligible before 2020 | A, B, C, F, K and L |
| Using a federal guaranteed issue right, eligible after 2020 | A, B, D, G, K and L |
Guaranteed issue substitutions: Plans D and G replace C and F for people newly eligible after 2020 (NAIC MACRA guidance). Some states add more rights.
Eligible means the date you could first get Medicare, not the date you signed up. Someone who turned 65 in 2019 but kept job coverage until 2027 can still buy Plan F.
Find Your State's Medicare Supplement Guide
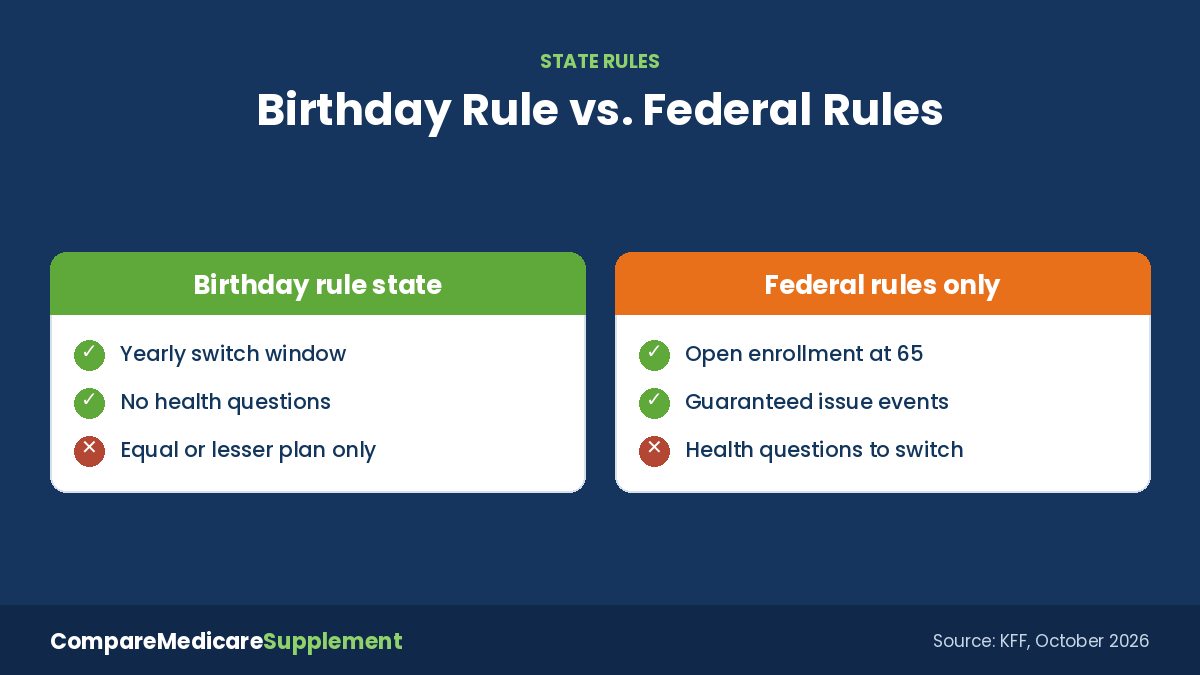
Your state decides when you can switch plans and whether people under 65 can buy a policy. Each of our state guides covers its own switching rules, the companies that file plans there and real price ranges where the state publishes them.
| State guide | Yearly switching right |
|---|---|
| California | Birthday rule |
| Georgia | None listed; switching usually means health questions |
| Kentucky | Birthday rule |
| Nevada | Birthday rule |
| North Carolina | None listed; switching usually means health questions |
| Oklahoma | Birthday rule |
| Oregon | Birthday rule |
| Virginia | Birthday rule |
| Washington | Switch to equal or lesser coverage any time, with less than a 90-day gap |
Source: KFF review of state Medigap rules, October 2026. Birthday rule windows run 30 to 63 days depending on the state; see each guide for exact dates.
Moving soon? You can usually keep a standard Medigap policy when you move to another state, as long as you stay in Original Medicare. Your premium may change to the new area’s rate.
Medicare Supplement Companies We Compare
We compare the companies below when they sell in your state. Not every company sells every letter everywhere, and prices for the same letter can differ by hundreds of dollars a year, so we always show several quotes side by side.
| Company | What to know |
|---|---|
| HealthSpring | The new name for Cigna’s Medicare Supplement plans |
| Mutual of Omaha | Long-time Medicare Supplement seller in most states |
| Aetna | Sells Medicare Supplement plans in many states |
| Humana | Sells Medicare Supplement plans alongside its other Medicare products |
| Medico and Wellabe | Wellabe is the newer brand for a group of companies that includes Medico Insurance Company |
| Blue Cross Blue Shield | Your state’s own Blue plan |
Availability, plan letters and household discounts vary by state and ZIP code.
Our guide to the best plans for 2027 explains how we weigh price, pricing method and rate history when we line these companies up.
How Buying a Medicare Supplement Plan Works
Enroll in Part A and Part B first. A supplement only works with Original Medicare. You cannot use one with a Medicare Advantage plan.
Choose a letter. Use the plan guide above to decide between full coverage, a lower premium with small copays, or a high deductible.
Get quotes for that letter. Ask for the same letter from several companies, with any household or online discounts applied.
Apply at the right time. During your six-month open enrollment, or with a guaranteed issue or state switching right, the company must accept you. Outside those windows it can ask health questions.
Add a Part D drug plan. Supplements sold today do not cover prescriptions, so most people pair one with a separate Part D plan.
Use the 30-day free look if you switch. When you replace one policy with another, you get 30 days to decide, and you may pay both premiums for that one month.
Bottom Line
Pick the letter that matches how you use care, check your state’s guide for switching rules and local companies, then compare that same letter from several companies before you apply. The coverage is identical; the price and the timing are what you control.
Check which plan letters are sold in your ZIP code
Medicare Supplement Plans — Frequently Asked Questions
➤ Why are Medicare Supplement plans named with letters?
Federal law standardizes the plans, and each letter stands for a fixed set of benefits. The letters make it easy to compare companies, because a Plan G from any company pays the same costs.
➤ Who can still buy Plan C?
Only people who were eligible for Medicare before January 1, 2020. The same rule applies to Plan F and high-deductible Plan F.
➤ Which plan letter has the lowest premium?
High-deductible Plan G and Plan K are usually the cheapest monthly choices for new enrollees, because you pay more of the cost when you use care. Prices still vary by company, age and ZIP code.
➤ Does every state sell all of the plan letters?
No. Companies do not have to sell every letter, and Plan M is hard to find in many areas. Massachusetts, Minnesota and Wisconsin use their own plan designs instead of the letters.
➤ What is the difference between Plan K and Plan L?
Plan K pays 50% of most costs and caps your 2027 spending at $8,360. Plan L pays 75% and caps your spending at $4,180, for a higher premium.
➤ Can I keep my Medicare Supplement plan if I move to another state?
Usually yes, as long as you stay in Original Medicare and keep paying the premium. Your rate may change based on your new address, and Medicare SELECT policies have their own rules.
➤ Can I have two Medicare Supplement plans at once?
No. It is illegal for a company to sell you a second policy if it knows you already have one, unless you put in writing that you will cancel the first.
➤ Which companies sell Medicare Supplement plans in my state?
It depends on your ZIP code. Our state guides list the companies that file plans there, and our quote tool shows the ones selling at your address.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll