Connecticut Medicare Supplement Plans 2027: Year-Round Acceptance, One Price at Every Age and the State’s Rate Chart
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 18, 2026
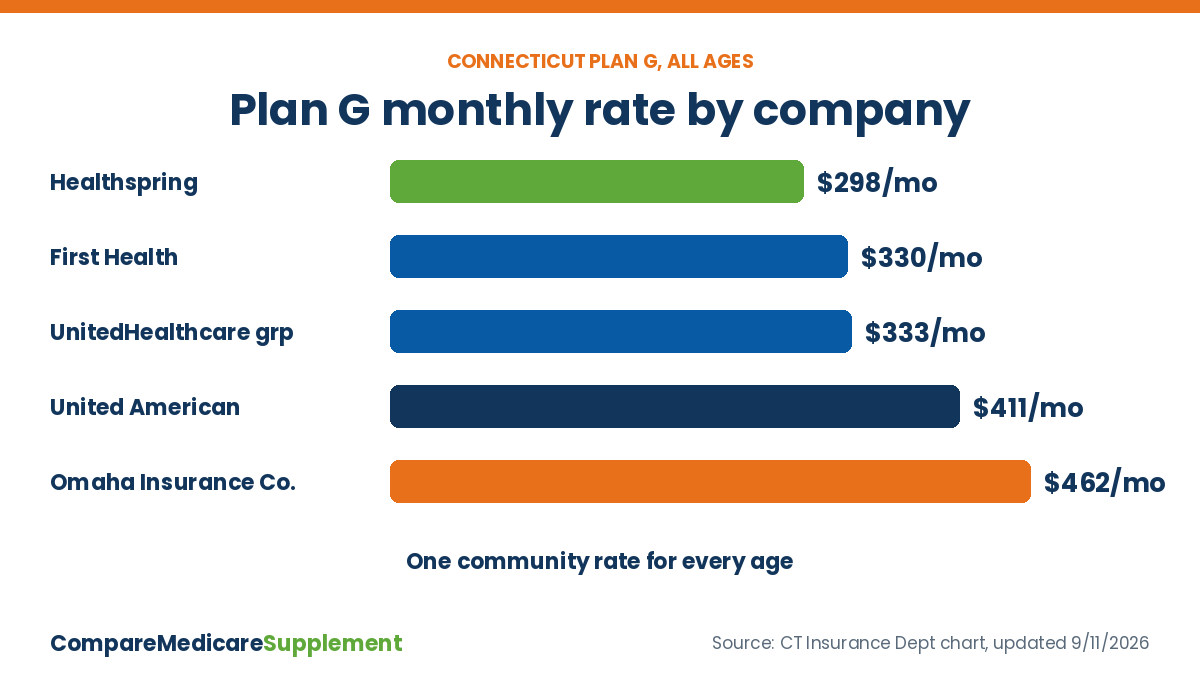
Connecticut Medicare Supplement plans for 2027 can be bought any time of year with no health questions, and each company charges one community rate regardless of age, so a 65-year-old and an 85-year-old pay the same. On the Connecticut Insurance Department’s September 2026 chart, Plan G runs from $297.75 to $461.94 a month depending on the company.
2027 by the Numbers
$297.75-$461.94
Plan G monthly range on the CT Insurance Department chart updated 9/11/2026
$1,970.28
yearly difference between the cheapest and priciest Plan G on that chart (our math)
1 of 4
states that require insurers to accept Medigap applicants 65+ at least yearly, regardless of health (KFF)
Connecticut is one of the few states where the usual Medigap warning, buy in your first six months or risk being turned down, does not apply. State law requires guaranteed issue at all times and community rating, so price depends on the company and the plan, not on your age or health.
That changes how you shop. Below we read the state’s own rate chart, compare companies, measure the Plan G to Plan N gap at each one, and test high-deductible Plan G against the cheapest regular G. Guaranteed issue works the same way in our neighbor New York Medicare Supplement plans 2027 guide.
Compare Connecticut 2027 Medigap Rates
Connecticut Rules That Change How You Shop
Guaranteed issue at all times. Connecticut requires Medigap insurers to accept applicants year-round regardless of medical condition. KFF lists Connecticut with Maine, Massachusetts and New York as the only states with continuous or annual guaranteed issue for people 65 and older.
Community rating. Connecticut is one of nine states requiring community rating for people 65 and older (KFF). Premiums cannot vary by age, and the state chart shows one rate per plan per company.
Under 65 on Medicare. Every company must offer Plan A to disabled beneficiaries, per the state rate chart. Plan C remains only for disabled people eligible for Medicare before January 1, 2020.
Provider charges. Connecticut General Statutes section 17b-552 bars health care providers from charging Medicare beneficiaries more than the federal amount for covered services, with civil penalties. Confirm with any provider who does not take assignment.
Because you can switch whenever a better rate appears, there is no birthday rule to watch and no reason to accept a large renewal increase without checking other companies.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Plan G, N and High-Deductible G Rates by Company
These monthly rates come from the Connecticut Insurance Department’s chart of standardized plans, updated September 11, 2026. Most are electronic-payment rates, and the effective date varies by company.
| Company | Plan G | Plan N | HD Plan G | Effective |
|---|---|---|---|---|
| Healthspring (formerly Cigna National) | $297.75 | $194.39 | $84.80 | 8/1/2026 |
| First Health Life & Health | $330.03 | $174.43 | not listed | 3/1/2026 |
| UnitedHealthcare group plan | $333.00 | $247.00 | not listed | 6/1/2026 |
| Medco Containment (formerly Cigna Health & Life) | $363.42 | $239.74 | not listed | 12/1/2026 |
| United American | $411.00 | $242.00 | $48.00 | 1/1/2026 |
| Washington National | $430.19 | not matched | $66.53 | 1/1/2027 |
| Omaha Insurance Company | $461.94 | $317.11 | $59.27 | 7/1/2026 |
Source: Connecticut Insurance Department, Monthly Medicare Supplement Rates for Standardized Plans, updated 9/11/2026. The UnitedHealthcare plan requires a group membership fee. Rows we could not match to a plan column with confidence are left out; check the chart or a quote.
Our Math: What Company Choice and Letter Choice Are Worth
With one price for every age, Connecticut’s chart makes clean comparisons. Picking Healthspring’s Plan G over Omaha Insurance Company’s saves $164.19 a month, or $1,970.28 a year, for identical benefits. The table below shows what dropping from Plan G to Plan N saves at the same company.
| Company | Plan G minus Plan N, monthly | Yearly saving with N |
|---|---|---|
| UnitedHealthcare group plan | $86.00 | $1,032.00 |
| Healthspring | $103.36 | $1,240.32 |
| Medco Containment | $123.68 | $1,484.16 |
| Omaha Insurance Company | $144.83 | $1,737.96 |
| First Health | $155.60 | $1,867.20 |
| United American | $169.00 | $2,028.00 |
Our calculation from the CT chart. Plan N adds copays of up to $20 per office visit and up to $50 per ER visit and does not pay the Part B deductible or excess charges.
Nutmeg State note: Plan N’s savings here are larger than in many age-rated states, because community-rated Plan G starts high. Our Plan G vs Plan N comparison shows how many visits it takes to erase the gap.
High-Deductible Plan G: Connecticut's Hidden Bargain
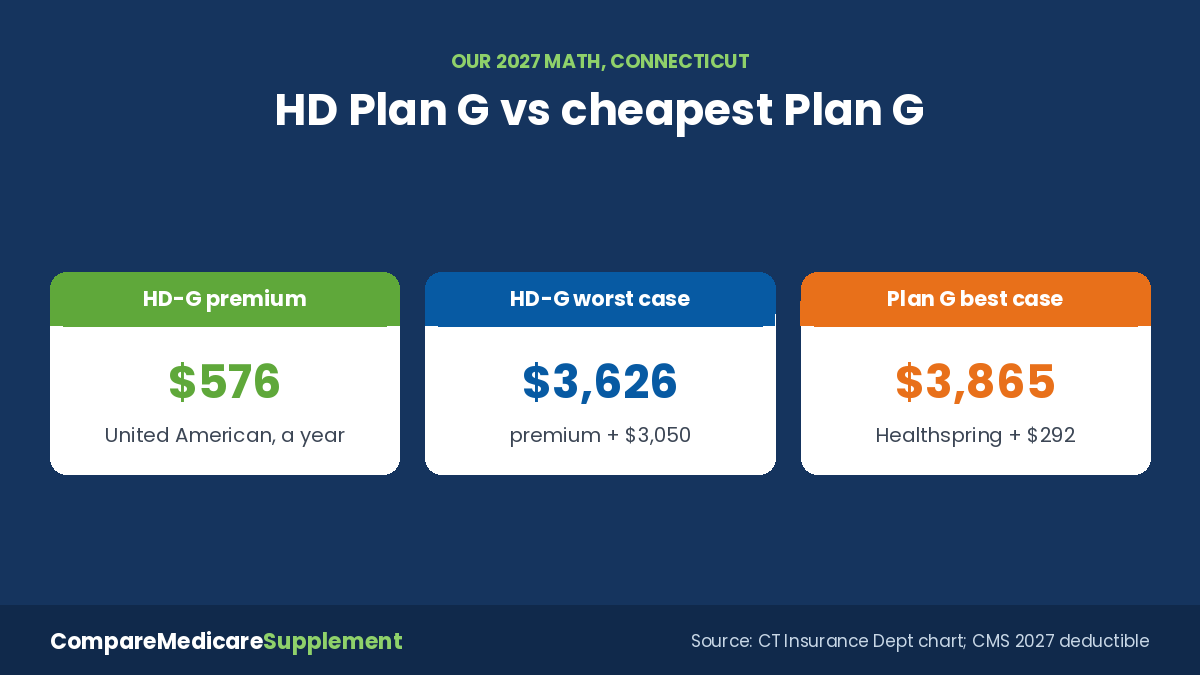
High-deductible Plan G pays nothing until you reach the 2027 deductible of $3,050, which includes the Part B deductible, then pays like Plan G. We compared its worst possible year with the best possible year on the cheapest regular Plan G.
| 2027 scenario | United American HD Plan G | Healthspring Plan G |
|---|---|---|
| Yearly premium | $576.00 | $3,573.00 |
| Most you pay for covered care | $3,050.00 | $292.00 (2027 Part B deductible) |
| Worst-case total | $3,626.00 | $3,865.00 |
Our math from the CT chart (United American HD-G $48.00 and Healthspring Plan G $297.75 monthly) and the 2027 CMS high-deductible amount. Excludes the Part B premium.
Even if you hit the full deductible, the high-deductible plan comes out $239 ahead of the lowest-priced regular Plan G on this chart, and in a light year it saves thousands. The catch is cash flow: you need $3,050 on hand. Details are on our high-deductible Plan G 2027 page.
Rate Changes Coming for 2027
Connecticut reviews Medigap rate requests and holds public hearings on some of them. On September 1, 2026, the Insurance Department heard Anthem Blue Cross and Blue Shield’s request covering its Connecticut Medigap policies, which sought 5.20% for modernized Plan G, 13.00% for Plan N and 19.90% for high-deductible Plan F. The department’s chart lists an Anthem approval dated September 3, 2026 with rates effective January 1, 2027.
Read your renewal letter. Note the new premium and effective date.
Compare it with the state chart. If another company charges less for the same letter, you can switch without health questions.
Line up the dates. Start the new policy before canceling the old one so you are never uninsured.
For national context on 2027 increases, see our Medicare Supplement rate increases 2027 report.
Free Help and Next Steps in Connecticut
Connecticut’s State Health Insurance Assistance Program is called CHOICES, run by the Department of Aging and Disability Services. Counselors give free, unbiased Medicare help and can walk you through the state rate chart.
Turning 65. Enroll in Part B, then pick a letter. You can buy a supplement immediately or later, but buying when Part B starts avoids any gap.
Leaving Medicare Advantage. Connecticut’s guaranteed issue means you can buy a supplement after you leave, without the 63-day federal deadline being your only route.
Already covered and paying too much. Price the same letter at the lowest-cost companies on the chart; switching is open all year.
Bottom Line
Connecticut Medicare Supplement plans carry two protections most states lack: guaranteed acceptance all year and a single price at every age. With Plan G ranging from $297.75 to $461.94 a month on the state’s September 2026 chart, the company you pick matters more than your timing, and high-deductible Plan G deserves a close look.
See 2027 Connecticut Plan G and N prices from several companies
Connecticut Medicare Supplement Plans 2027 — Frequently Asked Questions
➤ Can I buy a Medicare Supplement plan any time in Connecticut?
Yes. Connecticut requires guaranteed issue at all times, so insurers must accept you year-round regardless of health.
➤ Do Connecticut Medigap premiums go up with age?
No. Connecticut requires community rating, so a company charges the same premium for a plan whether you are 65 or 90. Premiums can still rise for everyone through approved rate increases.
➤ What is the cheapest Plan G in Connecticut?
On the Insurance Department chart updated September 11, 2026, Healthspring listed the lowest Plan G at $297.75 a month.
➤ Why do Connecticut Plan G rates look higher than other states?
Community rating and year-round guaranteed issue spread costs across all ages and health levels, so starting rates at 65 are higher than in states that price by age.
➤ Can I switch Medigap companies in Connecticut without health questions?
Yes. Because guaranteed issue applies at all times, you can change plans or companies whenever you find a better rate.
➤ Can people under 65 buy a supplement in Connecticut?
Yes. All companies must offer Plan A to Medicare beneficiaries under 65 with a disability, and companies that sell certain other letters must make those available too.
➤ Who reviews Medigap rate increases in Connecticut?
The Connecticut Insurance Department reviews rate filings and has held public hearings, such as the September 1, 2026 hearing on Anthem’s Medigap request.
➤ Where can I get free Medicare counseling in Connecticut?
CHOICES, the state’s SHIP program run by the Department of Aging and Disability Services, offers free counseling.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll