Medicare Supplement Plan C 2027: Who Can Still Buy It and What It Costs Next to F and G
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated November 5, 2026
Medicare Supplement Plan C in 2027 can only be bought by people who were eligible for Medicare before January 1, 2020, and it pays every Medicare gap except Part B excess charges. That includes the Part B deductible, $292 for 2027, which newer Medigap plans such as Plan G are not allowed to cover.
2027 by the Numbers
Jan 1, 2020
eligibility cutoff: Plan C is closed to anyone newer to Medicare (federal law)
$298.56
Plan C monthly, age 73+, Blue Cross Blue Shield of Arizona 2026 Senior Security, BlueValue rate
$1,697
yearly amount Plan C came out ahead of that company’s Plan G in our math, before any excess charges
18 of 51
Pennsylvania insurers offering Plan C in our count of the state’s October 2026 list
Plan C is easy to confuse with Medicare Part C, which is Medicare Advantage. They are unrelated. Medicare Supplement Plan C is a standardized Medigap policy that works with Original Medicare, and since 2020 it has been sold only to people who reached Medicare eligibility before that year.
Because the pool of buyers is shrinking, Plan C pricing varies more than most letters. Below we compare one carrier’s published 2026 rates for Plans C, F and G and work out what each costs once the 2027 Part B deductible is added. For the current plans most new enrollees choose, see our Medicare Supplement Plan G 2027 guide.
Check 2027 Plan C and Plan G Prices
Who Is Allowed to Buy Plan C in 2027
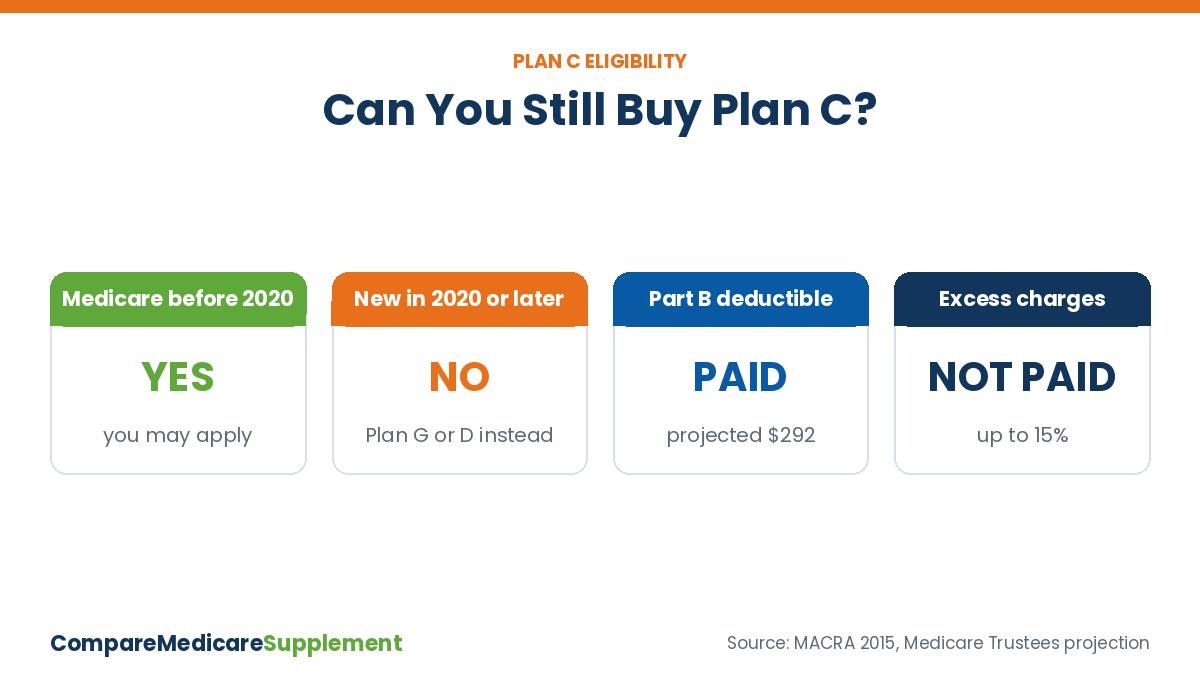
The Medicare Access and CHIP Reauthorization Act of 2015 (MACRA) barred Medigap plans that pay the Part B deductible from being sold to people newly eligible for Medicare on or after January 1, 2020. That rule closed Plan C, Plan F and high-deductible Plan F to new enrollees.
Can buy Plan C. Anyone who turned 65 before January 1, 2020, and anyone who qualified for Medicare earlier through disability, ALS or kidney failure, even if they never bought a Medigap policy.
Cannot buy Plan C. Anyone whose first Medicare eligibility date is January 1, 2020 or later. That includes everyone turning 65 in 2027.
Already have Plan C. You can keep it for life as long as you pay the premium. The policy is guaranteed renewable.
Age shortcut: If you were born before January 1, 1955 and became entitled to Medicare at 65, you were eligible before 2020 and can still apply for Plan C, subject to the insurer’s health questions outside your open enrollment or a guaranteed issue right.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
What Plan C Covers With 2027 Medicare Costs
| Medicare gap (projected 2027) | Plan C | Plan F | Plan G |
|---|---|---|---|
| Part A deductible ($1,788 per benefit period) | Pays | Pays | Pays |
| Part A hospital and hospice coinsurance | Pays | Pays | Pays |
| Skilled nursing coinsurance, days 21-100 | Pays | Pays | Pays |
| Part B deductible ($292) | Pays | Pays | You pay |
| Part B 20% coinsurance | Pays | Pays | Pays |
| Part B excess charges (up to 15%) | You pay | Pays | Pays |
| Foreign travel emergency care | 80% up to plan limits | 80% up to plan limits | 80% up to plan limits |
2027 Part A and Part B deductibles are Medicare Trustees projections; CMS announces final amounts each fall. Foreign travel benefits have a $250 deductible and a $50,000 lifetime maximum.
Real Plan C Prices: One Carrier's 2026 Rate Sheet
Blue Cross Blue Shield of Arizona publishes its 2026 Medicare Supplement rates by plan and age. Its Senior Security product sells Plans A, C, D, F, G and N, so it shows Plan C next to F and G at the same company. Since nearly everyone allowed to buy Plan C is now in their 70s, the 73-and-older band matters most.
| Senior Security, non-tobacco, monthly | Plan C | Plan F | Plan G | Plan N |
|---|---|---|---|---|
| Age 72, BlueValue rate | $247.80 | $401.64 | $345.01 | $287.97 |
| Age 73+, BlueValue rate | $298.56 | $483.90 | $415.67 | $346.95 |
| Age 73+, Standard (underwritten) rate | $484.70 | $774.24 | $671.74 | $560.07 |
Source: Blue Cross Blue Shield of Arizona 2026 Medicare Supplement monthly rate sheet. BlueValue rates are discounted for people with guaranteed issue rights, in open enrollment or who meet the carrier’s underwriting criteria. Rates elsewhere differ.
Plan C costing less than Plan G at the same company is unusual and shows how much closed-plan pricing can vary. Never assume the pattern holds in your state; ask for all three letters from each company you quote.
Our Math: Plan C vs Plan F vs Plan G for 2027
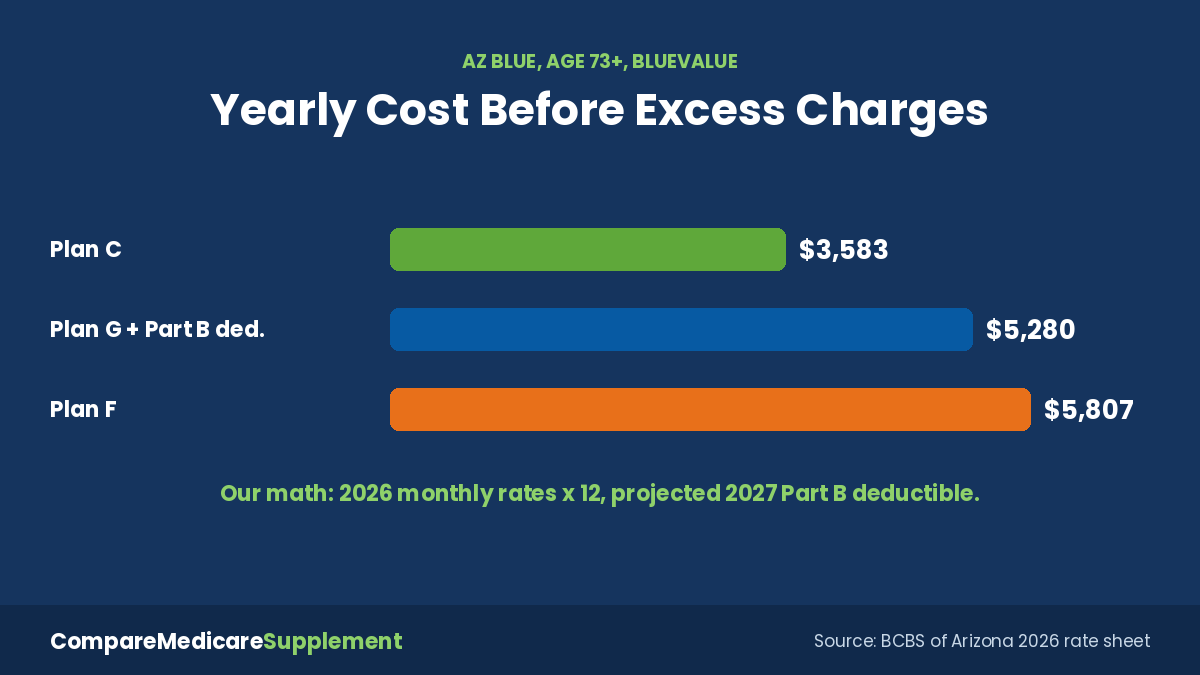
Using the age 73+ BlueValue rates above and the projected $292 Part B deductible, here is what each plan costs for a year in which you use at least $292 of Part B care. We left out excess charges, which only Plan F and Plan G pay.
| Plan (AZ, age 73+) | Yearly premium | Part B deductible you pay | Total before excess charges |
|---|---|---|---|
| Plan C | $3,582.72 | $0 | $3,582.72 |
| Plan G | $4,988.04 | $292 | $5,280.04 |
| Plan F | $5,806.80 | $0 | $5,806.80 |
Our calculation: monthly rate x 12, plus the projected 2027 Part B deductible where the plan does not pay it.
Plan C vs Plan G. Plan C came out $1,697.32 ahead for the year at this carrier, before any excess charges.
Plan C vs Plan F. Plan F cost $2,224.08 more per year, and its only extra benefit over Plan C is excess-charge coverage.
What that means. Paying Plan F’s extra premium only makes sense if you expect more than about $2,224 a year in excess charges from doctors who do not accept Medicare assignment.
The Excess-Charge Question
Excess charges are the one hole in Plan C. A doctor who does not accept Medicare assignment can bill up to 15% above the Medicare-approved amount, and Plan C leaves that to you. A $1,000 approved specialist bill could carry up to $150 extra.
Ask your doctors one question. Do you accept Medicare assignment? Most do, and with them excess charges never apply.
Check your state. Several states, including Connecticut, Massachusetts, Minnesota, New York, Ohio, Pennsylvania, Rhode Island and Vermont, limit or ban Part B excess charges, which makes Plan F’s extra benefit worth little there.
Do the math. Compare the yearly gap between Plan C and Plan F premiums with the excess charges you have actually paid in recent years.
If you are weighing Plan F, our rewritten Medicare Supplement Plan F page covers its 2027 pricing in detail.
Buying, Keeping or Leaving Plan C
Fewer companies sell it. Our count of Pennsylvania’s October 2026 available-plans list found 18 of 51 insurers offering Plan C, compared with 48 offering Plan G. See our Pennsylvania 2027 page.
Health questions usually apply. Outside your Medigap open enrollment or a guaranteed issue situation, insurers can review your health before selling Plan C.
Watch closed-block increases. With no new 65-year-olds entering, Plan C pools age over time. Review your renewal letters; our 2027 rate increase guide explains how filings work.
Moving to Plan G. Going from Plan C to Plan G adds the Part B deductible to your costs but adds excess-charge coverage. Only switch after the new policy is approved.
Bottom Line
Plan C is still open to anyone first eligible for Medicare before 2020 and pays every gap except excess charges, including the projected $292 Part B deductible in 2027. At Blue Cross Blue Shield of Arizona’s 2026 age 73+ rates, it beat that carrier’s Plan G by about $1,697 a year in our math, so it is worth quoting next to F and G if you qualify.
Compare Plan C, F and G rates in your ZIP code
Medicare Supplement Plan C 2027 — Frequently Asked Questions
➤ Is Medicare Supplement Plan C the same as Medicare Part C?
No. Medicare Part C is Medicare Advantage, a private plan that replaces Original Medicare. Medicare Supplement Plan C is a Medigap policy that pays costs left over by Original Medicare.
➤ Can I buy Plan C if I turn 65 in 2027?
No. Federal law limits Plan C to people who were eligible for Medicare before January 1, 2020. New 2027 enrollees can choose Plan G or Plan D instead.
➤ Does Plan C pay the Part B deductible in 2027?
Yes. Plan C pays the Part B deductible, $292 for 2027, along with the Part A deductible and Medicare coinsurance.
➤ What does Plan C not cover?
It does not pay Part B excess charges, which are amounts up to 15% above Medicare’s approved rate billed by doctors who do not accept assignment. It also does not cover dental, vision, hearing or prescription drugs.
➤ Is there a high-deductible Plan C?
No. The high-deductible option exists only for Plans F, G and J, with a $3,050 deductible in 2027 set by CMS.
➤ Can I keep my Plan C if I move to another state?
Yes. Medigap policies are guaranteed renewable, so you can keep Plan C after a move, though your premium may change to the new area’s rate.
➤ I got Medicare through disability in 2018. Can I buy Plan C?
Yes, because your Medicare eligibility began before 2020. Whether a company will sell it to you under 65 depends on your state’s rules for disabled enrollees.
➤ Is Plan C cheaper than Plan F?
Usually, because it skips excess-charge coverage. At Blue Cross Blue Shield of Arizona’s 2026 age 73+ BlueValue rates, Plan C was $185.34 a month less than Plan F.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll