Medicare Basics 2027: The Four Parts, Who Qualifies and When to Enroll
Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 29, 2026
Medicare basics for 2027: Medicare is federal health insurance for people 65 and older and some younger people with disabilities, split into Part A (hospital), Part B (medical), Part C (Medicare Advantage) and Part D (drugs). Most people sign up during a 7-month window around their 65th birthday, and a Medicare Supplement plan can be added to Parts A and B to pay the costs they leave behind.
2027 by the Numbers
7 months
Initial Enrollment Period: 3 months before your 65th birthday month, that month and 3 after (Medicare.gov)
$209.50
projected 2027 Part B monthly premium (Medicare Trustees; CMS sets the final figure in November)
$2,806
projected 2027 Part B premium plus deductible for a full year, before any Medigap plan (our math)
10%
added to the Part B premium for each full year you go without it when you should have had it, for life
Medicare can feel like alphabet soup the first time you look at it. The good news is that the structure is simple once you see how the pieces fit. There are four parts, three main sign-up windows and a handful of costs that you either pay yourself or hand off to extra coverage.
This page gives you the big picture for 2027. When you want the details on one part, go to our guides to Medicare Part A in 2027 and Medicare Part B in 2027.
Compare 2027 Medicare Supplement Plans
The Four Parts of Medicare in 2027
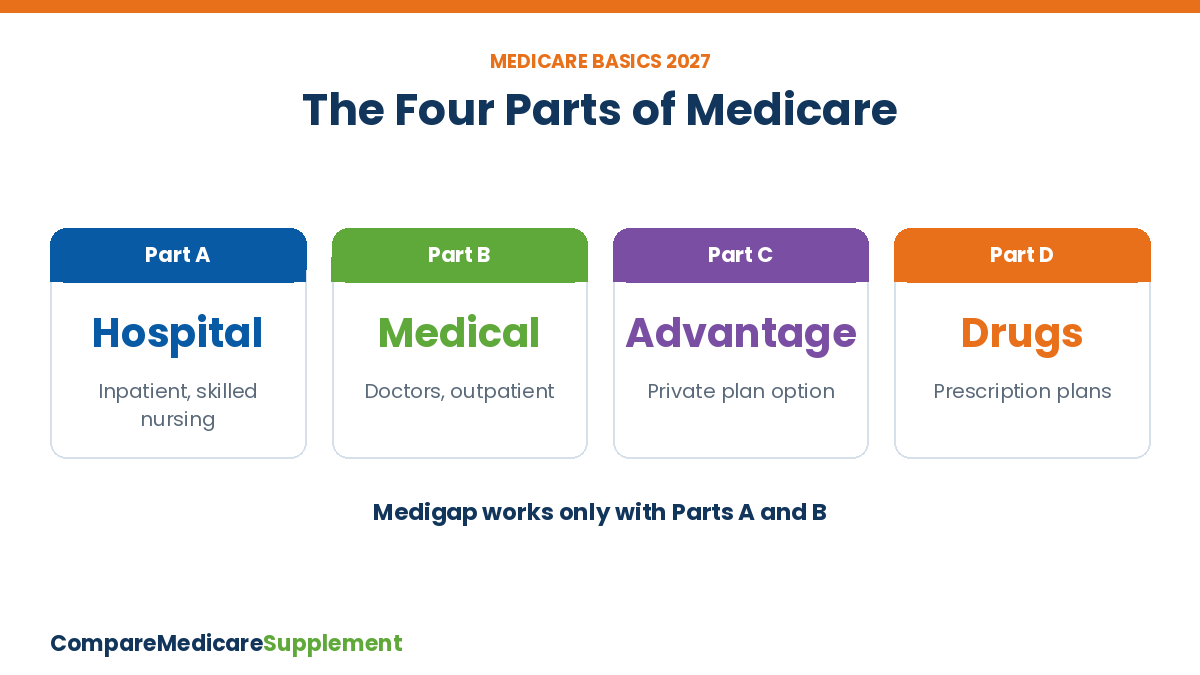
Parts A and B are run by the federal government and together are called Original Medicare. Parts C and D are sold by private insurance companies that Medicare approves.
| Part | What it pays for | Who runs it |
|---|---|---|
| Part A | Hospital stays, skilled nursing after a hospital stay, hospice, some home health | Federal government |
| Part B | Doctors, outpatient care, lab work, imaging, medical equipment, preventive care | Federal government |
| Part C (Medicare Advantage) | Replaces how you get A and B through a private plan, usually with a network | Private insurers |
| Part D | Prescription drugs | Private insurers |
A Medicare Supplement (Medigap) plan is not a part of Medicare. It is private insurance that works only with Original Medicare.
Keep this straight: You choose one of two paths. Path one is Original Medicare plus a Medicare Supplement plus a Part D drug plan. Path two is a Medicare Advantage plan, which usually bundles drug coverage. You cannot use a Medicare Supplement with Medicare Advantage.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll
Who Qualifies for Medicare
Age 65 or older. You qualify if you are a U.S. citizen or a permanent legal resident who has lived here for at least 5 years in a row.
Under 65 with a disability. You generally qualify after getting Social Security disability benefits for 24 months.
Kidney failure or ALS. People with End-Stage Renal Disease, and people with ALS, can qualify at any age. With ALS, Medicare starts as soon as disability benefits start.
Qualifying for Medicare and paying nothing for Part A are two different things. Part A is premium-free if you or your spouse worked and paid Medicare taxes for about 10 years. Everyone pays a monthly premium for Part B.
What Original Medicare Costs: 2026 Actual vs 2027 Projected
Here are the main costs you face with Original Medicare alone. The 2027 numbers are projections from the 2026 Medicare Trustees Report. CMS normally announces the final 2027 amounts in November.
| Cost | 2026 (final) | 2027 (projected) |
|---|---|---|
| Part B monthly premium (standard) | $202.90 | $209.50 |
| Part B yearly deductible | $283 | $292 |
| Part A hospital deductible, per benefit period | $1,736 | $1,788 |
| Part B coinsurance after the deductible | 20% | 20% |
| Yearly cap on what you pay | None | None |
2026 figures: CMS. 2027 figures: 2026 Medicare Trustees Report projections, not final.
Our math: at the projected 2027 rates, a year of Part B premiums ($209.50 x 12 = $2,514) plus the Part B deductible ($292) comes to about $2,806 before you have paid a single coinsurance bill. Higher earners pay more through an income charge called IRMAA.
When to Enroll: Initial, General and Special Enrollment Periods
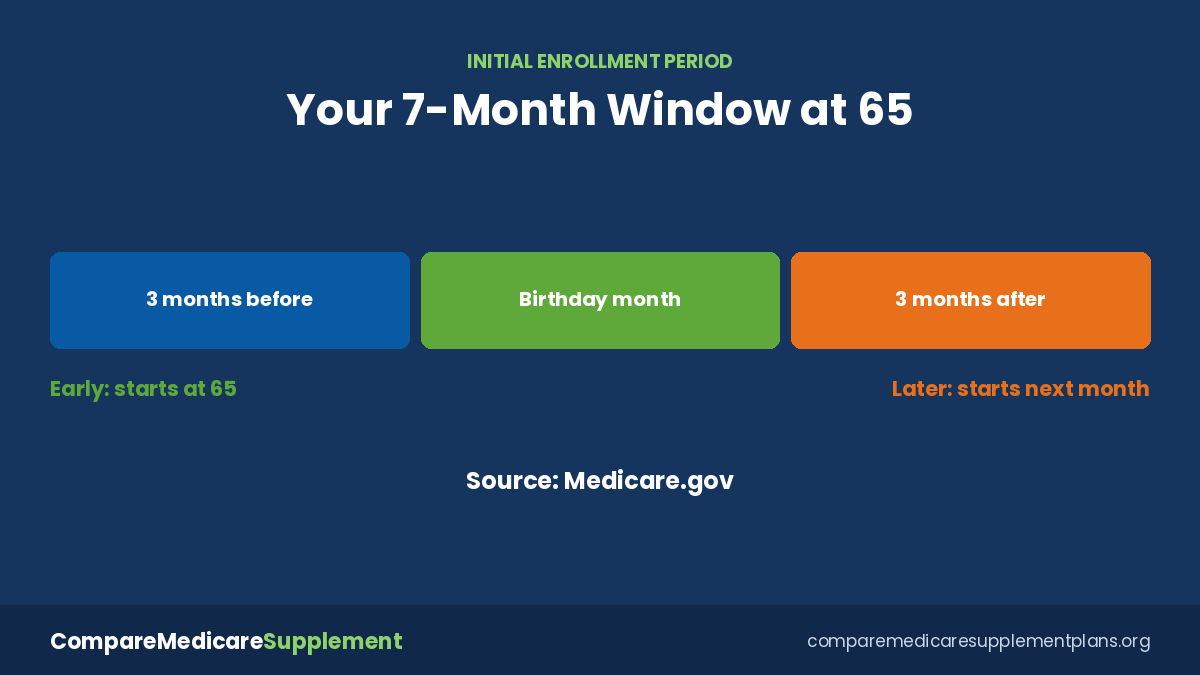
Medicare has three main windows for signing up for Parts A and B. Which one applies depends on your age and whether you have health coverage from a current job.
| Window | When it runs | When coverage starts |
|---|---|---|
| Initial Enrollment Period | 7 months: 3 months before your 65th birthday month, that month and 3 months after | Sign up before your birthday month: the month you turn 65. Sign up later: the month after you sign up. |
| General Enrollment Period | January 1 to March 31 every year | The month after you sign up. A late penalty may apply. |
| Special Enrollment Period | While you have job-based coverage, and up to 8 months after that job or coverage ends | Usually the month after you sign up |
Source: Medicare.gov. COBRA and retiree coverage do not count as coverage from a current job.
Already on Social Security? If you get Social Security benefits for at least 4 months before you turn 65, you are usually enrolled in Parts A and B automatically and your card arrives in the mail.
Late Enrollment Penalties and What They Really Cost
Medicare charges penalties if you skip a part when you should have taken it and had no other qualifying coverage. Most of them last as long as you have that part.
| Part | Penalty rule | Our example (2026 figures) |
|---|---|---|
| Part A (only if you pay a premium) | 10% higher premium, for twice the number of years you waited | Rare: most people get Part A free |
| Part B | 10% for each full 12-month period you went without it, for life | Wait 2 full years: 20% x $202.90 = $40.58 more a month, or $486.96 a year |
| Part D | 1% of the national base premium for each month without drug coverage | 20 months: 20% x $38.99 = about $7.80 more a month, for life |
Our math using 2026 CMS figures. The penalty is recalculated each year, so it grows when the base premium grows.
The Part B penalty is the expensive one. For the full rules on delaying Part B while you still work, see our Part B 2027 guide.
Where a Medicare Supplement Fits In
Original Medicare has no yearly limit on your share of costs. A Medicare Supplement plan pays some or all of the deductibles and the 20% coinsurance, depending on the plan letter you choose.
Get Parts A and B. A Medicare Supplement only works on top of Original Medicare.
Use your 6-month Medigap window. It starts the month you are 65 or older and have Part B. During it, companies cannot turn you down or charge more for health reasons.
Add a Part D drug plan. Medicare Supplement plans do not cover prescriptions. For 2027 Part D has a $2,400 yearly out-of-pocket cap.
Pick a plan letter, then a company. Plan G and Plan N are the most common choices for people new to Medicare.
See every letter side by side in our 2027 Medicare Supplement comparison chart, or weigh the other path in our Medicare Advantage vs Medicare Supplement guide.
Bottom Line
Medicare in 2027 comes down to four parts, three sign-up windows and one big choice: Original Medicare with a Medicare Supplement and Part D, or a Medicare Advantage plan. Sign up for Parts A and B on time to avoid lifelong penalties, and buy your Medicare Supplement during your 6-month window when your health cannot be held against you.
See 2027 Medicare Supplement prices in your ZIP code
Medicare Basics 2027 — Frequently Asked Questions
➤ Is Medicare free when I turn 65?
Part A is free for most people because they or a spouse paid Medicare taxes for about 10 years. Part B is not free: the standard premium is $202.90 a month in 2026 and is projected at $209.50 for 2027.
➤ Will I be signed up for Medicare automatically?
Yes, if you already get Social Security or Railroad Retirement benefits at least 4 months before you turn 65. If not, you have to apply through Social Security during your Initial Enrollment Period.
➤ Can I get Medicare before age 65?
Yes. People who have received Social Security disability benefits for 24 months qualify, and people with End-Stage Renal Disease or ALS can qualify sooner.
➤ What happens if I miss my 7-month enrollment window?
Unless you have coverage from a current job, you wait for the General Enrollment Period from January 1 to March 31. Coverage starts the month after you sign up, and you may owe a lifelong Part B penalty.
➤ Do I need Part B if I am still working?
Not always. If you have health coverage from your own or your spouse’s current job, you may be able to delay Part B without a penalty and use a Special Enrollment Period later. Check with the employer plan first, because small-employer rules can differ.
➤ Does Original Medicare pay for dental, vision and hearing aids?
Generally no. Routine dental cleanings, eyeglasses and hearing aids are not covered by Parts A and B, and Medicare Supplement plans do not add them either.
➤ Is there a limit on what I pay with Original Medicare?
No. Parts A and B have no yearly out-of-pocket cap, which is the main reason people add a Medicare Supplement plan to cap their costs.
➤ Do I need a Medicare Supplement if I have Original Medicare?
You are not required to buy one, but without it you pay all deductibles and the 20% coinsurance with no limit. Many people add one during their 6-month Medigap window when no health questions are asked.
Compare Medicare Supplement Plans
Call a Licensed Agent Now
Compare 2027 Plan G, Plan N and more from several insurance companies in one call.
No obligation to enroll